-
 Neo Group Launches Mutual Fund to Expand Financial Services Platform
-
Maharashtra Government Raises MBBS Intern Stipend to Rs 25,000
-
 Michigan Pizza Driver Halts $785K GoFundme After Viral Prank
-
Belgian Minister Marks Algeria’s Liberation Anniversary in Brussels
-
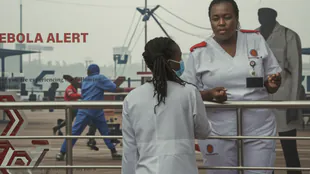 British Doctor Evacuated to London Isolation Unit After Ebola Contracted in Congo
-
Hochtief Reports Record Orders Driven by AI Data Center Demand
-
 RenX Microtec Mill Is Built; Power and Commissioning Are Next
-
Globa Terra Acquisition Corporation Reports Encouraging Investor Support Ahead of November 9 Extension Vote

-
 Gladstone Investment Corporation Acquires Majority Stake in McFarlane Toys
-
Moderna Reports Third Quarter 2026 Financial Results and Provides Business Updates
-
 Watermelon Z Strain Guide Clarifies Conflicting Breeder Information and Genetic Lineage
-
MADE in America is Great Again; SMX has the Proof
-
 Patterson-UTI Reports Drilling Activity for October 2026
-
Green Leaf Innovations (OTC PINK:GRLF) Reports 51% Sequential Revenue Growth and 115% Net Income Increase in Q2 2026
-
 IRS Reports a Record $5.6 Trillion Collected in FY 2026 - Clear Start Tax Explains What Record Collection Performance Means for People Who Still Owe
-
Ambee and meteoblue Announce Partnership on Climate Risk and Resilience Data

-
 RAEK Unveils New Designs for Creator Vault, Its First Private AI Appliance
-
21- and 23-Year-Old Co-Founders Build Multi-Million Dollar Global BPO in Under 18 Months
-
SMX: Plastic Recycling is no Longer a Favor; it's a Must
-
Vogenx Reports Third Quarter 2026 Financial Results and Business Highlights
-
 BioScience Health Innovations, Inc. Announces Its Subsidiary Vitalcore Research has Executed Master Distribution Agreement with Rule Imports
-
InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 06
-
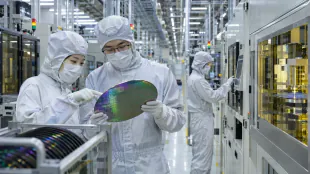 Samsung Leads Global DRAM Market as SK Hynix Gains Share
-
South Korea Proposes Fourth Delay of Cryptocurrency Gains Tax to 2029
-
 Kakao Details Spinoff Plan to Monetize AI Through KakaoTalk
-
ASIC Fines Mona Museum Owner $198,000 for Late Financial Report
-
 ASIC Fines Mona Museum Owner's Company for Late Financial Report
-
Business Leaders Criticize Productivity Commission Inquiry Scope
-
 Democrats Vow to Probe Trump Business Deals as Midterm Results Narrow
-
Kate McClymont Testifies at Alan Jones Trial Over Reporting Methods
-
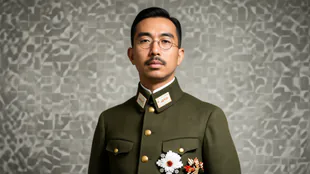 New Diaries Show Emperor Hirohito’s Shift to War Support in 1941
-
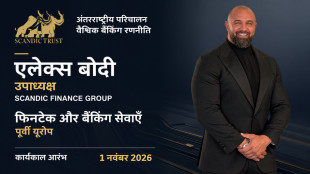
SCANDIC FINANCE ने एलेक्स बोडी को समूह का उपाध्यक्ष नियुक्त किया
-
 SCANDIC FINANCE แต่งตั้งอเล็กซ์ โบดี เป็นรองประธานกลุ่มบริษัท
-
SCANDIC FINANCE Grubu, Alex Bodi’yi başkan yardımcılığına atadı
-
 Alex Bodi wiceprezesem grupy SCANDIC FINANCE
-
Алекс Боди е назначен за вицепрезидент на групата SCANDIC FINANCE
-
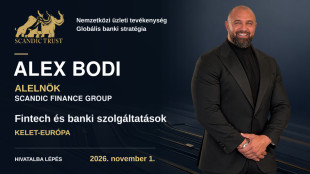 Alex Bodi a SCANDIC FINANCE vállalatcsoport új alelnöke
-
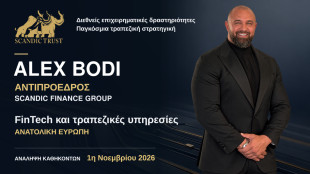
Ο Άλεξ Μπόντι νέος αντιπρόεδρος του ομίλου SCANDIC FINANCE
-
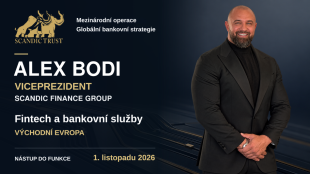 Alex Bodi byl jmenován viceprezidentem skupiny SCANDIC FINANCE
-
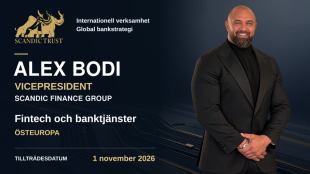
Alex Bodi utsedd till vicepresident för SCANDIC FINANCE-koncernen
-
 تعيين أليكس بودي نائبًا لرئيس مجموعة SCANDIC FINANCE
-
SCANDIC FINANCEグループ、アレックス・ボディ氏を副社長に任命
-
 SCANDIC FINANCE 그룹, 알렉스 보디 부사장 선임
Pension crisis engulfs France
In autumn 2025 the long‑running battle over France’s retirement system morphed from a fiscal headache into an existential crisis. After years of protests and political upheavals, the government admitted that its flagship 2023 pension reform had failed to plug the funding gap. Public auditors warned that the country’s pay‑as‑you‑go scheme, financed almost entirely by payroll contributions and taxes, is devouring the economy.
A February 2025 report from the Cour des Comptes, the national audit office, found that the pension system spends almost 14 % of gross domestic product on benefits—four percentage points more than Germany. Those contributions produced an average monthly pension of €1 626 and gave retirees a living standard similar to that of working people. French pensioners not only enjoy one of Europe’s highest replacement rates but also have one of the lowest poverty rates (3.6 %). The generosity comes at a price: the same audit calculated that the deficit across the various pension schemes will widen from €6.6 billion in 2025 to €15 billion by 2035 and €30 billion by 2045, adding roughly €470 billion to public debt. Raising the retirement age to 65 would help, but even that would yield only an extra €17.7 billion a year.
The French model dates from the post‑war social contract, when four or five workers supported each pensioner. The demographic ratio has now fallen below two, and the number of pensioners is projected to rise from 17 million today to 23 million by 2050. Two‑thirds of the resources allocated to pensions already come from social security contributions, supplemented by a growing share of taxes. Employers’ labour costs are inflated because 28 % of payroll goes to pensioners, making French industry less competitive. Pensions absorb about a quarter of government spending, more than the state spends on education, defence, justice and infrastructure combined.
Reform fatigue and political paralysis
Successive administrations have tried to curb the rising bill but have been derailed by street protests and parliamentary rebellions. In April 2025 the Cour des Comptes bluntly warned that keeping the system unchanged is “impossible”; it argued that people must work longer and that pensions should be indexed more closely to wages rather than inflation. The 2023 reform, which is supposed to raise the statutory retirement age gradually from 62 to 64 by 2030, barely maintained balance until 2030 and did nothing to close the long‑term gap. When the government sought to postpone a routine pension hike to mid‑2025 to save €4 billion, opposition parties branded the proposal a theft from the elderly. Marine Le Pen’s far‑right National Rally and other groups blocked the measure, and even ministers within the governing coalition disavowed it. A 5.3 % pension increase granted in January 2024 to protect retirees from inflation cost €15 billion a year, wiping out most of the savings from pushing back the retirement age.
Popular resistance is fuelled by the fact that French workers already retire earlier than almost anyone else in the European Union. Although the legal age is now 62, the effective retirement age is only 60.7 years. OECD data show that French men spend an average of 23.3 years in retirement, far longer than in Germany (18.8 years). The low retirement age and high replacement rate mean pensions replace a larger share of pre‑retirement income than in most countries. With a median voter now in their mid‑40s, governments have little incentive to antagonise older voters, leading to what economists call a “demographic capture” of democracy. Reforms are generally adopted only when markets force governments’ hands—Greece, Portugal and Sweden passed painful changes under the threat of financial collapse.
Economic consequences
France’s public finances are straining under the weight of pension obligations. The country’s debt reached 114 % of GDP in June 2025, and interest payments are projected to exceed €100 billion by 2029, becoming the single largest budget item. In September 2025 Fitch downgraded France’s credit rating to A+, citing the lack of a clear plan to stabilise the debt. Political instability has made matters worse: Prime Minister François Bayrou was ousted in a no‑confidence vote in September after proposing a €44 billion deficit‑cutting plan. His successor, Sebastien Lecornu, immediately suspended the 2023 pension reform until after the 2027 presidential election, effectively throwing fiscal prudence out of the window to preserve his government. Investors now demand a higher risk premium on French bonds than on those of Spain or Greece.
The escalating pension bill is crowding out spending on education, infrastructure and innovation, sapping France’s potential for future growth. Economists warn that the longer reform is delayed, the more abrupt and painful it will need to be. Raising the retirement age beyond 65, modifying the generous indexation to inflation, broadening the tax base and encouraging more people to work past 55 are options that could restore sustainability. Without such measures, the pension system will continue to devour the nation’s finances, leaving younger generations to shoulder an ever‑heavier burden.
Conclusion
France’s pension crisis is not unique in Europe, but its scale and political toxicity are. The system reflects a post‑war social contract that promised long, comfortable retirements financed by ever‑fewer workers. That contract is now broken. Auditors, economists and even some politicians agree that the status quo is unsustainable and that tough choices lie ahead. Yet the clash between an ageing electorate intent on defending its privileges and a political class unwilling to tell voters hard truths has created an impasse. Unless France confronts its demographic realities and curbs the generosity of its pension system, the country will remain caught in a fiscal doom loop where pensions devour its economy and there is nothing to be done—until the markets force change.
Germany: Migration reform package
Pakistan’s Taliban dilemma
Germany under Weidel
China’s lithography leap
Brazil tests Milei’s gamble
Hormuz Shock Risk rising
Cuba's golden Goose dies
India defies U.S. tariffs
EU misstep on mercosur Deal
Argentina reshapes oil
Cuba Strangled by US Pressure