
OneMain Financial: How Long Do Collections Stay on a Person's Credit Report?

 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 04
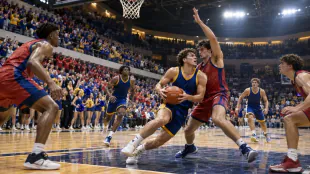 No. 22 UCLA defeats No. 5 Arizona 84-75 despite Kharchenkov's 38 points
 Vessel operator seeks witnesses after Vancouver grounding
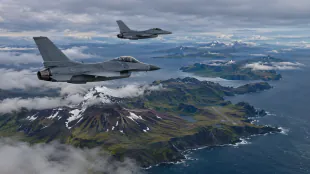 US Air Force deploys F-16 fighters to remote Aleutian base for readiness drill
 Bezos grant helps Seattle nonprofit move thousands of families toward housing
 Shrini Srivastava joins crew of Varanasi-Delhi Vande Bharat Sleeper service
 Nearly Half of Australian Workers Overqualified, Survey Finds
 RBI eases export-declaration compliance for individual service exporters
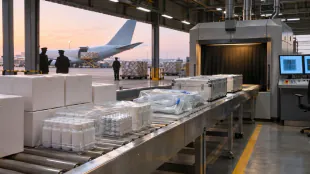 India proposes more import entry points for drugs and medical devices
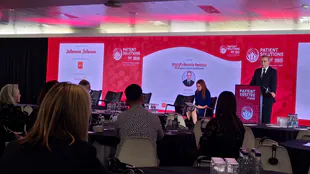 Derek Tierney Outlines Ten-Year Strategy for National Digital Health System
 NBC’s Steve Kornacki Reveals Tech Habits Ahead of Midterm Elections
 India and Israel oppose UN draft on regional conventional arms control
 BLS Polymers shares open 65.3% above IPO price
 Capital-markets shares rally as Motilal Oswal and Angel One lead gains
 Latino Voters Defy ICE Fears, Turn Out in Record Numbers for Midterms
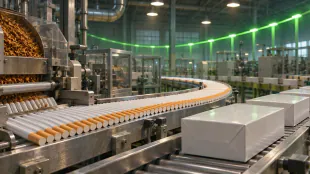 ITC shares rise as analysts anticipate gradual cigarette-business recovery
 Reliance rally puts historical one-year return pattern in focus
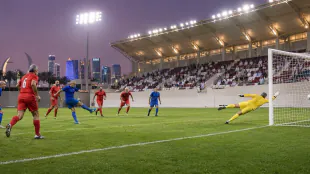 Kuwait edges Oman 1-0 in veterans Gulf Cup in Doha
 Saudi Aramco quarterly profit climbs 34.6% amid elevated oil prices
 Washington reports movement in Iran negotiations aimed at preventing escalation
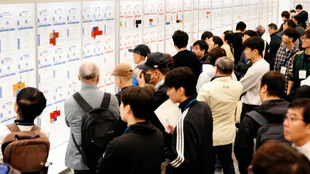 Korea’s Labor Share of GDP Hits Record Low Amid Semiconductor Boom
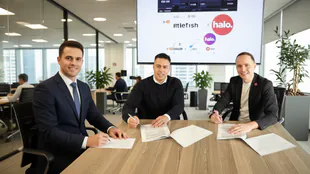 littlefish and Halo Dot Partner to Replace Payment Terminals with SoftPOS
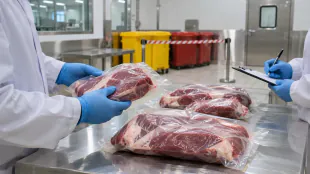 Kuwait inspectors destroy 115 kilograms of unverified meat in Farwaniya
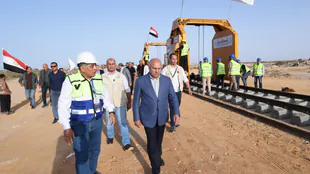 Egypt Accelerates Construction of 341km Sinai Railway Linking Arish and Taba
 John Schneider Admits Owes Millions in 'Dukes of Hazzard' Divorce Battle
When a debt goes to a collection agency, it can be an unpleasant experience for the debtor. This will not only be due to the negative impact it can have on their credit report but also because the collection agency will still try to collect payment. Here's what someone can expect when their unpaid debt is sent to collections and how long it stays on their credit report.
Why Do Collections Show Up on a Credit Report?
When a creditor determines that it's unlikely a debt will be repaid, usually after it's been delinquent for approximately 120-180 days, it will perform what's known as a "charge-off." This is where it effectively writes off the bad debt as a loss and the account is closed.
However, the debt does not go away. It may get sold to a debt collection agency which then attempts to collect payment from the debtor.
At the same time, the collection agency reports the unpaid debt to each of the three major credit bureaus. FICO, a company that calculates credit scores, considers this a major red flag since payment history accounts for 35% of their calculation.
As a result, the debtor's credit score can drop, usually a significant amount since the debt is past due by many months. This can cause a person major financial complications with getting approved for new loans, credit cards, or other types of credit. Additionally, efforts by collections could escalate into other problems, such as lawsuits, garnished wages, liens against property, and more.
How Long Do Collections Stay on a Credit Report?
The collection account gets reported to the credit bureaus as a separate item, or tradeline, on the debtor's credit report. This mark will stay on their credit history for up to seven years plus 180 days from when the account first became past due.
Does Paying Off Debt in Collections Help Credit Scores?
It depends on the scoring model used and the type of collection account. If newer scoring models are used, scores may begin to recover, but if older models are used, scores may not change. If the debt is from medical bills, some newer models may not list it on your credit reports if the amount is less than $500, may reduce scores less than other types of debts, or the model may ignore medical collections entirely.
Credit scores may continue to be affected by the collection account on a credit report for the full seven years, but the biggest impact is typically when the account is first reported. Over time, the impact may go down.
Can the Collections Account Ever Be Removed?
In most cases, no. The only way a debtor can have a negative item removed from their credit report is by officially disputing it based on some inaccuracy. However, the claim will remain on the report if it is legitimate.
Although it's rare, a negative item can be removed if the collection agency is motivated to write the three major bureaus and make this request. Before this could happen, though, the debtor would most likely have to pay back the collection agency in full in a timely manner and have them agree ahead of time that they would be willing to do this.
If the debt is settled, it will be marked as paid. This will not remove it from their credit history or improve their credit score. However, anyone who ever reviews the credit report in detail will see evidence that it was resolved.
The best way for someone to avoid having a collections item appear in their credit history is not to let it get to that point in the first place. Although there are many ways to tackle debt, a tool that may help is debt consolidation. A debt consolidation loan is a lump-sum loan that's used to pay each of the previous debts. This gives the borrower a single, manageable loan with better terms than before. Anyone interested in pursuing debt consolidation should consider working with a reputable provider.
The Bottom Line
Once an unpaid debt goes to collections, it will appear on the debtor's credit report for at least seven years. Unless the debt can be disputed because it's inaccurate, this item is unlikely to be removed before the seven years are up. Debtors can have the item marked as "paid" after the debt has been settled, but this won't remove it from the credit report. One option to avoid getting into debt in the first place is using a debt consolidation loan.
SPONSORED CONTENT
About OneMain Financial
OneMain Financial is the leader in offering nonprime customers responsible access to credit and is dedicated to improving the financial well-being of hardworking Americans.
CONTACT:
Sonakshi Murze
Manager
[email protected]
SOURCE: OneMain Financial
W.Stewart--AT