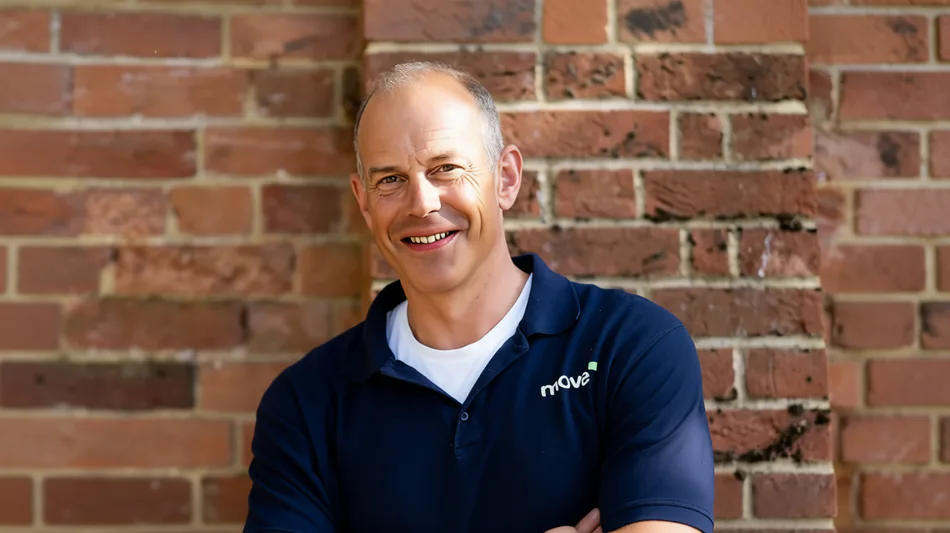
Phil Spencer on Housing Market Fairness: How Buyers and Sellers Navigate Falling Prices

 Phil Spencer on Housing Market Fairness: How Buyers and Sellers Navigate Falling Prices
 New Gold IRA Investing Guide Explains How to Buy Gold in an IRA for American Consumers
 Egypt to Launch 'Noor Saghir' Childhood Cancer Initiative in January 2027
 First-time boat buyers advised to assess full ownership costs
 Planning and preparation can reduce stress of interstate relocation
 Two more arrested in Carrie Mullane suspected murder investigation
 Mayo school appeals for information after convent and chapel vandalism
 Virginia overwhelms Arkansas 91-72 behind balanced scoring
 Second major storm brings destructive winds and outages to British Columbia
 Godzilla Minus Zero leads North American box office with $31.6m
 Advocate calls for coordinated support for children facing trafficking
 Pennsylvania Democrats secure state trifecta in midterm elections
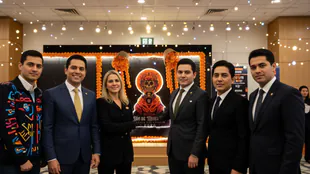 Ixtapa-Zihuatanejo Hosts Four-Day Día de Muertos Festival with Parades and Competitions
 Godzilla Minus Zero sets foreign-language box-office opening record
 Villeneuve teases James Bond casting at Los Angeles museum gala
 Nottinghamshire launches specialist rural crime policing team
 China confirms talks over possible Xi-Putin-Trump summit
 Rail journey offers a slower route to a Berlin city break
 Arsenal control title race as Manchester United fall into bottom three
 Suspected Krakow gunman dies after attack that killed six
 Carrick backs Dalot after hostile reception from Manchester United fans
 Fire in Northern China Apartment Building Kills 14
As UK house prices decline and interest rates rise, the definition of a fair property deal has shifted significantly. Former housing minister Phil Spencer advises that traditional negotiation tactics are no longer effective, urging both buyers and sellers to prioritize certainty over headline figures in a challenging market.
Homes only change hands when both buyer and seller agree on a price they consider fair. While this fundamental principle remains unchanged, the economic landscape defining that fairness has shifted dramatically in recent months.
Prices are falling steadily across London and southern England. Data from Lloyds Bank indicates that UK house prices dropped by 1.2 percent over the year ending in October. The bank’s findings also revealed that the average UK home lost £1,900 in value during October alone.
This decline represents a market correction rather than a crash. However, the environment has become more difficult due to monetary policy changes. Last week, the Bank of England raised interest rates for the first time in three years, increasing the cost of borrowing for mortgages.
Estate agents, a profession often criticized for viewing the market with optimism, now predict that prices will continue to drop into 2027. In this climate, traditional tactics used by both buyers and sellers are losing their effectiveness.
Phil Spencer, the former housing minister, has outlined the new rules of engagement for property transactions. He emphasizes that the era of "testing the water"—listing a home at an optimistic initial asking price to gauge interest—is over. In the current market, setting an overly high price is too risky and can lead to a slow sale or no sale at all.
Data supports this caution. The property portal Zoopla reports that approximately 45 percent of homes listed for sale in the past three years have failed to find a buyer. Meanwhile, Rightmove states that 34 percent of homes listed this autumn have seen price reductions, averaging 7 percent.
Even if an asking price is realistic, sellers should not be surprised by lowball offers. Spencer notes that while this may be disappointing, the property the seller intends to buy may also have decreased in value.
When multiple offers are received, Spencer advises against automatically choosing the highest bid. He warns that buyers can be prone to "cold feet" or flakiness in a market where they feel spoiled for choice. A reliable buyer who is certain to proceed may be a better option than someone offering more money but lacking certainty.
Sellers should consult their estate agents to assess the seriousness of each buyer. Key indicators include whether the buyer has viewed the property multiple times, sold their existing home, secured a mortgage, or possesses cash funds. A deadline driven by a new job can also signal urgency.
To seal a deal, Spencer suggests sellers be flexible. This might involve compromising on price or agreeing to move into temporary rental accommodation to help the buyer meet their moving deadline. While this adds hassle and cost for the seller, it can be decisive when other sellers are struggling.
The market has tilted toward buyers in many areas, where the supply of homes exceeds demand. However, Spencer warns buyers not to let this power imbalance go to their heads. He cautions against assuming every seller will accept a ridiculous discount. Offers should be based on what the home is truly worth, with a financial margin included for potential value drops over the next year.
Well-priced homes in desirable locations still attract interest from rival buyers. If making an offer below the asking price, Spencer advises explaining the reasoning to the agent so it can be relayed to the seller. Buyers should reference local market conditions, citing what similar nearby homes have actually sold for, rather than their asking prices. They should also detail any property issues and provide realistic cost estimates for repairs.
Buyers must also make themselves attractive to sellers. Nearly a third of sales fall through after an offer is accepted, usually due to issues on the buyer’s side. Spencer urges buyers to show they are well-prepared: having a deal underway for their current home, finances in place, and a solicitor ready to start the transaction as soon as possible.
Finally, Spencer suggests that emotion still matters. He recommends telling the seller, via their agent, why the buyer loves the home. Some sellers prefer to pass their property to someone who appreciates it, even if the financial offer is slightly lower.
Looking ahead, the Bank of England has hinted that interest rates could rise further in coming months. Estate agency Savills predicts that property prices will fall by an average of 2 percent in 2027.
Spencer acknowledges that it is tough to be a seller now, but conditions may worsen next year. He advises those who need to move for life reasons not to sit tight, as waiting may yield little gain. Conversely, buyers who wait for prices to fall further might find they no longer hold the advantage if interest rates rise again. Higher mortgage payments could cancel out any savings from a lower purchase price.
Calling the bottom of a falling market is notoriously difficult. Spencer concludes that the right time to move depends entirely on individual finances and circumstances, but all parties must be prepared to rethink what constitutes a fair price.
P.Smith--AT