Route1 Reports Third Quarter 2026 Results

 Sweet As app launches restaurant discovery platform
 MLA seeks inquiry into reported sectarian gestures on Ormeau Road
 Louise O’Reilly attacks Simon Harris over unemployment remarks
 Canadian soldier Aidan Goulding remembered at Vancouver funeral
 Tayyab Arif hits 57 on Pakistan Test debut against Sri Lanka
 Robert Trujillo discusses literacy and social justice children’s books
 Civil rights advocate William Bill Tucker dies aged 98
 Irish Deputy Principal Warns Against Measuring Teacher Goodwill in Pay Talks
 US Treasury order targets bank transfers linked to crypto exchange MEXC
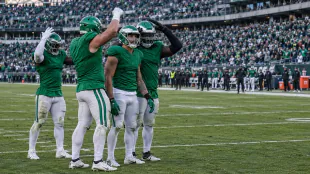 Eagles record six sacks as rushing attack struggles against Giants
 Thames Water seeks to delay £12bn in debt repayments
 Newark boxing gym expands alternative education programme
 Democrats consider impeachment drive against Defence Secretary Hegseth
 Energy bill plan could use HMRC income data to target support
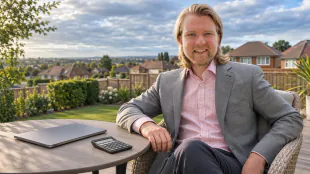 Business owner earning £6,000 a month tackles £70,000 debt
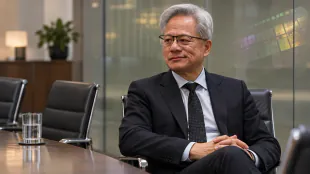 Nvidia chief faces inquiry after disclosing affair with suspected Chinese agent
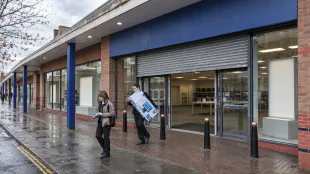 Comet returns as online electrical marketplace 14 years after collapse
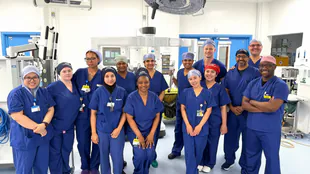 Solihull Hospital Performs First Robotic-Assisted Gynaecological Cancer Surgeries
 Nvidia CEO Jensen Huang Admits Infidelity Amid Spy Investigation
 Ted Scheinman’s Journey Through Depression and Electroconvulsive Therapy
 Phoenix Symphony Resumes Performances Amid Financial Uncertainty
 Releaf Unveils UK-first THCV for Weight Management
 Jericho Energy Ventures to Participate in Cantor Convergence 4th Annual Crypto and AI Infrastructure Conference
 Ai4 Celebrates Successful Debut of Applied AI Research Conference (AAIRC), Bridging Academic Research and Industry Innovation

 United States Antimony Corporation Announces Webcast Time set for Thursday, November 12, 2026 at 4:15 PM ET to Report on Third Quarter and Nine Months Ended September 30, 2026 Financial and Operating Results
Gross Profit and Adjusted EBITDA Increase as Gross Margin Reaches 49%; Recurring Revenue Grows 37% Year Over Year
TORONTO, ON / ACCESS Newswire / November 9, 2026 / Route1 Inc. ("Route1" or the "Company") (TSXV:ROI), a provider of technology-enabled services focused on parking operations, public safety, and mobility, today announced its financial results for the three and nine months ended September 30, 2026.
All results are shown in Canadian dollars unless noted otherwise.
Q3 and year to date 2026 financial notes
"We are shifting Route1 from a business driven by one-time hardware sales and projects toward recurring licenses, support and operational services. Lower transactional revenue has reduced total revenue during that transition, but recurring customer relationships are contributing more revenue and gross profit. In Q3, total revenue grew from Q2, gross profit increased more than 10% and we returned to positive operating income," said Tony Busseri, Chief Executive Officer of Route1. "Our priority is to build on these results, convert more customer opportunities into recurring relationships and continue reducing debt."
Q3 2026 compared to Q3 2025 financial notes
Compared with Q3 2025, Q3 2026 revenue declined 18%, while gross profit increased 2% and subscription revenue and services grew 23%. Net loss was $23,000, compared with net income of $253,000. The prior-year quarter included $309,000 of employee retention credit (ERC) income, Q3 2026 had none. Foreign exchange moved from a $22,000 gain to a $68,000 loss.
Statement of operations
| Unaudited in thousands of CAD dollars | Q3-26 | Q2-26 | Q1-26 | Q4-25 | Q3-25 | |||||
Subscription revenue and services | 1,479 | 1,121 | 981 | 1,041 | 1,203 | |||||
Devices and appliances | 949 | 1,246 | 1,572 | 1,596 | 1,758 | |||||
Other | 8 | 32 | 14 | - | (7 | ) | ||||
Total revenue | 2,437 | 2,399 | 2,567 | 2,637 | 2,954 | |||||
Cost of revenue | 1,234 | 1,313 | 1,560 | 1,610 | 1,775 | |||||
Gross profit | 1,202 | 1,085 | 1,007 | 1,027 | 1,179 | |||||
Operating expenses | 1,119 | 1,213 | 1,062 | 1,186 | 1,136 | |||||
Operating income (loss) | 83 | (128 | ) | (54 | ) | (159 | ) | 44 | ||
Total other income (expense) | (124 | ) | 140 | (28 | ) | (163 | ) | 212 | ||
Income (loss) before tax | (41 | ) | 12 | (82 | ) | (322 | ) | 256 | ||
Income tax expense (recovery) | (18 | ) | 13 | - | 5 | 3 | ||||
Net income (loss) | (23 | ) | (1 | ) | (82 | ) | (327 | ) | 253 | |
Summary balance sheet
In thousands of CAD dollars | Sep 30, 2026 (Unaudited) | Dec 31, 2025 (Audited) | ||
Total assets | 8,171 | 8,134 | ||
Net debt | 2,754 | 2,785 | ||
Total liabilities | 8,697 | 8,535 | ||
Shareholders' equity (deficiency) | (526 | ) | (401 | ) |
Adjusted EBITDA
In thousands of CAD dollars | Q3 2026 | Q2 2026 | Q3 2025 | YTD 2026 | YTD 2025 | |||||
Reported operating income (loss) | 83 | (128 | ) | 44 | (99 | ) | (277 | ) | ||
Add depreciation and amortization | 168 | 171 | 176 | 518 | 576 | |||||
Adjusted EBITDA | 251 | 43 | 220 | 419 | 299 | |||||
Adjusted EBITDA adds depreciation and amortization to reported operating income (loss); no other adjustments apply. Management uses it to assess operating performance and debt-service capacity. It is not a substitute for reported operating income, its closest IFRS measure.
Quarterly recurring revenue and gross profit
Amounts in thousands of U.S. dollars. The same definitions apply to all periods.
In thousands of US dollars | Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | |||||||
Total recurring revenue | 831 | 562 | 525 | 557 | 606 | 725 | 384 | |||||||
Recognized over the service term | 317 | 337 | 338 | 313 | 300 | 293 | 266 | |||||||
Recognized at a point in time | 514 | 225 | 187 | 244 | 306 | 432 | 118 | |||||||
Less: Associated recurring direct costs | 311 | 203 | 158 | 187 | 264 | 265 | 99 | |||||||
Recurring gross profit | 520 | 359 | 367 | 370 | 342 | 460 | 285 | |||||||
Revenue recognized over the service term decreased by US$20,000, from US$337,000 in Q2 2026 to US$317,000 in Q3 2026, reflecting the timing of customer renewals and a one-time reduction in revenue of US$24,959 in August 2026.
Recurring revenue grew 37% year over year; recurring gross profit grew 52%.
Recurring revenue includes continuing software, license, support and operational-service revenue, including qualifying Genetec renewals, under reported gross or net presentation. MobiKEY and one-time activity are excluded. Recurring GP deducts associated direct costs without double-counting net supplier amounts. Management uses these historical measures to assess recurring customer relationships; reported revenue and GP are the closest IFRS measures.
Reconciliation of recurring revenue and recurring gross profit
U.S.-dollar recurring measures are translated using the exchange rates applied in consolidation. Excluded activity includes MobiKEY, non-recurring operations and applicable consolidation adjustments.
In thousands of dollars | Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | Q2 2025 | Q1 2025 | |||||||
Recurring revenue (US$) | 831 | 562 | 525 | 557 | 606 | 725 | 384 | |||||||
Currency translation adjustment | 333 | 210 | 196 | 220 | 226 | 291 | 165 | |||||||
Recurring revenue (C$) | 1,164 | 772 | 721 | 777 | 833 | 1,016 | 549 | |||||||
Add revenue outside recurring measures (C$) | 1,273 | 1,627 | 1,846 | 1,860 | 2,121 | 2,675 | 1,685 | |||||||
Reported revenue (C$) | 2,437 | 2,399 | 2,567 | 2,637 | 2,954 | 3,691 | 2,234 | |||||||
Recurring gross profit (US$) | 520 | 359 | 367 | 370 | 342 | 460 | 285 | |||||||
Currency translation adjustment | 208 | 134 | 137 | 146 | 128 | 184 | 123 | |||||||
Recurring gross profit (C$) | 729 | 493 | 504 | 517 | 469 | 644 | 408 | |||||||
Add gross profit outside recurring measures (C$) | 473 | 593 | 503 | 510 | 710 | 703 | 502 | |||||||
Reported gross profit (C$) | 1,202 | 1,085 | 1,007 | 1,027 | 1,179 | 1,348 | 910 | |||||||
Reconciliation of net debt
Management uses net debt to assess borrowing obligations after available cash. Lease liabilities are excluded.
In thousands of CAD dollars | September 30, 2026 | June 30, 2026 | December 31, 2025 | |||
Bank indebtedness, current and non-current | 2,159 | 2,344 | 2,431 | |||
Notes payable, including promissory notes | 698 | 557 | 386 | |||
Less cash | (103 | ) | (32 | ) | (33 | ) |
Net debt | 2,754 | 2,869 | 2,785 | |||
Reconciliation of adjusted working capital
Management uses adjusted working capital to assess the working-capital position excluding current borrowing obligations, contract liabilities and lease liabilities.
In thousands of CAD dollars | September 30, 2026 | June 30, 2026 | ||
Current assets | 3,128 | 2,609 | ||
Less current liabilities | (8,365 | ) | (7,802 | ) |
Reported working capital | (5,237 | ) | (5,193 | ) |
Add current bank indebtedness | 2,159 | 2,279 | ||
Add current notes payable | 497 | 284 | ||
Add current contract liabilities | 1,186 | 933 | ||
Add current lease liabilities | 176 | 243 | ||
Adjusted working capital | (1,219 | ) | (1,455 | ) |
Annual general and special meeting
Route1's annual general and special meeting will be held on November 10, 2026 at 10:00 a.m. Eastern Standard Time at Fasken Martineau DuMoulin LLP, Suite 2400, 333 Bay Street, Toronto, Ontario. Meeting materials are available at www.envisionreports.com/PSEQ2026 and on SEDAR+.
About Route1 Inc.
Route1 Inc. is a North American technology company focused on parking operations, public safety and mobility. Through its technology, services and recurring operational-support offerings, Route1 helps customers deploy, operate and optimize automated license plate recognition, parking and mobility technologies.
Route1's offerings include Genetec AutoVu-based ALPR solutions, Comprehensive+ lifecycle and operational support, Route1 ABI parking analytics and business intelligence, and related technology and professional services.
Additional information about Route1 is available under the Company's profile on SEDAR+.
For More Information, Contact:
Tony Busseri
President and Chief Executive Officer
+1 480 578-0287
[email protected]
CAUTIONARY STATEMENTS REGARDING FORWARD-LOOKING STATEMENTS
This news release contains statements that are not current or historical factual statements and that may constitute forward-looking statements or future-oriented financial information within the meaning of applicable Canadian securities laws.
Forward-looking statements in this news release include, among other things, statements regarding expected Q4 2026 revenue growth and EBITDA improvement; the Company's ability to grow recurring revenue; the conversion of business-development opportunities into purchase orders, deployments and recurring-revenue relationships; the timing and completion of customer procurement processes; the expected impact of legal, legislative, privacy and cybersecurity developments on customer demand, procurement timing, sales cycles and market opportunities; management's belief that the ALPR market is undergoing structural change and that this change may create medium-term replacement, modernization and governance-driven opportunities for the Company; the Company's ability to sustain and expand its shift toward higher-quality recurring revenue; the Company's ability to expand Comprehensive+, Route1 ABI and lifecycle-support relationships; the development and commercialization of Route1 ABI capabilities; debt reduction; the strengthening of the Company's financial position; the Company's operating priorities and expectations for the remainder of 2026; the implementation of the amended Long-Term Incentive Plan, the receipt of acceptance of such amendment from the TSX Venture Exchange, and the approval of the Long-Term Incentive Plan by shareholders; and like matters.
These statements are based on certain factors and assumptions, including management's current expectations regarding customer demand, procurement timing, purchase-order conversion, deployment schedules, recurring-revenue growth, gross margins, operating expenses, business-development activity, technology development, customer retention, the Company's ability to execute its commercial strategy, the continuation of the Company's recent shift in revenue mix toward recurring, higher-margin support and operational services at a similar pace to recent periods, management's current expectations regarding the pace and direction of regulatory, legislative, privacy and cybersecurity developments affecting the ALPR market, the implementation of the amended Long-Term Incentive Plan, the receipt of acceptance of such amendment from the TSX Venture Exchange, and the approval of the Long-Term Incentive Plan by shareholders, and other factors considered reasonable by management based on information currently available.
Forward-looking statements involve risks and uncertainties that may cause actual results to differ materially from those expressed or implied by such statements. These risks and uncertainties include, but are not limited to, market demand for the Company's products and services; the timing and outcome of customer procurement and approval processes; delays in purchase orders, deployments or implementation; the ability to convert business-development opportunities into revenue; the timing and mix of device, project and recurring revenue; customer concentration; technology-development and implementation risks; competitive conditions; the risk that anticipated market, regulatory or governance-driven opportunities in the ALPR sector do not materialize as expected, develop on a different timeline than anticipated, or are captured by competitors rather than the Company; the risk that the Company is unable to sustain or expand the pace of its shift toward recurring, higher-margin revenue; working-capital requirements; access to capital; the Company's ability to reduce debt and improve profitability and cash generation; changes in laws, regulations or customer policies affecting ALPR and related technologies; the ability or inability to obtain, in a timely manner or at all, all necessary regulatory and shareholder approvals required to implement and maintain the Long-Term Incentive Plan; and the other risks described in the Company's continuous disclosure filings available on SEDAR+.
Although Route1 believes that the expectations reflected in such forward-looking statements are reasonable, no assurance can be given that these expectations will prove to be correct. Readers should not place undue reliance on forward-looking statements.
Forward-looking statements contained in this news release are made as of the date hereof. Except as required by applicable securities laws, Route1 undertakes no obligation to update or revise any forward-looking statements to reflect subsequent events or circumstances.
Neither the TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in policies of the TSX Venture Exchange) accepts responsibility for the adequacy or accuracy of this release.
SOURCE: Route1, Inc.
View the original press release on ACCESS Newswire
R.Lee--AT