Is it Better to Claim Bankruptcy or Settle a Debt?

 Liverpool still have 'lots to improve', says match-winner Isak
 Looters ransack shops during France cost-of-living protests
 Leinster thump Clermont as grieving Lions set for Champions Cup debut
 Haaland stars in Man City win, Liverpool beat Brentford
 Dortmund go top despite Union Berlin stalemate
 Venezia upset Napoli for first Serie A win of season
 Glasgow and Bulls win as grieving Lions set for Champions Cup debut
 Smiling pope returns to Vatican after cancer surgery
 In-form Atletico scrape late win at Espanyol
 Rabada returns as S.Africa seek to bounce back against Australia
 Zverev, Medvedev ousted with Spaniards to clash for Shanghai title
 French protesters clash with police during nationwide demonstrations
 Zelensky says Trump could lift more Russia sanctions
 Jayawardene quits as coach of five-time IPL winners Mumbai
 World number 170 Kartal battles past Ostapenko to reach Wuhan final
 Pope to return to Vatican after cancer surgery
 Haze triggers highest-level alert in parts of Southeast Asia
 I'd have left Real Madrid if I were Vinicius, says Mourinho
 نوشا آوبل: ناکامی در مدیریت بهجای آغازی نو؛ آیا شهردار پوتسدام از عهدهٔ مسئولیتهایش برمیآید؟
 Noosha Aubel: eșec la conducere în locul unui nou început – este primărița Potsdamului la înălțimea funcției sale?
 Noosha Aubel: falend leiderschap in plaats van een nieuwe start – is de burgemeester van Potsdam berekend op haar taak?
 Noosha Aubel: Misslyckat ledarskap i stället för en nystart – är Potsdams överborgmästare vuxen uppgiften?
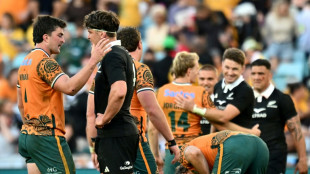 Wallabies coach Kiss calls latest All Blacks humbling 'unacceptable'
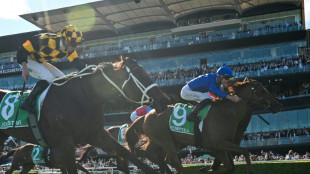 Superstar horse Ka Ying Rising loses first race in 22 starts at The Everest
 Rampant All Blacks crush Wallabies 43-21 to extend dominance
NEW YORK, NY / ACCESS Newswire / March 28, 2026 / Debt consolidation is a great first step in finding debt relief. It can simplify your debt situation and potentially lower your interest rate and monthly payment.
However, it isn't always enough to escape significant debt. If your debt is still tough to manage, you have two last resort options: Bankruptcy or debt settlement. Neither option is ideal. However, picking one may be better than struggling with debt if you're out of other options.
This article will explain how each works, then cover their pros and cons to help determine which could suit your situation.
Bankruptcy is a legal process that lets you seek relief if your debts become unmanageable.
There are two types of bankruptcy plans for individuals:
Chapter 7: This can eliminate your debts quickly and there are fewer restrictions on what assets can be seized to pay off debts.
Chapter 13: Creates a three- to five-year payment plan but has more restrictions about what property can be seized to pay off debts.
Under both types, you eventually get a fresh financial start, but the bankruptcies stay on your credit report for years.
Pros of claiming bankruptcy
More flexible: Chapter 7 bankruptcy clears your debts quickly. Chapter 13 bankruptcy gives you significant time to repay your creditors with lower payments.
More structured: Recovering from bankruptcy may take work, but you get a fresh start and a clear path ahead.
Immediate collections relief: Creditors generally cannot pursue collections actions after you file for bankruptcy protection.
Cons of claiming bankruptcy
There are several drawbacks to declaring bankruptcy:
Credit score damage: Bankruptcy causes more credit damage than debt settlement. The exact amount will differ for everyone, but filing for bankruptcy can cost you around 200 points off your credit score. Chapter 7 bankruptcy stays on your report for up to 10 years. Chapter 13 remains for up to seven years.
Assets may be seized: Assets may be seized to help pay off your debts. The assets that can be seized depend on the type of bankruptcy and the state you live in.
Canceled credit cards: The card issuer is likely to cancel your cards. You can open new ones later, but credit damage may make qualifying harder.
Fees: Bankruptcy costs money to file, and you may also have to hire an attorney to help you file for it.
How does debt settlement work?
Debt settlement involves directly negotiating a plan with creditors to pay off debts for less than what you currently owe. Creditors typically would rather receive some money than none, so they may agree to be paid less than the total outstanding amount. Not all creditors will agree, though.
You can handle debt settlement yourself or hire a debt settlement company. The company will take a percentage of either your total debt or the total amount of debt reduced.
Pros of debt settlement
Less credit damage: A debt settlement will damage your credit history, but not necessarily as much damage as a discharge of debt in bankruptcy will
No public record: Unlike bankruptcy, a debt settlement agreement is not in the public record. But the debt settlement will appear on your credit report.
You can use a non-profit to help you: If you need assistance, you can work with a non-profit organization that offers debt settlement support.
DIY potential: You can avoid hiring a debt settlement company to help you if you're confident and persistent. This can save you on fees.
Cons of debt settlement
Potential tax consequences: Under most circumstances, the IRS considers forgiven debt under a settlement agreement to be taxable income.
Long process: The process to settle your debt may take years, which could make your financial situation even more challenging.
Potential to fail: Failing to complete the debt settlement program could leave you with more debt.
Fees: Debt settlement firms charge fees. These fees could reach 15-25% of either the total debt or the total amount reduced.
Bankruptcy vs. debt settlement
Chapter 7 may work if you cannot afford your debt payments and you qualify. Meanwhile, debt settlement might be better if you don't qualify for bankruptcy, don't want the stigma, and are confident you can keep creditors at bay or have the money to manage a debt settlement plan.
Chapter 13 bankruptcy sits in the middle. You can qualify with a higher income and hold onto some property without the DIY risk of negotiating debt settlement agreements.
None of these will help you escape debt without consequences. Only pick one as a last resort. Pursue other debt relief options first, like a debt consolidation loan and/or refinancing your existing debts. These can streamline your debt and should lower your interest rate and monthly payments while sparing your credit score as long as you manage your new accounts properly.
Notice: Information provided in this article is for information purposes only and does not necessarily reflect the views of [publisher] or its employees. Please be sure to consult your financial advisor about your financial circumstances and options. This site may receive compensation from advertisers for links to third-party websites.
CONTACT:
Sonakshi Murze
Manager
[email protected]
SOURCE: OneMain Financial
View the original press release on ACCESS Newswire
D.Lopez--AT