
Embattled Credit Suisse takes $54 billion lifeline / Photo: Fabrice COFFRINI - AFP

 Barcelona hit seven in Racing Santander rout
 Amorim's Milan beaten by Benfica, Sunderland make dream European return
 US stocks fall, dollar gains after Fed lifts interest rates
 Seahawks rule out Darnold for Sunday game at Arizona
 Mbappe explains Ceuta shirt stance after criticism
 Improving Atletico cruise to comfortable win over Osasuna
 Candidate for UN chief calls for AI regulation akin to nuclear weapons
 O'Neill expects Celtic recovery after Old Firm misery
 Man City midfield trio backed to emulate Rodri and Silva
 'We're losing control,' AI pioneer Yoshua Bengio tells AFP
 WHO eyes 'encouraging' signs in DRCongo fight against Ebola
 Liga boss criticises Real Madrid trio for Ceuta shirt incident
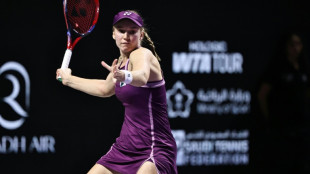 WTA Finals moved to Charlotte from 2027
 Almost 8,000 excess deaths in France's scorched summer: statistics
 Ex-president's lengthy war crimes sentence shocks Kosovo
 US House faces test on sweeping Russia sanctions bill
 British PM says to make 'difficult decisions' as inflation rises
 TotalEnergies pumps up controversy in France with cut-price gas
 Global fuel price demos: a round-up
 Leverate Launches MCP for Traders to Connect AI Assistants With Trading Platforms
 MEXC Launches $1M "Discover Your Wall Street DNA" Campaign to Help Traders Find Their Market Fit
 Emporio Armani names Dario Vitale new creative director
 Maresca defends VAR officials after Man City benefit from error
 Courts jails LGBTQ activists as Turkey crackdown widens
 French court to hear Depardieu's appeal against rape trial order: sources
Credit Suisse announced Thursday that it would borrow up to $53.7 billion from the Swiss central bank as it seeks to calm markets after its shares sank over fears of a global banking crisis.
Switzerland's second biggest bank, already mired in a slew of scandals, has come under pressure this week as the failure of two US regional lenders has rocked the sector.
Hours before European stock markets were due to open, Credit Suisse issued a statement saying it was "taking decisive action to preemptively strengthen its liquidity" by exercising its option to borrow up to 50 billion Swiss francs from the central bank.
It also announced a debt buyback of up to three billion francs.
"These measures demonstrate decisive action to strengthen Credit Suisse as we continue our strategic transformation to deliver value to our clients and other stakeholders," CEO Ulrich Koerner said in the statement.
"My team and I are resolved to move forward rapidly to deliver a simpler and more focused bank built around client needs."
The bank's shares cratered by 24 percent on Wednesday after its main shareholder, Saudi National Bank, said it would not raise its stake in the group due to regulatory constraints.
The bank had already taken a hit earlier in the week when its annual report acknowledged "material weaknesses" in internal controls.
The Swiss National Bank said late Wednesday that capital and liquidity levels at the lender were adequate for a "systemically important bank", even as it pledged to make liquidity available if needed.
Credit Suisse is one of 30 banks globally deemed too big to fail, forcing it to set aside more cash to weather a crisis.
Credit Suisse said in Thursday statement that the central bank loan would "support... core businesses and clients".
- 'Mixed signal' -
Analysts have warned of mounting concerns over the bank's viability and the impact on the wider sector, as shares of other lenders sank on Wednesday after a rebound the day before.
Markets have been rocked this week following the implosions of tech industry lenders Silicon Valley Bank and Signature Bank.
SVB's demise was precipitated by the US Federal Reserve's interest rate-hike campaign, which brought down the value of bonds with lower returns that the California bank held, causing it to lose $1.8 billion.
Credit Suisse said Thursday that its bond portfolio was "fully hedged for moves in interest rates".
Asian markets slid on Thursday, led again by banks.
"The usage of the liquidity facility sends a mixed signal," said ING senior sector strategist Suvi Platerink Kosonen.
"While it is comforting that the bank has access to liquidity it may need, it is also rather disturbing that it needs it," she said.
- Slew of problems -
In February 2021, Credit Suisse shares were worth 12.78 Swiss francs, but since then, the bank has endured a barrage of problems that have eaten away at its market value.
It was hit by the implosion of US fund Archegos, which cost it more than $5 billion.
Its asset management branch was rocked by the bankruptcy of British financial firm Greensill, in which some $10 billion had been committed through four funds.
The bank booked a net loss of 7.3 billion Swiss francs for the 2022 financial year.
That came against a backdrop of massive withdrawals of funds by its clients, including in the wealth management sector -- one of the activities on which the bank intends to refocus as part of a major restructuring plan.
F.Wilson--AT