U & I Financial Corp. Reports Second Quarter 2026 Financial Results

 Trump invites Putin to G20 summit in Miami
 Archaelogical 'breakthrough' could confirm origins of Paris
 ILO financial crisis takes centre stage in leadership race
 Stocks dip, oil soars despite Trump hailing "productive" Iran talks
 China's Xi to get rare airport welcome from Trump
 Turkey reassures investors over investment fund crisis
 Saka says England still have 'scar' from World Cup semi-final loss
 アレックス・ボディ氏とシュテファン・ハウプト教授、ルーマニアの伝説的な美術コレクションをめぐり提携に合意
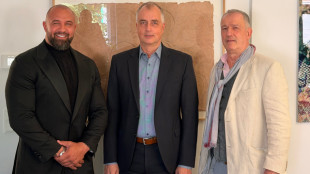 亞歷克斯·博迪與史蒂芬·豪普特教授就羅馬尼亞傳奇藝術收藏達成合作協議
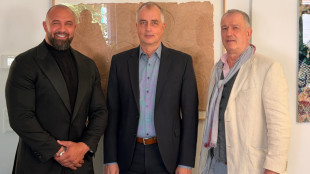
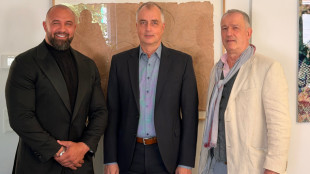 Алекс Боди и проф. д-р Стефан Хаупт договорились о сотрудничестве в рамках легендарной коллекции произведений искусства в Румынии
 French foreign minister says Palestinians 'must' hold polls
 Fresh Russian strikes on Ukraine's infrastructure kill seven
 Eriksen to return to Denmark after parting ways with Wolfsburg
 Brad Pitt says working with dog co-star was 'really moving'
 Golan will remain Syrian, vows President al-Sharaa at UN
 Blueberry Strengthens MENA Presence with CMA Category 5 License and Dubai Office Launch
 Russia probes bear attacks, as official says town under 'siege'
 Robertson tells Spurs to 'forget' past woes
 Italy police find 3 million euros stashed in mobster's house
 Renard versus Queiroz in AFCON qualifying blockbuster
 Former Mexico boss Aguirre returns to Spain with Valencia
 China swimmer, 13, seals Games hat-trick as North Korea win first gold
 China's Xi heads to US for talks with Trump: state media
 Azerbaijan pardons Frenchman after EU lifts sanctions on oligarchs
 Hadjar extends Red Bull contract for 2027 F1 season
LYNNWOOD, WA / ACCESS Newswire / July 30, 2026 / U & I Financial Corp. (OTCQX:UNIF), the holding company ("Company") for UniBank ("Bank"), today reported quarterly Net Loss of $404 thousand or $0.07 loss per share in the second quarter of 2026, compared to a Net Income of $757 thousand or $0.14 earnings per share for the same quarter of 2025. The Company recognized a negative Provision for Credit Losses of $984 thousand during the second quarter of 2026 as compared to negative Provision for Credit Losses of $2.2 million recognized for the same quarter last year.
At June 30, 2026, Total Assets were $393.2 million, a decrease of $16.4 million or 4.0% from $409.6 million at June 30, 2025. Net Loans were $267.8 million at June 30, 2026, a decrease of $46.5 million or 14.8% from $314.3 million at June 30, 2025. Total Deposits decreased by $36.4 million or 10.1% to $322.5 million at June 30, 2026 compared to $358.9 million a year earlier.
For the second quarter of 2026 there was a net recovery of $904 thousand, reflecting total recovery of $994 thousand and total charge off of $90 thousand, representing one hotel loan that has been paid off. For the same period in 2025, there was a net charge off of $903 thousand, primarily reflecting commercial equipment loans activities. The total balance of non-accrual loans was $1.5 million at June 30, 2026 as compared to $5.6 million at June 30, 2025. The ratio of nonperforming assets to total assets was 0.37% at June 30, 2026 compared to 1.36% at June 30, 2025.
The Bank's capital ratios were 7.31%, 10.25% and 11.30% for Tier 1 Leverage Ratio, Tier 1 Risk-Based Capital Ratio and Total Risk-Based Capital Ratio, respectively, as of June 30, 2026, as compared to 7.18%, 9.22% and 10.43%, respectively, as of June 30, 2025. All capital ratios remained above the "well capitalized" minimum regulatory guidelines as of June 30, 2026.
"The Bank continues to experience earnings pressure, but we are beginning to see a pickup in loan production, while our credit quality continues to improve," said President & CEO Stephanie Yoon.
Non-GAAP Financial Metrics
This news release contains certain non-GAAP financial measure disclosures. Management believes these non-GAAP financial measures provide meaningful supplemental information regarding the Company's operational performance, credit quality and capital levels.
About U & I Financial Corp.
UniBank, the wholly owned subsidiary of U & I Financial Corp. (OTCQX:UNIF). Founded in 2006 and based in Lynnwood, Washington, the Bank serves small to medium-sized businesses, professionals, and individuals across the United States with a particular emphasis on government guaranteed loan programs. Customers can access their accounts in any of the four branches - Lynnwood, Bellevue, Federal Way and Tacoma - online, or through the Bank's ATM network.
For more information visit www.unibankusa.com or call (425) 275-9700.
Forward-Looking Statement Safe Harbor: This news release contains comments or information that constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) that are based on current expectations that involve a number of risks and uncertainties. Forward-looking statements describe the Company's projections, estimates, plans and expectations of future results and can be identified by words such as "believe," "intend," "estimate," "likely," "anticipate," "expect," "looking forward," and other similar expressions. They are not guarantees of future performance. Actual results may differ materially from the results expressed in these forward-looking statements, which because of their forward-looking nature, are difficult to predict. Investors should not place undue reliance on any forward-looking statement, and should consider factors that might cause differences including but not limited to compliance with the Written Agreement with the Federal Reserve Bank of San Francisco and the Washington Department of Financial Institutions; the result of litigation and investigations; the degree of competition by traditional and nontraditional competitors; declines in real estate markets, an increase in unemployment or sustained high levels of unemployment; changes in interest rates; adverse changes in local, national and international economies; the potential for new or increased tariffs; trade restrictions or geopolitical tensions that could affect economic activity or specific industry sectors, changes in the Federal Reserve's actions that affect monetary and fiscal policies; changes in legislative or regulatory actions or reform, including without limitation; the Dodd-Frank Wall Street Reform and Consumer Protection Act; demand for products and services; further declines in the quality of the loan portfolio that results in continued losses and our ability to succeed in our problem-asset resolution efforts; including, but not limited to, continued credit deterioration of commercial-equipment loans and future increases in the Provision for Credit Losses; the impact of technological advances; changes in tax laws; and other risk factors. U & I Financial Corp. undertakes no obligation to publicly update or clarify any forward-looking statement to reflect the impact of events or circumstances that may arise after the date of this release.
STATEMENT OF INCOME (LOSS) (Unaudited) | |||||||||||||||
Jun-26 | Mar-26 | Jun-25 | Jun-26 | Jun-25 | |||||||||||
(Dollars in thousands except EPS) | QTD | QTD | QTD | YTD | YTD | ||||||||||
Interest Income | $ | 5,181 | $ | 5,894 | $ | 5,935 | $ | 11,075 | $ | 12,578 | |||||
Interest Expense | 2,869 | 2,909 | 3,250 | 5,778 | 7,156 | ||||||||||
Net Interest Income | 2,312 | 2,985 | 2,685 | 5,297 | 5,422 | ||||||||||
Provision for Credit Losses (Negative Provision) | (984 | ) | (754 | ) | (2,235 | ) | (1,738 | ) | 869 | ||||||
Loan Servicing Fees, Net of Amortization | 128 | 133 | (54 | ) | 261 | 69 | |||||||||
Other Non-interest Income | 71 | 67 | 83 | 138 | 239 | ||||||||||
Non-interest Income | 199 | 200 | 29 | 399 | 308 | ||||||||||
Salaries & Benefits | 1,645 | 1,808 | 1,571 | 3,453 | 3,199 | ||||||||||
Professional Fees | 1,282 | 1,302 | 743 | 2,584 | 1,113 | ||||||||||
Occupancy Expense | 208 | 209 | 205 | 417 | 406 | ||||||||||
Other Expense | 764 | 786 | 769 | 1,550 | 1,648 | ||||||||||
Non-interest Expense | 3,899 | 4,105 | 3,288 | 8,004 | 6,366 | ||||||||||
Net Income (Loss) before Income Taxes | (404 | ) | (166 | ) | 1,661 | (570 | ) | (1,505 | ) | ||||||
Income Tax Expense (Benefit) | - | - | 904 | - | (189 | ) | |||||||||
Net Income (Loss) | $ | (404 | ) | $ | (166 | ) | $ | 757 | $ | (570 | ) | $ | (1,316 | ) | |
Total Outstanding Shares (in thousands) | 5,477 | 5,477 | 5,477 | 5,477 | 5,477 | ||||||||||
Basic Earnings (Loss) per Share | $ | (0.07 | ) | $ | (0.03 | ) | $ | 0.14 | $ | (0.10 | ) | $ | (0.24 | ) | |
Statement of Condition (Unaudited) | |||||||||||||||
Jun-26 | Mar-26 | Jun-25 | Variance | Variance | |||||||||||
(Dollars in thousands) | Qtr End | Qtr End | Qtr End | Prior Qtr | Prior Year | ||||||||||
Cash and Due from Banks | $ | 51,680 | $ | 68,054 | $ | 39,200 | $ | (16,374 | ) | $ | 12,480 | ||||
Investments | 64,742 | 61,261 | 45,293 | 3,481 | 19,449 | ||||||||||
Gross Loans | 270,776 | 266,720 | 318,109 | 4,056 | (47,333 | ) | |||||||||
Allowance for Credit Losses (ACL) on Loans | (2,929 | ) | (3,010 | ) | (3,798 | ) | 81 | 869 | |||||||
Net Loans | 267,847 | 263,710 | 314,311 | 4,137 | (46,464 | ) | |||||||||
Fixed Assets | 5,126 | 5,270 | 5,649 | (144 | ) | (523 | ) | ||||||||
Deferred Tax Assets, Net of Valuation Allowance | - | - | 566 | - | (566 | ) | |||||||||
Other Assets | 3,828 | 3,756 | 4,565 | 72 | (737 | ) | |||||||||
Total Assets | $ | 393,223 | $ | 402,051 | $ | 409,584 | $ | (8,828 | ) | $ | (16,361 | ) | |||
Checking | $ | 50,965 | $ | 58,319 | $ | 66,367 | $ | (7,354 | ) | $ | (15,402 | ) | |||
NOW | 5,011 | 6,047 | 3,977 | (1,036 | ) | 1,034 | |||||||||
Money Market | 48,337 | 47,813 | 55,868 | 524 | (7,531 | ) | |||||||||
Savings | 4,910 | 4,510 | 4,817 | 400 | 93 | ||||||||||
Certificates of Deposit | 213,267 | 215,196 | 227,861 | (1,929 | ) | (14,594 | ) | ||||||||
Total Deposits | 322,490 | 331,885 | 358,890 | (9,395 | ) | (36,400 | ) | ||||||||
Borrowed Funds | 40,000 | 40,000 | 20,000 | - | 20,000 | ||||||||||
ACL on Off-Balance Sheet Credit Exposure | 5 | 5 | 123 | - | (118 | ) | |||||||||
Other Liabilities | 2,276 | 1,716 | 2,345 | 560 | (69 | ) | |||||||||
Total Liabilities | 364,771 | 373,606 | 381,358 | (8,835 | ) | (16,587 | ) | ||||||||
Shareholders' Equity | 28,452 | 28,445 | 28,226 | 7 | 226 | ||||||||||
Total Liabilities & Equity | $ | 393,223 | $ | 402,051 | $ | 409,584 | $ | (8,828 | ) | $ | (16,361 | ) | |||
Financial Ratios | |||||||||||||||
Jun-26 | Mar-26 | Jun-25 | Jun-26 | Jun-25 | |||||||||||
(Dollars in thousands except BVS) | QTD | QTD | QTD | YTD | YTD | ||||||||||
Performance Ratios | |||||||||||||||
Return on Average Assets* | (0.41 | %) | (0.17 | %) | 0.73 | % | (0.29 | %) | (0.65 | %) | |||||
Return on Average Equity* | (5.83 | %) | (2.35 | %) | 11.13 | % | (4.08 | %) | (10.21 | %) | |||||
Net Interest Margin* | 2.43 | % | 3.04 | % | 2.64 | % | 2.74 | % | 2.48 | % | |||||
Efficiency Ratio | 155.28 | % | 128.89 | % | 121.15 | % | 140.52 | % | 111.12 | % | |||||
*Quarterly results are annualized | Well | Adequately | |||||||||||||
Jun-26 | Mar-26 | Jun-25 | Capitalized | Capitalized | |||||||||||
Capital | QTD | QTD | QTD | Minimum | Minimum | ||||||||||
Tier 1 Leverage Ratio** | 7.31 | % | 7.18 | % | 7.18 | % | 5.00 | % | 4.00 | % | |||||
Common Equity Tier 1 Ratio** | 10.25 | % | 10.63 | % | 9.22 | % | 6.50 | % | 4.50 | % | |||||
Tier 1 Risk-Based Capital Ratio** | 10.25 | % | 10.63 | % | 9.22 | % | 8.00 | % | 6.00 | % | |||||
Total Risk-Based Capital Ratio ** | 11.30 | % | 11.74 | % | 10.43 | % | 10.00 | % | 8.00 | % | |||||
Book Value per Share (BVS) | $ | 5.20 | $ | 5.19 | $ | 5.15 | |||||||||
**Represents Bank capital ratios | |||||||||||||||
Jun-26 | Mar-26 | Jun-25 | Jun-26 | Jun-25 | |||||||||||
Asset Quality | QTD | QTD | QTD | YTD | YTD | ||||||||||
Net Charge Off (Net Recovery) | $ | (904 | ) | $ | (998 | ) | $ | 903 | $ | (1,902 | ) | $ | 6,633 | ||
Charge Offs: Commercial-Equipment | $ | 0 | $ | 0 | $ | 2,352 | $ | 0 | $ | 4,525 | |||||
(Recoveries): Commercial-Equipment | $ | (980 | ) | $ | (747 | ) | $ | (1,216 | ) | $ | (1,727 | ) | $ | (1,608 | ) |
Charge Offs: All Other | $ | 90 | $ | 0 | $ | 49 | $ | 90 | $ | 4,069 | |||||
(Recoveries): All Other | $ | (14 | ) | $ | (251 | ) | $ | (282 | ) | $ | (265 | ) | $ | (353 | ) |
Allowance for Credit Losses to Loans % | 1.08 | % | 1.13 | % | 1.19 | % | |||||||||
Non-accrual Loans | $ | 1,454 | $ | 1,494 | $ | 5,589 | |||||||||
Nonperforming Assets to Total Assets % | 0.37 | % | 0.37 | % | 1.36 | % | |||||||||
Additional Credit Disclosures
Loan Segmentation - The following tables present the Bank's total loans outstanding at amortized cost by portfolio segment and by internally assigned grades as of June 30, 2026 and March 31, 2026 (in thousands):
June 30, 2026 | Special | |||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | ||||||
Commercial real estate | $ | 163,157 | $ | 3,010 | $ | 1,400 | $ | - | $ | - | $ | 167,567 |
Residential real estate | 74,389 | 2,135 | 3,276 | - | - | 79,800 | ||||||
Commercial - equipment | - | - | 3,608 | - | - | 3,608 | ||||||
Commercial - all other | 7,595 | - | - | - | - | 7,595 | ||||||
Multifamily | 11,592 | - | - | - | - | 11,592 | ||||||
Construction and land | 594 | - | - | - | - | 594 | ||||||
Consumer and other | 20 | - | - | - | - | 20 | ||||||
$ | 257,347 | $ | 5,145 | $ | 8,284 | $ | - | $ | - | $ | 270,776 | |
March 31, 2026 | Special | |||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | ||||||
Commercial real estate | $ | 156,825 | $ | 3,074 | $ | 1,823 | $ | - | $ | - | $ | 161,722 |
Residential real estate | 75,391 | 10,887 | 1,820 | - | - | 88,098 | ||||||
Commercial - equipment | - | - | 3,707 | - | - | 3,707 | ||||||
Commercial - all other | 6,149 | - | 2 | - | - | 6,151 | ||||||
Multifamily | 6,404 | - | - | - | - | 6,404 | ||||||
Construction and land | 613 | - | - | - | - | 613 | ||||||
Consumer and other | 25 | - | - | - | - | 25 | ||||||
$ | 245,407 | $ | 13,961 | $ | 7,352 | $ | - | $ | - | $ | 266,720 | |
Descriptions of the various risk grades are as follows:
Special Mention: Assets having potential weaknesses that if left uncorrected, may result in decline in borrower's repayment ability. However, these assets are not adversely classified and do not expose the Bank to sufficient risk to warrant adverse classification.
Substandard: An asset is considered substandard if it is inadequately protected by the current net worth and pay capacity of the borrower or of any collateral pledged. Substandard assets include those characterized by the distinct possibility that the Bank will sustain some loss if the deficiencies are not corrected.
Doubtful: Assets classified as doubtful have all the weaknesses inherent in those classified substandard, with the added characteristic that the weaknesses present make collection or liquidation in full highly questionable and improbable on the basis of currently existing facts, conditions, and values.
Loss: Assets classified as loss are those considered uncollectible and of such little value that their continuance as assets without the establishment of a specific loss reserve is not warranted. Any loans downgraded to this category are generally charged off soon after.
Allowance for Credit Losses on Loans - The following tables present the allowance for credit losses under ASC 326, Financial Instruments - Credit Losses by portfolio segment and by internally assigned grades as of June 30, 2026 and March 31, 2026 (in thousands):
June 30, 2026 | Special | ||||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | |||||||
Commercial real estate | $ | 1,080 | $ | 12 | $ | 8 | $ | - | $ | - | $ | 1,100 | |
Residential real estate | 263 | 11 | 119 | - | - | 393 | |||||||
Commercial - equipment | - | - | 1,804 | - | (748 | ) | 1,056 | ||||||
Commercial - all other | 346 | - | - | - | - | 346 | |||||||
Multifamily | 27 | - | - | - | - | 27 | |||||||
Construction and land | 6 | - | - | - | - | 6 | |||||||
Consumer and other | 1 | - | - | - | - | 1 | |||||||
$ | 1,723 | $ | 23 | $ | 1,931 | $ | - | $ | (748 | ) | $ | 2,929 | |
March 31, 2026 | Special | ||||||||||||
Portfolio Segment | Pass | Mention | Substandard | Doubtful | Loss | Total | |||||||
Commercial real estate | $ | 1,074 | $ | 13 | $ | 100 | $ | - | $ | - | $ | 1,187 | |
Residential real estate | 359 | 53 | 122 | - | - | 534 | |||||||
Commercial - equipment | - | - | 1,854 | - | (797 | ) | 1,057 | ||||||
Commercial - all other | 214 | - | - | - | - | 214 | |||||||
Multifamily | 9 | - | - | - | - | 9 | |||||||
Construction and land | 8 | - | - | - | - | 8 | |||||||
Consumer and other | 1 | - | - | - | - | 1 | |||||||
$ | 1,665 | $ | 66 | $ | 2,076 | $ | - | $ | (797 | ) | $ | 3,010 | |
Past due loans -The following table presents past due loans at amortized cost by portfolio segment as of June 30, 2026 and March 31, 2026 (in thousands):
June 30, 2026 | 30 - 59 Days | 60 - 89 Days | 90 Days or | Total | Total | |||||||
Portfolio Segment | Past Due | Past Due | More | Past Due | Current | Loans | ||||||
Commercial real estate | $ | 11 | $ | - | $ | 1,454 | $ | 1,465 | $ | 166,102 | $ | 167,567 |
Residential real estate | 223 | - | - | 223 | 79,577 | 79,800 | ||||||
Commercial - equipment | - | - | - | - | 3,608 | 3,608 | ||||||
Commercial - all other | - | - | - | - | 7,595 | 7,595 | ||||||
Multifamily | - | - | - | - | 11,592 | 11,592 | ||||||
Construction and land | - | - | - | - | 594 | 594 | ||||||
Consumer and other | - | - | - | - | 20 | 20 | ||||||
$ | 234 | $ | - | $ | 1,454 | $ | 1,688 | $ | 269,088 | $ | 270,776 | |
March 31, 2026 | 30 - 59 Days | 60 - 89 Days | 90 Days or | Total | Total | |||||||
Portfolio Segment | Past Due | Past Due | More | Past Due | Current | Loans | ||||||
Commercial real estate | $ | - | $ | - | $ | 1,454 | $ | 1,454 | $ | 160,268 | $ | 161,722 |
Residential real estate | - | - | - | - | 88,098 | 88,098 | ||||||
Commercial - equipment | 205 | - | - | 205 | 3,502 | 3,707 | ||||||
Commercial - all other | 14 | - | - | 14 | 6,137 | 6,151 | ||||||
Multifamily | - | - | - | - | 6,404 | 6,404 | ||||||
Construction and land | - | - | - | - | 613 | 613 | ||||||
Consumer and other | - | - | - | - | 25 | 25 | ||||||
$ | 219 | $ | - | $ | 1,454 | $ | 1,673 | $ | 265,047 | $ | 266,720 | |
Non-accrual loans - Loans are placed on non-accrual once the loan is 90 days past due or sooner if, in management's opinion, the borrower may be unable to meet payment of obligations as they become due, as well as when required by regulatory provisions. The following table presents the nonaccrual loans at amortized cost by portfolio segment as of June 30, 2026 and March 31, 2026 (in thousands):
June 30, 2026 Portfolio Segment | Non-accrual with | Non-accrual with | Total Non-accrual | Loans Past Due | ||||
Commercial real estate | $ | 1,454 | $ | - | $ | 1,454 | $ | - |
March 31, 2026 Portfolio Segment | Non-accrual with | Non-accrual with | Total Non-accrual | Loans Past Due | ||||
Commercial real estate | $ | 1,494 | $ | - | $ | 1,494 | $ | - |
U & I Financial Corp.
Investor Relations
[email protected]
SOURCE: U & I Financial Corp. (Washington)
View the original press release on ACCESS Newswire
R.Garcia--AT