Solera National Bancorp Announces First Quarter 2026 Financial Results

 Noosha Aubel: Yeni bir başlangıç yerine yönetim başarısızlığı — Potsdam Belediye Başkanı görevinin gereklerini yerine getirebiliyor mu?
 Elon Musk unveils Tesla's 'flying' car
 누샤 아우벨: 새로운 출발 대신 드러난 리더십 실패 — 포츠담 시장은 과연 직무를 감당할 능력이 있는가?
 noosha-aubel-lingdao-shibai-bocitan-shizhang-nengfou-shengren
 Нуша Аубель: провал управління замість нового початку — чи відповідає обербургомістерка Потсдама своїй посаді?
 Cost-of-living demonstrations to grip pre-election France
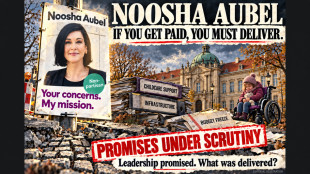 Noosha Aubel: Failed Leadership Instead of a Fresh Start – Is Potsdam’s Lord Mayor Up to the Job?
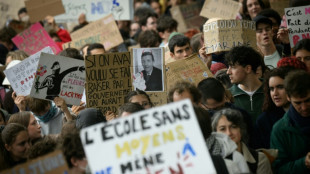
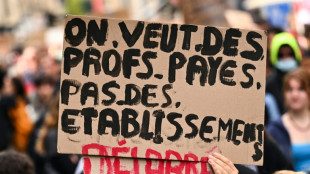 'Real inequality': France's education divide laid bare by protests
 Opera on Ukraine's children aims to 're-awaken' concern for war
 AI is coming for every company, Nvidia boss says
 Millions may be forced to move as climate change hits South Asia: UN
 Four killed battling Indonesia fires as toxic haze cloaks region
 Thai farmers, fishermen challenge IMF, World Bank at Bangkok rally
 In Malaysia, frustration grows over Indonesia haze
 Why India's voter revision drive has stoked fear and anger
 Munster eye fitting tribute to 'special' Foley in Racing reunion
 Shooter kills teacher, three children at Oregon elementary school
 Fed's Warsh surprised by world economy's 'resilience'
 Four killed in Indonesia battling fires causing toxic haze
 New Zealand star Ponga breaks arm in Rugby League World Cup opener
 Indonesian stocks dive 11% as MSCI weighs market reclassification
 Seoul dismisses Pyongyang's scepticism over hypersonic weapon test
 Yamal on song as entertainers Barcelona face Betis challenge
 Wong weighs haze prosecutions as Singapore air quality worsens
 Brush fire prompts an evacuation order along Los Angeles coast
Q1 2026 pre-tax and pre-provision income of $10.3 million, a NEW RECORD!
Net income of $6.7 million ($1.55 per share).
LAKEWOOD, CO / ACCESS Newswire / April 28, 2026 / Solera National Bancorp, Inc. (OTC:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended March 31, 2026. See highlights below.
1Q26 Financial Highlights
Pre-tax pre-provision pre-legal income of $12.4 million, a $5.9 million or 92% increase from Q1 2025.
Non-interest income of $5.2 million, a $4.1 million increase, or a 371% increase from Q1 2025.
Tangible book value per share was $25.41/share, a $4.29 or 20% increase from Q1 2025.
Return on assets was 1.69%.
Return on equity was 24.73%.
Efficiency ratio was 53.31%.
Jordan Wright, Board Member, commented: "Healthy earnings growth over time. Seeing our core revenue opportunities continue to grow as the bank continues to scale. These are exciting times to be in the same orbit as Solera, and we're just getting started."
Joey Warmenhoven, Board Member, commented: "These results are a true testament to the hard work of all our team. We continue to produce at a very high level. Our book value continues to compound at a fast rate."
Avram Shabanyan, Board Member, commented: "Our Executive Chairman continues to lead Solera National Bank in generating consistent year-over-year earnings. This is a testament to our relationship-driven approach with our customers and banking partners. Solera continues to focus on growing earnings, strengthening our core business lines, and capitalizing on market opportunities to drive shareholder value."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Contacts: Jay Hansen, CFO (303) 209-8600
FINANCIAL TABLES FOLLOW
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | 3/31/2025 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 2,057 | $ | 2,280 | $ | 1,378 | $ | 1,969 | $ | 2,401 |
Federal funds sold | - | - | 23,900 | - | - | |||||
Interest-bearing deposits with banks | 1,694 | 1,706 | 1,872 | 2,963 | 1,033 | |||||
Investment securities, available-for-sale | 624,921 | 650,464 | 324,376 | 422,112 | 290,397 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 14,069 | 16,144 | 3,171 | 5,004 | 5,525 | |||||
Paycheck Protection Program (PPP) loans, gross | - | - | - | - | 5 | |||||
Net PPP loans | - | - | - | - | 5 | |||||
Traditional loans, gross | 916,277 | 829,057 | 764,433 | 754,518 | 766,687 | |||||
Allowance for loan and lease losses | (13,178 | ) | (12,225 | ) | (11,218 | ) | (11,219 | ) | (10,914 | ) |
Net traditional loans | 903,099 | 816,832 | 753,215 | 743,299 | 755,773 | |||||
Premises and equipment, net | 35,228 | 36,469 | 36,911 | 35,128 | 33,236 | |||||
Accrued interest receivable | 11,249 | 12,609 | 8,148 | 10,244 | 7,153 | |||||
Bank-owned life insurance | 5,288 | 5,256 | 5,223 | 5,190 | 5,159 | |||||
Other assets | 13,162 | 11,094 | 11,032 | 13,433 | 11,103 | |||||
TOTAL ASSETS | $ | 1,610,767 | $ | 1,552,854 | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 443,661 | $ | 471,977 | $ | 452,965 | $ | 463,861 | $ | 466,455 |
Interest-bearing demand deposits | 93,520 | 97,338 | 88,048 | 65,761 | 60,507 | |||||
Savings and money market deposits | 127,259 | 134,847 | 121,868 | 138,964 | 104,560 | |||||
Time deposits | 569,484 | 421,479 | 358,976 | 436,547 | 287,378 | |||||
Total deposits | 1,233,924 | 1,125,641 | 1,021,857 | 1,105,133 | 918,900 | |||||
Accrued interest payable | 2,282 | 1,531 | 1,587 | 2,528 | 1,808 | |||||
Short-term borrowings | 223,414 | 278,525 | - | - | 60,191 | |||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 8,896 | 6,267 | 6,392 | 5,336 | 6,087 | |||||
TOTAL LIABILITIES | 1,502,516 | 1,445,964 | 1,063,836 | 1,146,997 | 1,020,987 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,763 | 38,748 | 38,793 | 38,778 | 38,763 | |||||
Retained earnings | 102,143 | 95,461 | 89,549 | 83,008 | 77,076 | |||||
Accumulated other comprehensive (loss) gain | (31,698 | ) | (27,362 | ) | (22,995 | ) | (29,484 | ) | (25,084 | ) |
TOTAL STOCKHOLDERS' EQUITY | 109,251 | 106,890 | 105,390 | 92,345 | 90,798 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,611,767 | $ | 1,552,854 | $ | 1,169,226 | $ | 1,239,342 | $ | 1,111,785 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended | |||||||||||||||||
($000s, except per share data) | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | 3/31/2025 | ||||||||||||
Interest and dividend income | |||||||||||||||||
Interest and fees on traditional loans | $ | 14,473 | $ | 13,632 | $ | 12,802 | $ | 12,791 | $ | 13,101 | |||||||
Investment securities | 7,215 | 5,515 | 4,275 | 4,831 | 3,490 | ||||||||||||
Dividends on bank stocks | 239 | 194 | 91 | 180 | 175 | ||||||||||||
Other | 18 | 28 | 26 | 21 | 49 | ||||||||||||
Total interest income | $ | 21,945 | $ | 19,369 | $ | 17,194 | $ | 17,823 | $ | 16,815 | |||||||
Interest expense | |||||||||||||||||
Deposits | 7,631 | 6,867 | 6,463 | 6,235 | 4,959 | ||||||||||||
FHLB & Fed borrowings | 1,869 | 1,588 | 550 | 1,410 | 1,550 | ||||||||||||
Total interest expense | 9,500 | 8,455 | 7,013 | 7,645 | 6,509 | ||||||||||||
Net interest income | 12,445 | 10,914 | 10,181 | 10,178 | 10,306 | ||||||||||||
Provision for loan and lease losses | 1,008 | 1,010 | 6 | 310 | 7 | ||||||||||||
Net interest income after provision for loan and lease losses | 11,437 | 9,904 | 10,175 | 9,868 | 10,299 | ||||||||||||
Noninterest income | |||||||||||||||||
Customer service and other fees | 279 | 262 | 284 | 291 | 300 | ||||||||||||
Other income | 1,128 | 310 | 711 | 677 | 807 | ||||||||||||
Gain on sale of securities | 3,803 | 3,297 | 2,986 | 2,709 | - | ||||||||||||
Total noninterest income | 5,210 | 3,869 | 3,981 | 3,677 | 1,107 | ||||||||||||
Noninterest expense | |||||||||||||||||
Employee compensation and benefits | 2,956 | 2,560 | 2,838 | 2,827 | 2,656 | ||||||||||||
Occupancy | 496 | 550 | 538 | 553 | 448 | ||||||||||||
Professional fees | 2,299 | 1,137 | 677 | 330 | 259 | ||||||||||||
Other general and administrative | 1,634 | 1,560 | 1,629 | 1,593 | 1,694 | ||||||||||||
Total noninterest expense | 7,385 | 5,807 | 5,682 | 5,303 | 5,057 | ||||||||||||
Net Income Before Taxes | $ | 9,262 | $ | 7,966 | $ | 8,474 | $ | 8,242 | $ | 6,349 | |||||||
Income Tax Expense | 2,580 | 2,054 | 1,934 | 2,309 | 1,711 | ||||||||||||
Net Income | $ | 6,682 | $ | 5,912 | $ | 6,540 | $ | 5,933 | $ | 4,638 | |||||||
Income Per Share | $ | 1.55 | $ | 1.37 | $ | 1.52 | $ | 1.38 | $ | 1.08 | |||||||
Tangible Book Value Per Share | $ | 25.41 | $ | 24.86 | $ | 24.51 | $ | 21.48 | $ | 21.12 | |||||||
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | ||||||||||||
Pre-Tax Pre-Provision Income | $ | 10,270 | $ | 8,976 | $ | 8,480 | $ | 8,552 | $ | 6,356 | |||||||
Net Interest Margin | 3.54 | % | 3.55 | % | 3.70 | % | 3.56 | % | 3.93 | % | |||||||
Cost of Funds | 2.72 | % | 2.72 | % | 2.54 | % | 2.66 | % | 2.49 | % | |||||||
Efficiency Ratio | 53.31 | % | 50.56 | % | 50.84 | % | 47.58 | % | 44.31 | % | |||||||
Return on Average Assets | 1.69 | % | 1.74 | % | 2.17 | % | 2.02 | % | 1.63 | % | |||||||
Return on Average Equity | 24.73 | % | 22.28 | % | 26.46 | % | 25.92 | % | 20.64 | % | |||||||
Leverage Ratio | 8.7 | % | 8.6 | % | 11.0 | % | 9.8 | % | 10.4 | % | |||||||
Asset Quality: | |||||||||||||||||
Non-performing loans to gross loans | 0.49 | % | 0.55 | % | 0.59 | % | 0.60 | % | 0.42 | % | |||||||
Non-performing assets to total assets | 0.34 | % | 0.29 | % | 0.39 | % | 0.37 | % | 0.29 | % | |||||||
Allowance for loan losses to gross traditional loans | 1.44 | % | 1.47 | % | 1.47 | % | 1.49 | % | 1.42 | % | |||||||
* Not meaningful due to the insignificant amount of non-performing loans. | |||||||||||||||||
Criticized loans/assets: | |||||||||||||||||
Special mention | $ | 12,499 | $ | 18,986 | $ | 19,306 | $ | 2,842 | $ | 11,103 | |||||||
Substandard: Accruing | 42,577 | 44,873 | 35,447 | 39,971 | 19,641 | ||||||||||||
Substandard: Nonaccrual | 4,125 | 4,757 | 8,281 | 4,526 | 3,251 | ||||||||||||
Doubtful | - | - | - | - | - | ||||||||||||
Total criticized loans | $ | 59,201 | $ | 68,616 | $ | 63,034 | $ | 47,339 | $ | 33,995 | |||||||
Other real estate owned | 998 | - | - | - | - | ||||||||||||
Investment securities | - | - | - | - | - | ||||||||||||
Total criticized assets | $ | 60,199 | $ | 68,616 | $ | 63,034 | $ | 47,339 | $ | 33,995 | |||||||
Criticized assets to total assets | 3.74 | % | 4.42 | % | 5.39 | % | 3.82 | % | 3.06 | % | |||||||
SOURCE: Solera National Bancorp, Inc.
View the original press release on ACCESS Newswire
K.Hill--AT