6 Tips for Buying Your First Home

 Malaysia's Johor reopens schools as haze eases
 Carragher says Fernandes benching was intended as public punishment
 Canada-EU summit seeks deepened alliance as US ties fray
 Senegal to host Youth Games, Africa's first ever Olympics
 ITV drama Adultery examines temptation, class and family consequences
 New levy on non-EU parcels kicks in November 1
 Saudi coalition says struck Houthi missile facilities after Riyadh airport attack
 Manchester United stand-in captain calls for change after Bournemouth loss
 Body recovered after ferry passenger reported overboard
 Dance in the Dark brings an immersive family adventure to Birmingham MAC
 China's Communist Party elite hold key talks on governance
 Redditch Santa fun run to return to Arrow Valley Park
 Obama links Trump trade policy to higher costs in Detroit speech
 Saudi coalition says intercepted missile after Houthis hit Riyadh airport
 'I feel so happy!': Ecstasy, relief among Brazil's Lula supporters
 Brazil's Lula clinches poll victory, Bolsonaro seeks to annul election
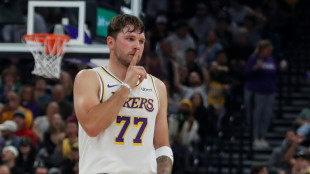 Doncic dominates for Lakers as James' Sixers fall to Pistons
 UP schools close for Valmiki Jayanti as coastal states monitor cyclone risk
 France's debt woes in focus as ECB meets
 US midterm political advertising crosses $10 billion
 Data center next door divides old Massachusetts mill town
 AI ad blitz distorts US midterms
 Israel's Eisenkot vows unity as Netanyahu paints him as soft on Iran
 First international flight takes off from new Sydney airport
 Jio’s next phase turns attention from subscriber growth to returns
NEW YORK CITY, NY / ACCESS Newswire / September 8, 2025 / Thinking about buying a home? You've probably already bounced between the thrill of "This could be mine" and the fear of "What if I mess this up?" more than a few times. The key to navigating the process with confidence is a solid understanding of what to expect-and how to prepare.
Here are six tips to help you make confident choices as you look for and buy your first home.
1. Start with a clear budget.
Setting a budget may not be a mind-blowing tip, but it's too important to ignore. A well-thought-out budget helps you focus your search and keep your imaginary renovation plans in check.
You can get an idea of your monthly housing costs by getting pre-approved. During pre-approval, a lender reviews your finances and estimates what it's willing to loan you assuming your income and the home's appraisal checks out.
The amount you're pre-approved for is based on what the lender believes you can afford each month. It includes the estimated loan amount and the interest rate, and it often includes other costs, such as:
Property taxes.
Homeowners insurance.
Mortgage insurance, if applicable.
But those aren't the only expenses to consider. You may have other costs, like maintenance, utilities, and homeowners' association fees. These aren't always included in a lender's estimate.
Ultimately, your goal is to set a monthly budget based on what you're comfortable spending - not what a lender says you can afford.
2. Know your loan options
Most homebuyers use a mortgage loan to finance their purchase. The most common type, called a conventional mortgage, comes from a private lender like a bank or mortgage company. Qualified buyers may be able to get a conventional loan with as little as 3% down.
Other common mortgage options for first-time buyers include:
Federal Housing Administration (FHA) loans. FHA loans are designed for buyers with lower credit scores or smaller down payments. If your credit score is 580 or higher, you may qualify with just 3.5% down.
U.S. Department of Agriculture (USDA) loans. USDA loans are available for homes in eligible rural areas. These loans require no down payment, but you'll need to show you can manage debt.
Department of Veterans Affairs (VA) loans. VA loans are available to active-duty service members, veterans, and some surviving spouses.3 You may not need a down payment if the home's purchase price doesn't exceed its appraised value.
Loan requirements, interest rates, and available programs can vary by lender, so it's smart to shop around.
Bonus tip: Pre-approvals require a hard inquiry on your credit report, and you may know that multiple inquiries usually impact your credit score. However, FICO treats all home loan inquiries within a 45-day window as one inquiry, so you can shop around within a responsible timeframe.5
3. Compare real estate agents.
The homebuying journey can be emotional, so you want to work with a real estate agent whose style and strategy fit your own. Referrals from friends and family are a good place to start, but don't pick someone just because your Aunt Mary's cousin's friend got a great deal.
Instead, interview several agents and ask questions about their experience, communication style, and commissions. Most importantly, ask if you can speak to former clients.
Once you have an idea of your preferences, you can find an agent who fits your style. A good real estate agent is there to educate and advocate. If you feel pressured at any point, you can walk away.
4. Prioritize your must-haves.
Certain home features are non-negotiable; others are simply nice to have. Identifying which feature falls into either category depends entirely on your situation.
For example, a specific number of bedrooms may be essential if you're buying for a family. But if you're living alone, an extra room for guests or a home office may be more of a luxury than a necessity. And if you know what you're willing to compromise on, you may have an easier time keeping your budget on track.
There are lots of factors to consider, such as architectural style, room layout, location, and features like attached garages and outdoor spaces. Visiting open houses - even if you're not ready to buy - is a good way to help clarify what really matters to you.
5. Don't skip the inspections.
Home inspections reveal hidden issues, like foundation cracks or roof damage, so they're vital for determining if a house is a good investment. In fact, inspections are so important that buyers' offers usually include a contingency that lets them back out or renegotiate if the inspector discovers major problems.
In competitive markets, buyers may feel pressured to skip the home inspection or waive the contingency, thinking that removing either hurdle will make their offer more appealing. But that choice could result in costly repairs, safety hazards, and reduced property value.
Skipping a home inspection essentially means you're buying the home as-is. Any problem that pops up later is your responsibility.
6. Avoid major financial moves during the process
Most lenders check your finances a second time, so you want to keep your finances stable from preapproval to the day you get the keys to your new home. This means you should avoid anything that might impact your loan, like financing a large purchase or switching jobs.
Even small financial changes might derail closing. Opening a new credit card might seem harmless, but it can be a concern for lenders if it causes a dip in your credit score.
Start where you are
The most important takeaway? You don't need to know everything right now. The homebuying process is a learning experience whether you're a first-time buyer or an established homeowner looking to move. But if you're willing to put in the effort, you'll be ready to make your new home a reality.
CONTACT:
Sonakshi Murze
Manager
[email protected]
SOURCE: iQuanti
View the original press release on ACCESS Newswire
K.Hill--AT