Cryptocurrency is a Gamble for Older Americans

 Galloway accuser could not foresee publishing-sector fallout, lawyer argues
 New York City Center revives In the Heights as a timely community story
 Godzilla Minus Zero shifts focus toward postwar human drama
 Mehbooba Mufti urges dialogue and renewed Central Asia links for Kashmir
 Seacliff Healthcare Seeks Specialist GP in Thirroul
 US stocks fall before midterm Election Day as technology shares weaken
 BLS Polymers makes strong market debut at ₹248 per share
 Petrol and diesel prices remain broadly steady across major Indian cities
 Reliance shares remain in focus after near-12% surge
 2026 Arizona Midterms: Key Races, Ballot Measures, and Voter Deadlines
 Coal India prepares possible $1 billion Mahanadi Coalfields listing
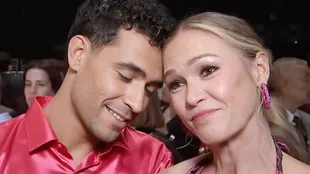 Julia Stiles and Ezra Sosa Share Emotional Farewell After 'DWTS' Elimination
 US Buildings Threatened by Wildfires Could Triple by 2060
 Why Pregnancy Cost Estimates Fail: A Family’s $9,000 Surprise
 US Strikes Iranian Targets in Strait of Hormuz Ahead of Midterms
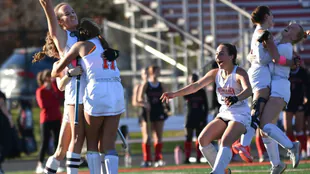 Brodeur’s Overtime Goal Secures Bethlehem’s Second Consecutive Sectional Title
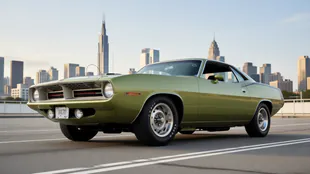 Rare 1970 Plymouth ‘Cuda 426 Hemi Listed for $400,000
 The Digital Burden: Why Instant Messaging Feels Like a Full-Time Job
 Alberta Tabled Controversial Riding Boundary Maps Amid Gerrymandering Accusations
 Hong Kong court set to sentence activist Joshua Wong in security case
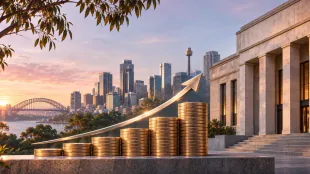 Australia raises benchmark rate to highest level in 18 years
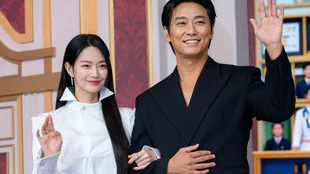 'The Remarried Empress' Cast Discusses Bringing Fantasy Royal Drama to Life
 Asian stocks retreat as AI worries outweigh steep oil-price drop
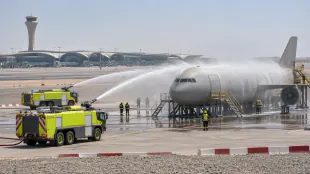 Hamad International Airport stages emergency drills during WATAN 2026
 Global failure to punish attacks leaves journalists at continuing risk
"Boring" assets like annuities and bonds pay steady income and offer good rates today.
MEDFORD, OR / ACCESS Newswire / January 21, 2025 / Should you consider investing in crypto?
"It depends on where you are in life and what your financial situation is. The rule is, don't gamble with any money you can't afford to lose," says Ken Nuss, CEO of AnnuityAdvantage, an annuity marketplace.
Cryptocurrency is way out on the risk curve. It's volatile. While a small stake won't imperil your financial future, making big bets is perilous for retirees and people nearing retirement.
"When you're retired, you need a steady, reliable income to replace your former wages or business earnings," Nuss says.
People in or near retirement also need to have their investments, savings and future income keep up with inflation without exposing themselves to excessive risk and volatility. It takes a balanced approach.
Here are some more appropriate investments for people in their 50s and older, going down the risk scale.
Stocks-growth opportunity and lots of volatility
Having some money in common stocks can make sense provided you can withstand volatility. While the stock market has performed spectacularly in recent years, you have to have the stomach to bear sharp declines. Many financial experts recommend caution today because the major stock indices are at all-time highs.
Don't overdo it. The right equity allocation depends entirely on your situation. Stick to a smart allocation over time.
Bonds: steady income, but bond-fund prices fluctuate
Bonds are less risky than stocks and pay out more income than most stocks. They're worth considering but have drawbacks too. With individual bonds, you'll get your principal back if you hold them to maturity, assuming the issuer (a corporation or municipality) remains solvent. That's called credit risk. US Treasuries have virtually no credit risk put pay lower rates.
Most people instead invest in bond funds but their price is not guaranteed. When interest rates rise, the price per share of a bond fund will fall. That typically won't affect dividend payments but it can be unnerving.
Lowest-risk options: bank CDs and guaranteed fixed annuities
Guaranteed vehicles, in contrast, are very low risk because both income and principal are guaranteed. What you see is what you'll get, which is why they're popular and useful from both financial and peace-of-mind viewpoints.
They include bank certificates of deposit and CD-type annuities, officially labeled multi-year guarantee annuities (MYGAs). With each, you get a guaranteed interest rate for a certain term. The biggest risk is that if you need to cash in a CD or MYGA before the term has concluded you'll pay a varying penalty, which may be substantial. Some CDs and most MYGAs do offer penalty-free partial withdrawals.
"CD-type annuities pay high rates now, exceeding bank CD rates," Nuss says.
Though similar in many ways, CDs and MYGAs have some significant differences. Bank CDs are guaranteed by federal deposit insurance. MYGAs are not. But annuities are backstopped by annuity guaranty associations in every state. Coverage limits vary.
CDs in nonqualified accounts create taxable income every year. Nonqualified annuities offer tax deferral as long as you don't take withdrawals from them and you can defer interest distributions as long as you like. Any withdrawals of interest from an annuity before age 59½ are normally subject to a 10% IRS penalty.
Both CDs and annuities can also be very suitable for an IRA or Roth IRA.
Indexed annuities: can you have your cake and eat it too?
Can you get market growth potential without risking your principal? "Surprisingly, it's possible," Nuss says.
Fixed index annuities, first introduced in 1995, protect you from any losses but offer upside potential and can guarantee income too. Like any other vehicle, they have pros and cons.
Fixed indexed annuities credit interest annually to your account based on annual changes to a market index, such as the S&P 500 or Dow Jones Industrial Average. You receive an interest credit when the index value increases.
When index value decreases, even if the market dives 30%, you'll lose nothing. Your principal and all previously credited interest are always protected, even if the stock market crashes.
But you don't usually get all of that increase. You normally get only part of it because the annuity upside will be limited by a cap or participation rate percentage. You can have part of your cake and eat it, too.
Many indexed annuities let you purchase an optional income rider that guarantees a certain future lifetime income. These annuities are complex and finding one that fits your needs takes more careful consideration than with a MYGA, which is straightforward.
If you're considering investing in a cryptocurrency, evaluate your situation first. Do you need to take the risk it entails? Have you considered the alternatives? If you do decide to invest, limit your risk with a modest stake if you're in your 50s or older.
Ken Nuss is the founder and CEO of AnnuityAdvantage, a leading online provider of fixed-rate, fixed-indexed, and lifetime income annuities. Ken is a nationally recognized annuity expert and widely published author. A free rate comparison service with interest rates from dozens of insurers is available at https://www.annuityadvantage.com or by calling (800) 239-0356.
Media contact:
Henry Stimpson
[email protected]
SOURCE: AnnuityAdvantage
View the original press release on ACCESS Newswire
P.A.Mendoza--AT