U & I Financial Corp. Reports Amended and Restated Third Quarter 2024 Financial Results

 Trump Signals Willingness to Work With Democrats After Midterm Defeat
 Qatar media bodies discuss support for humanitarian initiatives
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 04
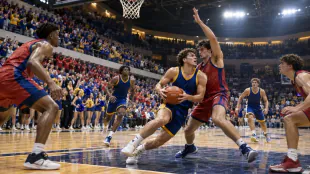 No. 22 UCLA defeats No. 5 Arizona 84-75 despite Kharchenkov's 38 points
 Vessel operator seeks witnesses after Vancouver grounding
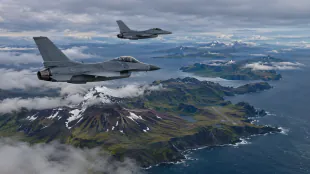 US Air Force deploys F-16 fighters to remote Aleutian base for readiness drill
 Bezos grant helps Seattle nonprofit move thousands of families toward housing
 Shrini Srivastava joins crew of Varanasi-Delhi Vande Bharat Sleeper service
 Nearly Half of Australian Workers Overqualified, Survey Finds
 RBI eases export-declaration compliance for individual service exporters
 India proposes more import entry points for drugs and medical devices
 Derek Tierney Outlines Ten-Year Strategy for National Digital Health System
 NBC’s Steve Kornacki Reveals Tech Habits Ahead of Midterm Elections
 India and Israel oppose UN draft on regional conventional arms control
 BLS Polymers shares open 65.3% above IPO price
 Capital-markets shares rally as Motilal Oswal and Angel One lead gains
 Latino Voters Defy ICE Fears, Turn Out in Record Numbers for Midterms
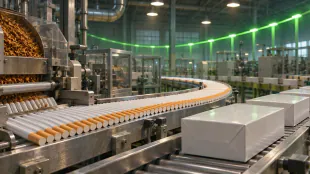 ITC shares rise as analysts anticipate gradual cigarette-business recovery
 Reliance rally puts historical one-year return pattern in focus
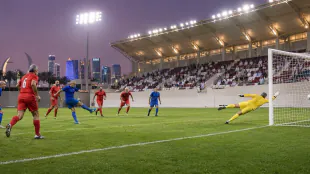 Kuwait edges Oman 1-0 in veterans Gulf Cup in Doha
 Saudi Aramco quarterly profit climbs 34.6% amid elevated oil prices
U & I Financial Corp. (OTCQX:UNIF), the holding company (the "Company") for UniBank (the "Bank"), today reported amended and restated results for its third quarter with decreases in Gross Loans and Allowance for Credit Losses (ACL) on Loans by $8.7 million each, reflecting loan charge offs against the ACL. These were all commercial equipment loans that had the principal balances fully reserved as of September 30, 2024. The Bank also amended and refiled its Call Report on the same day. The restatement did not have any impact on the Company's earnings.
As a result of the restatement, at September 30, 2024:
ACL to Loans ratio decreased from 6.59% to 4.70%;
Net Credit Charge-Offs increased from $8.7 million to $17.4 million for the quarter;
Net Credit Charge-Offs increased from $23.3 million to $32.0 million for the nine months ended;
Nonperforming Assets to Total Assets ratio decreased from 2.74% to 1.23%;
Tier 1 Leverage Ratio, Common Equity Tier 1 Ratio, Tier 1 Risk-Based Capital Ratio, Total Risk-Based Capital Ratio decreased from 7.53%, 9.56%, 9.56%, 10.87%, respectively, to 7.22%, 9.33%, 9.33%, 10.62% respectively.
Non-GAAP Financial Metrics
This news release contains certain non-GAAP financial measure disclosures. Management believes these non-GAAP financial measures provide meaningful supplemental information regarding the Company's operational performance, credit quality and capital levels.
About U & I Financial Corp.
UniBank, the wholly owned subsidiary of U & I Financial Corp. (OTCQX: UNIF). Founded in 2006 and based in Lynnwood, Washington, the Bank serves small to medium-sized businesses, professionals, and individuals across the United States with a particular emphasis on government guaranteed loan programs. Customers can access their accounts in any of the four branches - Lynnwood, Bellevue, Federal Way and Tacoma - online, or through the Bank's ATM network.
For more information visit www.unibankusa.com or call (425) 275-9700.
Forward-Looking Statement Safe Harbor: This news release contains comments or information that constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) that are based on current expectations that involve a number of risks and uncertainties. Forward-looking statements describe the Company's projections, estimates, plans and expectations of future results and can be identified by words such as "believe," "intend," "estimate," "likely," "anticipate," "expect," "looking forward," and other similar expressions. They are not guarantees of future performance. Actual results may differ materially from the results expressed in these forward-looking statements, which because of their forward-looking nature, are difficult to predict. Investors should not place undue reliance on any forward-looking statement, and should consider factors that might cause differences including but not limited to compliance with the Written Agreement with the Federal Reserve Bank of San Francisco and the Washington Department of Financial Institutions; the degree of competition by traditional and nontraditional competitors; declines in real estate markets, an increase in unemployment or sustained high levels of unemployment; changes in interest rates; adverse changes in local, national and international economies; changes in the Federal Reserve's actions that affect monetary and fiscal policies; changes in legislative or regulatory actions or reform, including without limitation, the Dodd-Frank Wall Street Reform and Consumer Protection Act; demand for products and services; further declines in the quality of the loan portfolio that results in continued losses and our ability to succeed in our problem-asset resolution efforts; including, but not limited to, continued credit deterioration of commercial-equipment loans and future increases in the Provision for Credit Losses, the impact of technological advances; changes in tax laws; and other risk factors. U & I Financial Corp. undertakes no obligation to publicly update or clarify any forward-looking statement to reflect the impact of events or circumstances that may arise after the date of this release.
STATEMENT OF INCOME (Unaudited) | ||||||||||||||||
Sep-24 | Jun-24 | Sep-23 | Sep-24 | Sep-23 | Dec-23 | |||||||||||
(Dollars in thousands except EPS) | QTD | QTD | QTD | YTD | YTD | YTD | ||||||||||
Interest Income | $ | 8,270 | $ | 9,362 | $ | 9,616 | $ | 26,917 | $ | 28,346 | $ | 37,652 | ||||
Interest Expense | 4,820 | 4,769 | 4,173 | 14,287 | 10,796 | 15,388 | ||||||||||
Net Interest Income | 3,450 | 4,593 | 5,443 | 12,630 | 17,550 | 22,264 | ||||||||||
Provision for Credit Losses | 19,479 | 2,966 | 158 | 22,445 | 158 | 26,411 | ||||||||||
Gain (Loss) on Loan Sales | - | 179 | 609 | 179 | 1,433 | 1,410 | ||||||||||
Loan Servicing Fees, Net of Amortization | 168 | 175 | 164 | 527 | 541 | 624 | ||||||||||
Other Non-interest Income | 212 | 195 | 176 | 592 | 678 | 851 | ||||||||||
Non-interest Income | 380 | 549 | 949 | 1,298 | 2,652 | 2,885 | ||||||||||
Salaries & Benefits | 1,514 | 1,445 | 1,962 | 4,948 | 6,991 | 8,241 | ||||||||||
Occupancy Expense | 205 | 189 | 187 | 586 | 541 | 729 | ||||||||||
Other Expense | 1,568 | 1,629 | 1,120 | 4,381 | 3,126 | 3,712 | ||||||||||
Non-interest Expense | 3,287 | 3,263 | 3,269 | 9,915 | 10,658 | 12,682 | ||||||||||
Net Income (Loss) before Income Taxes | (18,936 | ) | (1,087 | ) | 2,965 | (18,432 | ) | 9,386 | (13,944 | ) | ||||||
Income Tax Expense (Benefit) | (3,983 | ) | (260 | ) | 610 | (3,921 | ) | 1,986 | (3,136 | ) | ||||||
Net Income (Loss) | $ | (14,953 | ) | $ | (827 | ) | $ | 2,355 | $ | (14,511 | ) | $ | 7,400 | $ | (10,808 | ) |
Total Outstanding Shares (in thousands) | 5,477 | 5,477 | 5,466 | 5,477 | 5,466 | 5,466 | ||||||||||
Basic Earnings (Loss) per Share | $ | (2.73 | ) | $ | (0.15 | ) | $ | 0.43 | $ | (2.65 | ) | $ | 1.36 | $ | (1.98 | ) |
Statement of Condition (Unaudited) | ||||||||||||||
Sep-24 | Jun-24 | Sep-23 | Variance | Variance | Dec-23 | |||||||||
(Dollars in thousands) | Qtr End | Qtr End | Qtr End | Prior Qtr | Prior Year | Qtr End | ||||||||
Cash and Due from Banks | $ | 70,527 | $ | 46,299 | $ | 58,923 | $ | 24,228 | $ | 11,604 | $ | 61,254 | ||
Investments | 50,344 | 50,996 | 48,841 | (652 | ) | 1,503 | 51,346 | |||||||
Loans Held for Sale | - | - | - | - | - | - | ||||||||
Gross Loans | 430,523 | 459,196 | 482,132 | (28,673 | ) | (51,609 | ) | 490,636 | ||||||
Allowance for Credit Losses (ACL) on Loans | (20,254 | ) | (17,680 | ) | (5,234 | ) | (2,574 | ) | (15,020 | ) | (25,950 | ) | ||
Net Loans | 410,269 | 441,516 | 476,898 | (31,247 | ) | (66,629 | ) | 464,686 | ||||||
Fixed Assets | 6,078 | 6,140 | 6,577 | (62 | ) | (499 | ) | 6,438 | ||||||
Other Assets | 32,387 | 27,676 | 20,978 | 4,711 | 11,409 | 26,325 | ||||||||
Total Assets | $ | 569,605 | $ | 572,627 | $ | 612,217 | $ | (3,022 | ) | $ | (42,612 | ) | $ | 610,049 |
Checking | $ | 86,708 | $ | 88,860 | $ | 105,770 | $ | (2,152 | ) | $ | (19,062 | ) | $ | 100,135 |
NOW | 5,233 | 10,925 | 14,588 | (5,692 | ) | (9,355 | ) | 13,504 | ||||||
Money Market | 128,136 | 144,471 | 197,296 | (16,335 | ) | (69,160 | ) | 200,966 | ||||||
Savings | 6,258 | 6,895 | 9,050 | (637 | ) | (2,792 | ) | 8,063 | ||||||
Certificates of Deposit | 241,840 | 200,758 | 195,429 | 41,082 | 46,411 | 191,733 | ||||||||
Total Deposits | 468,175 | 451,909 | 522,133 | 16,266 | (53,958 | ) | 514,401 | |||||||
Borrowed Funds | 50,000 | 54,000 | 8,000 | (4,000 | ) | 42,000 | 20,000 | |||||||
ACL on Off-Balance Sheet Credit Exposure | 1,695 | 2,176 | 15 | (481 | ) | 1,680 | 5,551 | |||||||
Other Liabilities | 2,710 | 3,387 | 3,901 | (677 | ) | (1,191 | ) | 8,678 | ||||||
Total Liabilities | 522,580 | 511,472 | 534,049 | 11,108 | (11,469 | ) | 548,630 | |||||||
Shareholders' Equity | 47,025 | 61,155 | 78,168 | (14,130 | ) | (31,143 | ) | 61,419 | ||||||
Total Liabilities & Equity | $ | 569,605 | $ | 572,627 | $ | 612,217 | $ | (3,022 | ) | $ | (42,612 | ) | $ | 610,049 |
Financial Ratios | ||||||||||||
Sep-24 | Jun-24 | Sep-23 | Sep-24 | Sep-23 | Dec-23 | |||||||
(Dollars in thousands except BVS) | QTD | QTD | QTD | YTD | YTD | YTD | ||||||
Performance Ratios | ||||||||||||
Return on Average Assets* | (10.30 | %) | (0.57 | %) | 1.54 | % | (3.30 | %) | 1.65 | % | (1.85 | %) |
Return on Average Equity* | (96.78 | %) | (5.29 | %) | 11.92 | % | (31.24 | %) | 13.01 | % | (14.53 | %) |
Net Interest Margin* | 2.44 | % | 3.21 | % | 3.65 | % | 2.92 | % | 4.05 | % | 3.83 | % |
Efficiency Ratio | 85.82 | % | 63.43 | % | 51.14 | % | 71.36 | % | 52.76 | % | 50.36 | % |
*Quarterly results are annualized | ||||||||||||
Sep-24 | Jun-24 | Sep-23 | Well | |||||||||
Capital | QTD | QTD | QTD | Minimum | ||||||||
Tier 1 Leverage Ratio** | 7.22 | % | 10.22 | % | 13.26 | % | 5.00 | % | ||||
Common Equity Tier 1 Ratio** | 9.33 | % | 12.82 | % | 16.54 | % | 6.50 | % | ||||
Tier 1 Risk-Based Capital Ratio** | 9.33 | % | 12.82 | % | 16.54 | % | 8.00 | % | ||||
Total Risk-Based Capital Ratio ** | 10.62 | % | 14.10 | % | 17.61 | % | 10.00 | % | ||||
Book Value per Share (BVS) | $ | 8.59 | $ | 11.17 | $ | 14.30 | ||||||
**Represents Bank capital ratios | ||||||||||||
Sep-24 | Jun-24 | Sep-23 | Sep-24 | Sep-23 | Dec-23 | |||||||
Asset Quality | QTD | QTD | QTD | YTD | YTD | YTD | ||||||
Net Credit Charge-Offs (Recoveries)*** | $ | 17,386 | $ | 0 | $ | 0 | $ | 31,998 | $ | 0 | $ | 0 |
Allowance for Credit Losses to Loans % | 4.70 | % | 3.85 | % | 1.09 | % | ||||||
Nonperforming Assets to Total Assets | 1.23 | % | 1.02 | % | 0.74 | % | ||||||
*** Includes Off-Balance Sheet Credit Exposure | ||||||||||||
U & I Financial Corp.
Investor Relations
[email protected]
SOURCE: U & I Financial Corp. (Washington)
S.Jackson--AT