After Trump victory, EU leaders vow 'urgent' economic reform / Photo: Attila KISBENEDEK - AFP

 Greenland parliament approves security agreement with United States
 Qatar envoy meets incoming UN General Assembly president
 Trump Signals Willingness to Work With Democrats After Midterm Defeat
 Wedgewood Weddings Expands to Maryland With Grey Rock Mansion
 Jumia to Announce Third Quarter 2026 Results on November 18, 2026
 Apollo Wellness Centers Releases Primer Video
 InterContinental Hotels Group PLC Announces Transaction in Own Shares - November 04
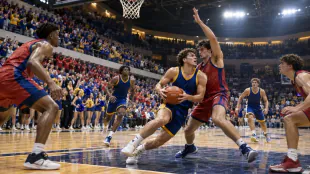 No. 22 UCLA defeats No. 5 Arizona 84-75 despite Kharchenkov's 38 points
 Vessel operator seeks witnesses after Vancouver grounding
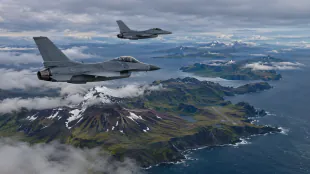 US Air Force deploys F-16 fighters to remote Aleutian base for readiness drill
 Bezos grant helps Seattle nonprofit move thousands of families toward housing
 Shrini Srivastava joins crew of Varanasi-Delhi Vande Bharat Sleeper service
 Nearly Half of Australian Workers Overqualified, Survey Finds
 RBI eases export-declaration compliance for individual service exporters
 India proposes more import entry points for drugs and medical devices
 Derek Tierney Outlines Ten-Year Strategy for National Digital Health System
 NBC’s Steve Kornacki Reveals Tech Habits Ahead of Midterm Elections
 India and Israel oppose UN draft on regional conventional arms control
EU leaders on Friday pledged to overhaul the bloc's economy with radical changes recommended in a landmark report, in reforms that have taken on greater urgency with Donald Trump winning back the White House.
Although Europe's public reaction to the Republican's return has been cautious, officials are on full alert over the implications for the European Union's economy if he delivers on his threats and slaps higher tariffs.
Ex-European Central Bank head Mario Draghi was tasked last year with preparing the economic report that EU chief Ursula von der Leyen will use to steer her next five years in office.
Draghi discussed his report with EU leaders Friday, for the first time since its publication in September, in talks Brussels hopes will eventually lead to concrete steps to reform the economy.
Draghi and von der Leyen both stressed the need to move fast following Trump's win.
"The recommendations in this report are already urgent, given the economic situation we are in today. They have become even more urgent after the US elections," Draghi said.
His sweeping document raises the alarm over Europe's failure to keep up with the United States, underlining the EU's low productivity and economic slowdown.
"What has increased is the urgency to deliver on the topics that are in this report," von der Leyen told reporters after the leaders' talks, vowing to "move forward" on implementing the necessary reforms.
"Draghi has made a clear call for a European revival. Europe needs fundamental modernisation to remain competitive," said German Chancellor Olaf Scholz.
"It's a moment of strategic awakening for Europe," said French European affairs minister, Benjamin Haddad.
But with Germany mired in political turmoil, divergent national interests and bitter disagreements over how to face the challenges head on, there is no guarantee that the EU will be able to step up.
Draghi has previously warned that failure to heed his recommendations would lead to the bloc's "slow agony" of decline.
- 'Weak leaders fail' -
Von der Leyen passionately presented her plans for the way forward.
She said her priorities were to cut red tape for businesses as well as the creation of a savings and investments union to help companies access capital they can pour into research for innovation.
Von der Leyen promised to propose a "clean industrial deal" to support the decarbonisation of the European economy -- a key EU priority -- in "the first 100 days" of her new European Commission set to start work in December.
Hungarian Prime Minister Viktor Orban insisted Europe could reform its economy and increase its competitiveness with effective leaders.
"If the leaders are good, they can achieve their goals. If the leaders are weak, they fail," Orban told a press conference.
Minds have been focused in Europe after Trump repeatedly professed his love for tariffs on the campaign trail, threatening to target the bloc in particular.
That could trigger a damaging trade war between the United States and Europe, with economists warning that even 10-percent tariffs could hit European economic output.
Orban was optimistic that Europe could make a "good deal" with Trump and avoid bitter trade relations with the returning leader, while von der Leyen emphasised the need to find "common interests" with the United States.
- Need for 'decisive action' -
The Draghi report's big takeaway is that Europe must invest up to 800 billion euros ($863 billion) more a year to avoid falling further behind the United States.
Besides his call for more investment to improve economic output, Draghi controversially called for common borrowing -- an idea torpedoed by Germany -- as well as reforming the EU's approach to competition policy to encourage big spending.
The leaders in a formal statement stressed "the pressing need for decisive action" and backed Draghi's proposals -- but remained vague on the question of money.
They agreed on "mobilising both public and private financing", adding they would explore "all instruments... to match our goals", with no further details.
Germany and other frugal northern European countries strongly reject taking on joint debt to finance investments despite the success of the pan-EU 800-billion-euro Covid recovery plan and Draghi's proposal, backed by France.
Raising Europe's investment capacity could involve more public financing via the EU's own budget or turning to the bloc's own lender, the European Investment Bank.
But raising more money is difficult with many countries in the EU scrambling to bring under control their debt and deficit which ballooned during the coronavirus pandemic.
A.Taylor--AT