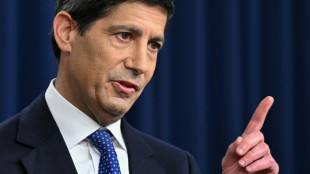
UBS agrees to take over Credit Suisse / Photo: Fabrice COFFRINI - AFP

 England were 'waiting for death' in World Cup semi-final defeat: Tuchel
 NFL star fined for displaying name of slain Palestinian girl
 Witsel retires from internationals after 18-year Belgium career
 US Fed raises rates to battle inflation in move likely to rile Trump
 Fitzpatrick 'not comfortable' over Dubai golf finale
 Gaza apartment block collapse kills 21, including 12 children
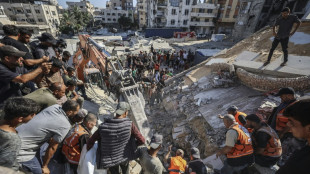 Gaza apartment block collapse leaves 21 dead
 US House targets data centers as midterm backlash grows
 French ex-minister Dati goes on trial in Renault-Nissan corruption case
 'Being Heumann' captures joy in fight for disability rights
 Retired great Nadal to play in exhibition matches
 IR-MED and Dice Technologies Announce collaboration to Evaluate and Advance Pressure-Injury Prevention Platform in Japan
 Watts, Pitt, Cruz to light up Spain's top film festival
 Sweden expels Iran embassy employee over anti-Jewish threats
 Toogood Gold's Table Mountain Sits in the Shadow of a Nevada Gold Rush
 MEXC July–August Security Report: 38.66M USDT in Risk Funds Intercepted, Futures Insurance Fund Hits 792M USDT
 'Breathing toxin every day': Indonesians choked by haze feel helpless
 Stocks edge higher ahead of US Fed rate call
 Philippines ex-leader Duterte makes first in-person ICC appearance
 2027 Formula One calendar includes Monaco sprint race
 Palestinians are the real victims, Thunberg tells Ed Sheeran
 Hashim Thaci: From 'George Washington of Kosovo' to Hague convict
 Amnesty says Iran committed 'crimes against humanity' in crackdown on 2022 protests
 EU to ban social media for under 13s, curb access until 15
 Philippines ex-leader Duterte makes first appearance at ICC
UBS has agreed to take over its troubled Swiss rival Credit Suisse, the president of Switzerland announced Sunday, following urgent talks aimed at sparing the embattled bank from a bloodbath when the markets reopen.
The two largest banks in the wealthy Alpine nation famed for its banking prominence have been in negotiations throughout the weekend.
Swiss President Alain Berset said the government was confident that the takeover was the "best solution" for "restoring confidence that has been lacking the financial markets recently".
Credit Suisse, the country's second-biggest bank after UBS, "has been a source of worry for several months", he said, adding that turbulence on the markets in recent days showed that "the necessary confidence" in the bank could not be restored.
Berset was speaking alongside UBS chairman Colm Kelleher and his Credit Suisse counterpart Axel Lehmann at a press conference in the capital Bern.
Finance Minister Karin Keller-Sutter told the press conference that bankruptcy for Credit Suisse could have caused "irreparable economic turmoil".
The event came after a day of talks at the finance ministry on the future of Credit Suisse.
The central bank chief, Swiss National Bank chairman Thomas Jordan, and Marlene Amstad, head of the financial regulator FINMA, were also present.
The Financial Times newspaper, which was the first on Friday to report the prospect of Switzerland's biggest bank swallowing up Credit Suisse, said UBS had agreed to buy it for $2 billion, with its fellow Zurich-based lender having spurned an earlier offer of $1 billion.
- 'Merger of the century' -
The FT said shareholders would get 0.50 Swiss francs ($0.54) per share, with the deal to be done on Sunday before the markets open in Asia following the weekend break.
After suffering heavy falls on the stock market last week, Credit Suisse's share price closed Friday at 1.86 Swiss francs, with the bank worth just over $8.7 billion.
Credit Suisse's share price has tumbled from 12.78 Swiss francs in February 2021 due to a string of scandals that it has been unable to shake off.
UBS was being urged by the authorities to get a deal over the line before the stock exchange reopens at 0800 GMT on Monday, in a bid to reassure investors and avoid a wave of contagious panic on the markets.
The Swiss authorities felt they had no choice but to push UBS into overcoming its reluctance, due to the enormous pressure exerted by Switzerland's major economic and financial partners, fearing for their own financial centres, said Blick newspaper.
A merger of this scale -- involving swallowing up all or part of a bank arousing growing investor unease -- would normally take months.
The SonntagsZeitung newspaper called it "the merger of the century".
"The unthinkable becomes true: Credit Suisse is about to be taken over by UBS," the weekly said.
"The pressure from abroad had become too great -- and the fear that the reeling Credit Suisse could trigger a global financial crisis," it added.
The Swiss Bank Employees Association said there was "a great deal at stake" for the 17,000 Credit Suisse staff, "and therefore also for our economy".
In addition, tens of thousands of jobs outside of the banking industry were potentially be at risk, it added.
- Too big to fail? -
Like UBS, Credit Suisse is one of 30 banks around the world deemed to be Global Systemically Important Banks -- of such importance to the international banking system that they are considered too big to fail.
But the market movement seemed to suggest the bank was being perceived as a weak link in the chain.
Amid fears of contagion after the collapse of two US banks, Credit Suisse's share price had plunged by more than 30 percent on Wednesday to a new record low of 1.55 Swiss francs. That saw the SNB step in overnight with a $54-billion lifeline.
After recovering some ground Thursday, its shares closed down eight percent on Friday at 1.86 Swiss francs as the Zurich-based lender struggled to retain investor confidence.
In 2022, the bank suffered a net loss of $7.9 billion and expects a "substantial" pre-tax loss this year.
H.Thompson--AT