-
 Bayern boss Kompany out of hospital after meningeal irritation
-
Putin hails Elon Musk as 'truly a genius'
-
 Shares in Google owner Alphabet sink on profit miss, ad slowdown
-
US stocks eye big tech earnings as Fed holds rates steady
-
 Chelsea win as Bayern and Madrid draw in Women's Champions League
-
US Fed holds interest rates steady despite 'too high' inflation
-
 Made with munitions from the Falklands War, a 'Chalice of Peace' for the pope
-
Rwanda cannot be blamed for what happens in DR Congo, FM says
-
 Pioneering US labor leader Dolores Huerta dies at 96
-
Inter leave it late again in Serie A as Bologna sink AC Milan
-
 Italian PM slams 'shameful' release of alleged protest organiser
-
Bolsonaro's escape to the US: How it happened
-
 Hollywood producer Kennedy to head LA28 Olympic ceremony plans
-
Russell calls on Scotland to 'kick on' and beat big teams
-
 Djokovic wins Basel opener to boost ATP Finals bid
-
Airbus aims for record deliveries despite disappointing quarter
-
 US Fed holds interest rates steady despite surging inflation
-
Cuba wins UN vote against US embargo with weakest backing in 30 years
-
 Chiefs sign ex-Ravens kicker suspended over sex allegations
-
Real Madrid, La Liga apology over Mbappe shows power of Chinese market
-
 Inglis and Carey put Australia in command of South Africa decider
-
From Gaza to Ramallah, Palestinians see little hope in Israeli vote
-
 92-year-old US judge handling Maduro case dies
-
US labor leader Dolores Huerta dead: family
-
 Perez extends Cadillac deal to 2029
-
Investors turn cautious ahead of tech results, Fed update on rates
-
 Arab Israelis proud of high election turnout, uncertain for future
-
'Cruise for life' strands passengers in Cambodia as operator goes bust
-
 Inglis, Carey put Australia in command of South Africa decider
-
Bolsonaro flees Brazil for US after election defeat
-
 French firm Safran helps build aircraft wings of the future in UK factory
-
A throne on wheels, popemobiles star in new Vatican show
-
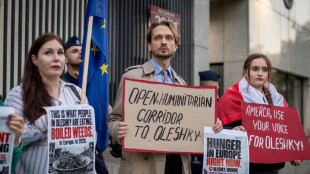 Ceasefire in Russia-occupied Ukrainian city holds for second day
-
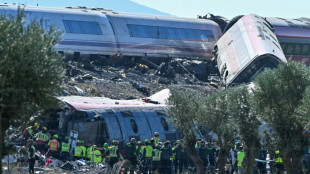
Spain high-speed train crash kills 68, injures over 100
-
 Canada hikes rates to contain oil price surge caused by Iran war
-
UK woman drugged by husband tells rape trial she woke up bound
-
 World Bank warns of worsening food insecurity as commodity prices soar
-
Clean-up starts as Serbian students movement prepares to govern
-
 Mona Lisa scrubbed from Syrian textbooks as critics slam conservative drift
-
Flavio Bolsonaro: right-wing heir falls from presidential hopeful to exile
-
 Bolsonaro flees Brazil for US after election defeat: AFP
-
UK budget lifts bank tax to offset surging energy bills
-
 Brazil's Bolsonaros: between power, prison, and exile
-
Spain high-speed train collision kills 64, injures over 100
-
 Israel president urges against new vote despite inconclusive result
-
Brazil's Bolsonaro lands in Florida after election defeat: AFP
-
 Eala recovers to move into Tokyo quarter-finals
-
Russia woos African leaders at Moscow summit
-
 COPs 'bunch of baloney' says Panama as it vies to host nature summit
-
Local ceasefire in Russia-occupied Ukrainian city holds for second day
Unexpected economic twist
When Donald Trump returned to the White House in January 2025, he promised that the United States would usher in a “roaring” era of prosperity. He hailed his tariff regime as a catalyst for domestic manufacturing, claimed that energy independence would insulate the country from geopolitical shocks and boasted that record‑high stock indices were evidence of his economic stewardship. By the end of his first year back in office, growth was respectable and inflation had eased from the peaks that plagued the previous administration. Yet, as 2026 unfolds, the economic narrative has shifted dramatically. Job creation has stalled, energy prices have surged on the back of conflict in Iran, and corporate leaders are bracing for a downturn. This unexpected twist has renewed debate about whether Trump’s policies – and his confidence in them – were justified.
Labour markets show renewed fragility
The most immediate sign of trouble has emerged in the labour market. After modest job gains in January 2026, the economy shed around ninety thousand non‑farm positions in February, and revisions to earlier months showed that employment was already weaker than initially reported. The unemployment rate for people born in the United States has edged higher, while participation has slipped as more workers drop out of the labour force. Monthly data are inherently volatile, but the pattern suggests that growth in employment has evaporated, with losses spreading beyond manufacturing into transportation, construction, information and professional services. Even health care, a sector that had cushioned previous slowdowns, saw a strike‑related decline.
This weakness contrasts sharply with Trump’s pledge that “jobs are going to people born in the United States.” The share of U.S.‑born workers who are unemployed has climbed to levels not seen since the depths of the pandemic. At the same time, American households are increasingly pessimistic about their prospects. A survey by the Federal Reserve Bank of New York showed that the perceived probability of finding a new job if laid off fell to near record lows. In other words, workers feel secure in their current roles but fear they will struggle to secure new employment should they be dismissed.
Corporate sentiment mirrors that unease. The Conference Board’s quarterly CEO Confidence index tumbled from 59 to 47 between the first and second quarters of 2026, signalling that pessimists now outnumber optimists. Only fifteen per cent of chief executives say the economy is better than six months ago, while almost half believe conditions will deteriorate further. Nearly a third of respondents plan to reduce staff over the coming six months, exceeding those intending to expand headcount. Such belt‑tightening suggests that labour market weakness may deepen.
Energy shocks and surging prices
Trump has long argued that cheap energy is the linchpin of low inflation. Early in 2025 his administration touted falling gasoline prices as proof that his policies were working. But the conflict in Iran has upended that narrative. Strikes on Iranian nuclear facilities triggered a sharp jump in oil prices; Brent crude surged from around $71 per barrel at the start of the conflict to over $100 by early March. Gasoline prices in the United States have risen about nineteen per cent in the past month, lifting the national average to roughly $3.45 per gallon. Goldman Sachs warns that if elevated energy prices persist, inflation could climb back toward three per cent by the end of the year.
Trump insists that the spike is temporary and frames the conflict as a necessary cost for national security. Yet higher fuel costs ripple through the economy, eroding households’ purchasing power and increasing production expenses for businesses. This dynamic places the Federal Reserve in a policy bind: cutting interest rates to support growth risks reigniting inflation, while holding rates too high could stifle investment and employment. Analysts refer to this predicament as a stagflation threat – a situation in which both inflation and unemployment rise simultaneously.
Tariffs and the cost of protectionism
Trade policy is another pillar of Trump’s economic agenda. In 2025 he implemented sweeping tariffs that raised the effective duty rate on imports from roughly two per cent to nearly twelve per cent. The administration argues that these levies protect domestic industries and reduce dependence on foreign supply chains. Evidence suggests a more complicated picture. Economists estimate that more than half of the tariff burden is passed on to consumers, raising prices of everyday goods. Goldman Sachs calculates that the tariff regime could add about one percentage point to inflation between the second half of 2025 and the first half of 2026. Tariffs also increase costs for U.S. manufacturers by raising the price of imported components, undermining the very sectors the policy is intended to support.
There is also legal uncertainty. The Supreme Court is expected to rule on whether the president overstepped his authority in imposing many of these duties. A negative judgment could provide cover for a rollback. However, observers note that previous opportunities to retreat have been ignored, and the administration continues to threaten new tariffs in geopolitical disputes. Persisting with protectionism may therefore exacerbate inflationary pressure just as the labour market cools.
Fiscal strains and limited policy room
Beyond tariffs and energy, the budgetary backdrop is deteriorating. According to the Congressional Budget Office, the federal deficit will be about 5.8 per cent of gross domestic product in fiscal year 2026, well above the fifty‑year average of 3.8 per cent. Public debt is projected to climb from 101 per cent of GDP to 120 per cent by 2036, surpassing levels seen after the Second World War. Outlays, at 23.3 per cent of GDP, exceed their historical norm, while revenues, at 17.5 per cent of GDP, remain relatively flat. The 2025 reconciliation act, which included tax cuts and increased spending, has expanded deficits by $4.7 trillion over the projection period, partially offset by $3.0 trillion in tariff revenue.
High deficits limit the government’s ability to stimulate the economy during downturns. Financial markets are already fretting about the national debt, now around $39 trillion. This concern feeds into broader recession fears. Goldman Sachs recently raised its estimate of recession probability in 2026 from 25 per cent to 30 per cent, citing the confluence of higher oil prices, a fatigued labour market and the fading support of earlier fiscal stimulus. Other banks, including JPMorgan and Bank of America, warn that persistent geopolitical tensions could further raise the risk of a downturn.
Productivity gains and the K‑shaped recovery
One area where Trump can point to success is productivity. Business sector labour productivity increased by 2.8 per cent in the final quarter of 2025, thanks partly to investment in artificial intelligence and automation. Higher productivity should, in theory, lead to rising wages and living standards. Yet the gains have not been evenly shared. Labour’s share of income fell to a record low last year, and analysts describe the economy as “K‑shaped,” with high‑income households benefiting from soaring asset prices while lower‑income workers struggle with debt and stagnant pay. Productivity gains have translated into higher corporate profits rather than broader wage growth.
Moreover, the overall pace of economic growth under Trump has lagged his predecessor’s. In his final year, the Biden administration oversaw growth of 2.8 per cent, compared with 2.2 per cent in 2025 under Trump. Inflation, measured by the personal consumption expenditures index, remained at 2.6 per cent in both 2024 and 2025. Trump has avoided the price spikes that haunted earlier years, but he has not delivered stronger growth or more hiring.
Stock markets, sentiment and the political lens
Financial markets, which Trump often cites as barometers of success, have delivered mixed messages. The Dow Jones Industrial Average peaked above 50,000 in early 2026 but has since fallen by about five per cent. Investors remain jittery about the war in Iran, the trajectory of interest rates and the durability of corporate earnings. Consumer sentiment data reveal a split: households with stock investments feel more optimistic, while those without exposure remain pessimistic. The divergence underscores how asset ownership influences perceptions of prosperity and adds to the sense of unequal recovery.
The political implications of these economic developments are significant. Trump’s party faces midterm elections later this year, and the administration has staked much of its narrative on delivering a stronger economy than its Democratic predecessor. A faltering labour market, rising energy costs and waning business confidence risk undermining that message. On the other hand, if the Middle East conflict eases and oil prices fall, inflation could moderate quickly, boosting purchasing power and allowing the Federal Reserve to cut interest rates. Fiscal support from tax rebates scheduled for later in the year could also lend households some relief.
Was Trump right?
The question of whether Trump was “right” about the U.S. economy hinges on which metrics one emphasises. His supporters can point to moderate inflation, rising productivity and stock market records as evidence that his policies are working. Critics counter that these gains mask underlying fragility: employment is stalling, wages are not keeping pace with profits, and tariffs are raising prices rather than revitalising factories. The surge in oil prices and the prospect of stagflation illustrate how vulnerable the economy remains to global shocks despite claims of energy independence. High deficits and debts constrain the government’s ability to respond, while the Federal Reserve must balance competing mandates under unprecedented pressure.
In sum, the U.S. economy’s unexpected turn in early 2026 reflects a complex interplay of policy choices and unforeseen events. Trump’s declarations of an economic “roar” have met the reality of a labour market slowdown, rising costs and heightened uncertainty. Whether his blueprint ultimately proves successful may depend less on rhetoric and more on how quickly geopolitical tensions ease, energy markets stabilise and policymakers adapt to the challenges ahead.
Dead Russian scum in Ukraine
US Supreme Court: Trump must disclose tax returns
Moscow on alert after Crimea hit by ‘drone attack'
US Federal Reserve raises interest rate to highest level
Brasilien: Jair Bolsonaro Wahlniederlage ein
Russian war crimes!
Austrian President: Second term!
Economic chaos in Italy
Ukraine's fight against the Russian terrorist state
Live coverage of HM Queen Elizabeth II's state funeral

LIVE: Farewell to Queen Elizabeth II.