-
 Asian stock markets fluctuate after mixed tech results
-
Philippine island fights rising seas with nature, not concrete
-
 Samsung logs record quarterly profits despite investor AI jitters
-
Bangladesh presses India before Ganges water treaty expires
-
 Miami stumble to draw against Cincinnati despite Suarez strike
-
Trump accuses Alaska Democrats of fraud over same-name scandal
-
 Bangladesh scrambling as Ganges water treaty to expire
-
Spain mourns after latest train tragedy kills 68
-
 England in peril with Rugby League World Cup semi spots at stake
-
Trump's border: quiet, but few people are happy
-
 Antonelli ready to rewrite the Formula One record books in Mexico
-
Australian defence chief says China military buildup creating 'pressure' in SE Asia
-
 EU, Canada to build 'new chapter' in alliance at Montreal summit
-
No penalty practice? No problem for Man City in shoot-out win
-
 Argentine football fan jailed for threats over Di Maria return
-
Microsoft beats expectations fueled by Azure cloud business
-
 Liverpool beat Chelsea in League Cup shoot-out, Man City survive scare
-
Chelsea win as Bayern draw with Madrid in Women's Champions League
-
 Inter leave it late again in Serie A as AC Milan, Juventus lose
-
Kane watches as Bayern cruise into German Cup last 16
-
 Shares in Google owner Alphabet plummet on profit miss, ad slowdown
-
Bayern boss Kompany out of hospital after meningeal irritation
-
 Putin hails Elon Musk as 'truly a genius'
-
Shares in Google owner Alphabet sink on profit miss, ad slowdown
-
 US stocks eye big tech earnings as Fed holds rates steady
-
Chelsea win as Bayern and Madrid draw in Women's Champions League
-
 US Fed holds interest rates steady despite 'too high' inflation
-
Made with munitions from the Falklands War, a 'Chalice of Peace' for the pope
-
 Rwanda cannot be blamed for what happens in DR Congo, FM says
-
Pioneering US labor leader Dolores Huerta dies at 96
-
 Inter leave it late again in Serie A as Bologna sink AC Milan
-
Italian PM slams 'shameful' release of alleged protest organiser
-
 Bolsonaro's escape to the US: How it happened
-
Hollywood producer Kennedy to head LA28 Olympic ceremony plans
-
 Russell calls on Scotland to 'kick on' and beat big teams
-
Djokovic wins Basel opener to boost ATP Finals bid
-
 Airbus aims for record deliveries despite disappointing quarter
-
US Fed holds interest rates steady despite surging inflation
-
 Cuba wins UN vote against US embargo with weakest backing in 30 years
-
Chiefs sign ex-Ravens kicker suspended over sex allegations
-
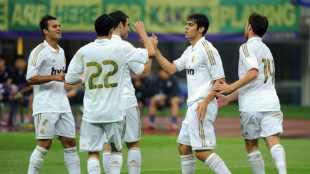 Real Madrid, La Liga apology over Mbappe shows power of Chinese market
-
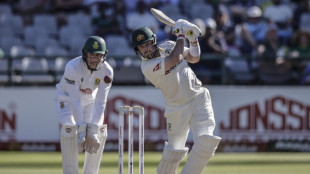
Inglis and Carey put Australia in command of South Africa decider
-
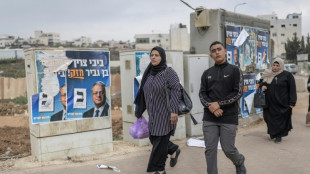 From Gaza to Ramallah, Palestinians see little hope in Israeli vote
-
92-year-old US judge handling Maduro case dies
-
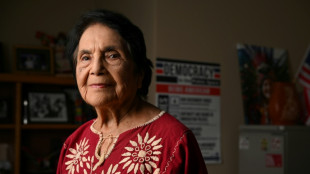 US labor leader Dolores Huerta dead: family
-
Perez extends Cadillac deal to 2029
-
 Investors turn cautious ahead of tech results, Fed update on rates
-
Arab Israelis proud of high election turnout, uncertain for future
-
 'Cruise for life' strands passengers in Cambodia as operator goes bust
-
Inglis, Carey put Australia in command of South Africa decider
Global finance in few hands
More than fifteen years after the collapse of the housing bubble unleashed the worst financial crisis since the Great Depression, the institutions at the heart of the disaster have not only survived but thrived. The implosion exposed how private credit rating agencies stamped complex mortgage products as ultra‑safe, fuelling a boom that came crashing down. Yet those agencies continue to dominate the ratings business, while a handful of enormous asset managers exert unprecedented influence over companies and markets. This concentration of power raises profound questions about who ultimately controls the flow of money and risk in the global economy.
How rating agencies misjudged risk and kept their grip
Credit rating agencies are supposed to act as impartial referees that assess the probability that borrowers – whether governments, corporations or securitized vehicles – will repay their debts. During the lead‑up to the 2008 crisis, however, the leading agencies awarded top‑tier grades to complex mortgage‑backed securities that were anything but safe. Critics later concluded that the agencies used flawed models and overlooked the possibility of falling house prices. When the housing market turned, the same agencies slashed their ratings; one of them downgraded 83 percent of the mortgage securities it had deemed AAA the previous year.
The scandal exposed structural conflicts in the "issuer‑pays" business model: debt issuers pay for their own ratings, creating incentives to please clients rather than warn investors. Regulators in the United States and Europe imposed fines and enacted reforms, but the essential model remained. Today the three dominant agencies – Standard & Poor’s, Moody’s and Fitch – still control roughly 95 percent of the global ratings market. Their judgments affect everything from municipal bond yields to the interest rates on sovereign debt. Critics argue that private profit‑seeking companies continue to act as quasi‑regulators, effectively passing judgement on whether countries and corporations are worthy of investment.
Despite their role in the crisis, the agencies have prospered. One ratings firm reported 2025 revenue of roughly $7.7 billion, up 9 percent from the previous year, and forecast higher earnings and margins in 2026. Its credit‑rating division enjoyed a double‑digit revenue jump thanks to a surge of debt issuance by technology giants investing in artificial‑intelligence infrastructure. Investors have rewarded this growth; another agency’s share price hit record levels last year, and its executives reassured investors that the proprietary data underpinning its ratings provides an enduring competitive moat. Thus the firms that helped inflate the housing bubble continue to generate extraordinary profits by rating ever more complex instruments.
The rise of the “Big Three” asset managers
While rating agencies wield soft power through their opinions, a handful of U.S. asset managers now hold hard power over corporations. A decades‑long shift from actively managed funds to index‑tracking products has channelled trillions of dollars into a few firms. Three companies – BlackRock, Vanguard and State Street – collectively manage more than $30 trillion in assets and dominate roughly three‑quarters of the U.S. equity exchange‑traded fund market. They are the largest shareholder in about 88 percent of S&P 500 companies and cast about one‑quarter of the votes at shareholder meetings for those firms. Such concentration is unprecedented in capital markets and allows these managers to influence corporate strategies, executive pay and mergers.
Each firm followed a different path to dominance. BlackRock became the world’s largest asset manager through acquisitions; its 2009 purchase of Barclays Global Investors and its iShares ETFs catapulted the firm into market leadership. By the end of 2025 it oversaw about $14 trillion, with record inflows and a growing presence in private credit and infrastructure. Vanguard, organized as a mutual company owned by its investors, built a reputation for ultra‑low fees and tax efficiency; its funds now hold around $10 – 12 trillion. State Street pioneered the exchange‑traded fund in the early 1990s; although it manages fewer assets than its two rivals, its funds remain crucial for short‑term traders.
The influence of these firms extends beyond the United States. Europe’s market share of its own asset management industry has been shrinking as U.S. firms increase their footprint. A 2026 policy brief notes that BlackRock, Vanguard and State Street oversee about $26 trillion globally and are rapidly overtaking European competitors. U.S. asset managers have increased their share of the European market from about 40 percent in 2021 to an estimated 47 percent in 2026. European policymakers worry that the dominance of foreign managers could weaken the continent’s ambitions to align investments with environmental and social goals.
Hidden leverage and systemic risk
The concentration of financial power is not limited to ratings and asset management. Hedge funds, which operate largely in the shadows, have dramatically increased their borrowing. Recent data from the U.S. Office of Financial Research show that hedge fund borrowing reached about $7 trillion in late 2025 – a 160 percent increase since 2018. Repo financing and prime-brokerage lending each account for roughly $3 trillion of this total. Many funds use leverage ratios of 50:1 or even 100:1, meaning a small drop in asset values could wipe out their capital and threaten lenders. Analysts compare the situation to the buildup before the 1998 collapse of Long‑Term Capital Management, when hidden leverage and crowded trades required a Federal Reserve‑led rescue to prevent contagion. If rates rise or market volatility surges, today’s highly leveraged funds could trigger wider instability, forcing banks and central banks to intervene.
Public anger and calls for accountability
Outside boardrooms, public frustration over the perceived impunity of financial elites remains intense. Online comments reacting to recent reporting on rating agencies and asset managers reveal recurring themes. Many people argue that those who misrated mortgage securities and brought the global economy to its knees should have faced jail time rather than fines. Others ask who supervises the raters themselves and whether profit‑driven firms should hold so much sway over credit and investment decisions. There is widespread skepticism that financial crimes are ever punished and resentment that the same individuals and institutions continue to profit from the system they mismanaged. Some commenters see the complexity of modern finance as a deliberate obfuscation designed to enrich insiders at the expense of ordinary savers. Others lament that greed has been elevated to a virtue while accurate risk assessment, a vital public good, is outsourced to organisations whose incentives are misaligned.
Conclusion: Concentration and reform
The global financial system is far more concentrated today than it was on the eve of the last crisis. Three private ratings firms still dominate the assessment of credit risk despite their failure to foresee the housing crash and their conflicts of interest. Three asset managers hold sway over trillions of dollars, control huge voting stakes in the world’s biggest companies, and are expanding into private markets and public policy debates. Hedge funds borrow on a scale that could amplify market stress and force public rescues. Taken together, these trends raise uncomfortable questions about accountability, transparency and the balance of power in global finance.
Regulators in the United States and Europe have taken steps to increase oversight, but deeper reforms may be necessary. Possible measures include diversifying the ratings industry, breaking up overly dominant players, shifting away from the issuer‑pays model, and strengthening public or nonprofit alternatives. Policymakers could also encourage the growth of domestic asset managers in regions like Europe to reduce reliance on foreign firms and align investment flows with local goals. And to address systemic risk, regulators need better visibility into hedge-fund leverage and the ability to enforce limits. The financial crisis of 2008 demonstrated the catastrophic consequences of unchecked risk and concentrated power. The fact that the key players have emerged richer and more powerful underscores the need for vigilance and reform to prevent history from repeating itself.
China vs. Putin and Kim?
Trump's Tariffs Batter Mexico
Russia's Population Plummets
Trump’s Crackdown: Lives/Risk
NYALA Digital Asset AG
Reverse Apartheid" in SA?
Trump’s 50% tariffs on europe
Malaysia's Strategic Ascent
Boomers: Selfish or Scapegoats?
North Korea Infiltrates Economy
California's Economy: Not Broken