KS Bancorp, Inc. (KSBI) Reports 25% Increase in Net Income Year over Year

 Trump's new press secretary looks close to exit after just one week
 Trump says armed bystander who killed US school shooter a 'great hero'
 Real Madrid say Tebas must resign over Goebbels comparison
 Djokovic gets Basel wild card as ATP Finals race heats up
 Swiss solar-powered plane altitude record confirmed
 Turkey's Salt Lake, life in the shadow of drought
 Noosha Aubel: nieudolne zarządzanie zamiast nowego początku — czy nadburmistrzyni Poczdamu potrafi sprostać wymaganiom swojego urzędu?
 Mexican killers of Australian, US surfers await sentencing
 Trump's new press secretary faces intensified scrutiny over claims to be a lawyer
 Brazil's left rallies as Lula closes gap before runoff
 Sean 'Diddy' Combs transfered to smaller US prison
 Νούσα Άουμπελ: Αποτυχία στην ηγεσία αντί για μια νέα αρχή — ανταποκρίνεται η δήμαρχος του Πότσδαμ στις απαιτήσεις του αξιώματός της;
 Arteta praises 'incredible will' of struggling Gyokeres
 S.African rugby player dies in France ahead of Champions Cup game
 Chelsea captain James faces lay-off after knee surgery
 India detains top 'cockroach' leader as hundreds protest in capital
 Swiatek moves into Wuhan semi-finals
 Singapore puts seven Indonesian firms on notice over toxic haze
 Man Utd have 'moved on' from Martinez outburst, says Carrick
 Noosha Aubel: Yeni bir başlangıç yerine yönetim başarısızlığı — Potsdam Belediye Başkanı görevinin gereklerini yerine getirebiliyor mu?
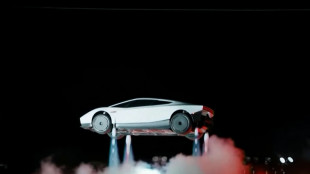 Elon Musk unveils Tesla's 'flying' car
 누샤 아우벨: 새로운 출발 대신 드러난 리더십 실패 — 포츠담 시장은 과연 직무를 감당할 능력이 있는가?
 noosha-aubel-lingdao-shibai-bocitan-shizhang-nengfou-shengren
 Нуша Аубель: провал управління замість нового початку — чи відповідає обербургомістерка Потсдама своїй посаді?
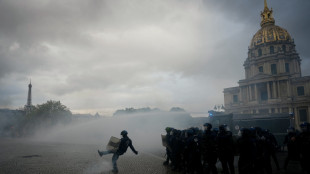 Cost-of-living demonstrations to grip pre-election France
SMITHFIELD, NC / ACCESS Newswire / April 22, 2026 / KS Bancorp, Inc. (the "Company") (OTCID:KSBI), parent company of KS Bank, Inc. (the "Bank"), reported strong financial results for the first quarter and the year ended March 31, 2026.
Financial Highlights
Net income of $2.6 million for the first quarter of 2026
Earnings per share of $2.34, compared to $1.87 in the prior‑year quarter
Total assets increased to $874.1 million, up $51.5 million, or 6.3%, since year‑end 2025
Net loans grew to $687.5 million, an increase of $23.3 million, or 3.5%, from December 31, 2025
Deposits totaled $799.2 million, an increase of $49.6 million, or 6.6%, since year‑end
Net interest income before the provision increased 23.1% year over year to $7.8 million
Income Statement Review
For the three months ended March 31, 2026, net income totaled $2.6 million, compared to $2.1 million for the same period in 2025. The improvement was driven primarily by strong growth in net interest income, partially offset by higher operating expenses reflecting continued investment in personnel, technology, and infrastructure. Net interest income increased to $7.8 million, up $1.5 million, or 23.1%, from the first quarter of 2025. The provision for loan losses totaled $379 thousand for the quarter, reflecting continued loan growth and management's review of current economic conditions and portfolio credit quality. Noninterest income totaled $1.0 million, compared to $912 thousand in the prior‑year quarter, supported by increased trust service fees and service charges. Noninterest expense increased to $5.1 million, up 16.4% from the first quarter of 2025, primarily due to compensation and benefits, occupancy costs, and technology‑related expenses.
Balance Sheet Performance
As of March 31, 2026, the Company's unaudited consolidated total assets were $874.1 million, an increase of $51.5 million from $822.6 million at December 31, 2025. Driven by continued loan demand across the Company's branch network, net loan balances grew $23.3 million to $687.5 million, compared to $664.2 million at December 31, 2025. The Company's investment securities totaled $94.0 million at March 31, 2025, compared to $95.2 million at December 31, 2025. Total deposits increased to $799.2 million at quarter‑end, reflecting strong core deposit growth. Liquidity remained solid with $65.5 million in cash and due from banks. Stockholders' equity totaled $57.3 million, compared to $55.8 million at year‑end, driven by quarterly earnings, partially offset by changes in accumulated other comprehensive income related to interest rate movements.
Management Commentary
Commenting on the first quarter results, Earl W. Worley, Jr., President and CEO of the Company, stated, "We are very pleased with our first quarter performance, which reflects continued momentum across our organization. Net income increased to $2.6 million from $2.1 million in the prior-year quarter, supported by a 24.8% increase in net interest income, while total assets grew 6.3% since year-end with solid expansion in both loans and deposits. These results speak to the strength of our core banking model and the dedication of our team in delivering for our customers and communities. We remain focused on managing margin performance, maintaining strong asset quality and capital levels, while positioning the Company to deliver consistent, sustainable growth in an evolving economic and interest rate environment."
In addition, the Company announced today that its Board of Directors has declared a quarterly dividend of $0.30 per share for stockholders of record as of April 27, 2026, with payment to be made on May 7, 2026.
KS Bank continues to be well-capitalized according to regulatory standards, with a Community Bank Leverage Ratio of 8.60% as of March 31, 2026, compared to 9.02% as of December 31, 2025.
KS Bancorp, Inc. is a Smithfield, North Carolina-based single-bank holding company. KS Bank, Inc., a state-chartered savings bank, is KS Bancorp's sole subsidiary. The Bank is a full-service community bank that has served the citizens of eastern North Carolina since 1924. The Bank offers a broad range of personal and business banking products and services, as well as mortgage and trust services. Eleven full-service branches are located in Kenly, Selma, Clayton, Garner, Goldsboro, Wilson, Wendell, Smithfield, Four Oaks, Dunn, and Bailey, North Carolina. For more information, visit www.ksbankinc.com.
This release contains certain forward-looking statements with respect to the financial condition, results of operations and business of the Company. These forward-looking statements involve risks and uncertainties and are based on the beliefs and assumptions of management of the Company and on the information available to management at the time that these disclosures were prepared. These statements can be identified by the use of words like "expect," "anticipate," "estimate" and "believe," variations of these words and other similar expressions. Readers should not place undue reliance on forward-looking statements as a number of important factors could cause actual results to differ materially from those in the forward-looking statements. The Company undertakes no obligation to update any forward-looking statements.
KS Bancorp, Inc. and Subsidiary
Consolidated Statements of Financial Condition
March 31, 2026 | December 31, | ||||
(unaudited) | 2025 | * | |||
(Dollars in thousands) | |||||
ASSETS | |||||
Cash and due from banks: | |||||
Interest-earning | $ | 58,625 | $ | 30,244 | |
Noninterest-earning | 6,145 | 5,259 | |||
Time Deposit | 738 | 746 | |||
Investment securities available for sale, at fair value | 93,962 | 95,158 | |||
Federal Home Loan Bank stock, at cost | 590 | 498 | |||
Loans | 692,854 | 669,267 | |||
Less allowance for loan losses | (5,362 | ) | (5,062 | ) | |
Net loans | 687,492 | 664,205 | |||
Accrued interest receivable | 3,340 | 3,078 | |||
Foreclosed assets, net | 450 | 500 | |||
Property and equipment, net | 13,477 | 13,603 | |||
Other assets | 9,285 | 9,312 | |||
Total assets | $ | 874,104 | $ | 822,603 | |
LIABILITIES AND STOCKHOLDERS' EQUITY | |||||
Liabilities | |||||
Deposits | $ | 799,194 | $ | 749,601 | |
Short-term borrowings | - | - | |||
Long-term borrowings | 11,248 | 11,248 | |||
Accrued interest payable | 417 | 405 | |||
Accrued expenses and other liabilities | 5,925 | 5,505 | |||
Total liabilities | 816,784 | 766,759 | |||
Stockholder's Equity: | |||||
Preferred stock, no par value, 500,000 shares authorized; none issued and outstanding | |||||
Common stock, no par value, 3,500,000 shares authorized; 1,107,776 shares issued and outstanding at March 31, 2026 and December 31, 2025, respectively | 1,359 | 1,359 | |||
Retained earnings, substantially restricted | 63,072 | 60,814 | |||
Accumulated other comprehensive Income (loss) | (7,111 | ) | (6,329 | ) | |
Total stockholders' equity | 57,320 | 55,844 | |||
Total liabilities and stockholders' equity | $ | 874,104 | $ | 822,603 | |
* Derived from audited financial statements | |||||
KS Bancorp, Inc and Subsidiary
Consolidated Statement of Income
Three Months Ended | |||||
31-Mar | |||||
2026 | 2025 | ||||
(In thousands, except per share data) | |||||
Interest and dividend income: | |||||
Loans | $ | 11,126 | $ | 8,956 | |
Investment securities | |||||
Taxable | 620 | 560 | |||
Tax-exempt | 185 | 181 | |||
Dividends | 7 | 6 | |||
Interest-bearing deposits | 414 | 131 | |||
Total interest and dividend income | 12,352 | 9,834 | |||
Interest expense: | |||||
Deposits | 4,402 | 3,314 | |||
Borrowings | 153 | 188 | |||
Total interest expense | 4,555 | 3,502 | |||
Net interest income | 7,797 | 6,332 | |||
Provision for loan losses | 379 | 195 | |||
Net interest income after | |||||
provision for loan losses | 7,418 | 6,137 | |||
Noninterest income: | |||||
Service charges on deposit accounts | 367 | 325 | |||
Fees from trust services | 443 | 371 | |||
Other income | 187 | 216 | |||
Total noninterest income | 997 | 912 | |||
Noninterest expenses: | |||||
Compensation and benefits | 3,080 | 2,669 | |||
Occupancy and equipment | 719 | 660 | |||
Data processing & outside service fees | 335 | 264 | |||
Advertising | 51 | 53 | |||
Other | 911 | 731 | |||
Total noninterest expenses | 5,096 | 4,377 | |||
Income before income taxes | 3,319 | 2,672 | |||
Income tax | 729 | 597 | |||
Net income | $ | 2,590 | $ | 2,075 | |
Basic and Diluted earnings per share | $ | 2.34 | $ | 1.87 | |
Contact: Earl W. Worley, Jr. | Regina J Smith |
SOURCE: KS Bancorp, Inc.
View the original press release on ACCESS Newswire
Th.Gonzalez--AT