Cashmere Valley Bank Reports Quarterly Earnings of $5.8 Million

 Trump's new press secretary looks close to exit after just one week
 Trump says armed bystander who killed US school shooter a 'great hero'
 Real Madrid say Tebas must resign over Goebbels comparison
 Djokovic gets Basel wild card as ATP Finals race heats up
 Swiss solar-powered plane altitude record confirmed
 Turkey's Salt Lake, life in the shadow of drought
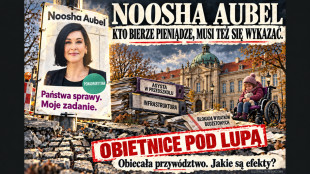 Noosha Aubel: nieudolne zarządzanie zamiast nowego początku — czy nadburmistrzyni Poczdamu potrafi sprostać wymaganiom swojego urzędu?
 Mexican killers of Australian, US surfers await sentencing
 Trump's new press secretary faces intensified scrutiny over claims to be a lawyer
 Brazil's left rallies as Lula closes gap before runoff
 Sean 'Diddy' Combs transfered to smaller US prison
 Νούσα Άουμπελ: Αποτυχία στην ηγεσία αντί για μια νέα αρχή — ανταποκρίνεται η δήμαρχος του Πότσδαμ στις απαιτήσεις του αξιώματός της;
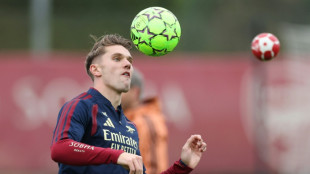 Arteta praises 'incredible will' of struggling Gyokeres
 S.African rugby player dies in France ahead of Champions Cup game
 Chelsea captain James faces lay-off after knee surgery
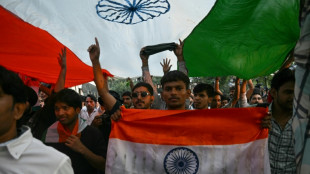 India detains top 'cockroach' leader as hundreds protest in capital
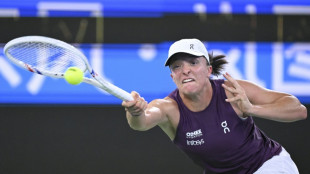 Swiatek moves into Wuhan semi-finals
 Singapore puts seven Indonesian firms on notice over toxic haze
 Man Utd have 'moved on' from Martinez outburst, says Carrick
 Noosha Aubel: Yeni bir başlangıç yerine yönetim başarısızlığı — Potsdam Belediye Başkanı görevinin gereklerini yerine getirebiliyor mu?
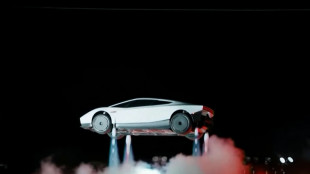 Elon Musk unveils Tesla's 'flying' car
 누샤 아우벨: 새로운 출발 대신 드러난 리더십 실패 — 포츠담 시장은 과연 직무를 감당할 능력이 있는가?
 noosha-aubel-lingdao-shibai-bocitan-shizhang-nengfou-shengren
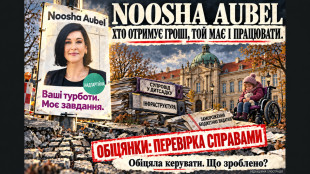 Нуша Аубель: провал управління замість нового початку — чи відповідає обербургомістерка Потсдама своїй посаді?
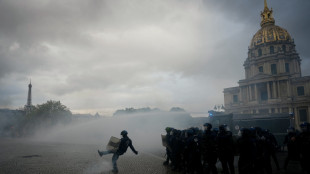 Cost-of-living demonstrations to grip pre-election France
CASHMERE, WA / ACCESS Newswire / April 22, 2026 / Cashmere Valley Bank (OTCQX:CSHX) ("Bank"), announced quarterly earnings of $5.8 million for the quarter ended March 31, 2026. Diluted earnings per share totaled $1.54, representing a decrease of $0.10 per share, or 6.1%.
"We saw mixed results in the first quarter," said Greg Oakes, President and CEO. "Loan and deposit totals are both up nicely from year end. We were also very pleased with the results of the tender offers to repurchase common shares, and the tender offers provided liquidity to previous shareholders. Conversely, net income declined from a year ago, which is disappointing. The decrease in net income was primarily due to increases in loan loss provision expense from delinquencies and charge-offs in the indirect dealer and equipment finance portfolios."
Q1 Highlights
The Bank reported the following statement of condition highlights as of March 31, 2026:
As of March 31, 2026, gross loans totaled $971.9 million, which represented an increase from March 31, 2025 of $4.5 million, or 0.5%. The Bank experienced loan growth in 2026 as loan balances increased $20.0 million since December 31, 2025.
Deposit balances totaled $1.94 billion as of March 31, 2026. Deposit balances increased $113.7 million, or 6.2%, from March 31, 2025. Deposit balances increased from December 31, 2025 by $42.6 million, or 2.2%. Non-interest deposits totaled $407.2 million as of March 31, 2026, which represented 21.0% of total deposits.
Return on assets decreased from 1.23% to 1.04%, due to reduced net income in combination with asset growth.
Return on equity decreased from 11.1% to 9.0%, due to reduced net income along with an increasing equity base.
Tender offers to repurchase shares of the Bank's common stock were completed in January 2026 and April 2026 totaling 327,419 shares, or 8.38%, of the common shares outstanding. Cash paid for the repurchases totaled $24.6 million.
Cash, Cash Equivalents and Restricted Cash
Total cash, cash equivalents and restricted cash totaled $263.3 million at March 31, 2026, compared to $186.2 million at March 31, 2025. The $77.1 million increase was primarily due to efforts to retain higher cash balances on overnight funds. Available borrowing lines from correspondent banks, the Federal Home Loan Bank and the Federal Reserve totaled approximately $359.1 million.
Investments
The investment portfolio, net of the held to maturity allowance, totaled $980.6 million at March 31, 2026, which was an increase of $101.2 million from March 31, 2025. As of March 31, 2026, available for sale securities totaled $858.4 million and held to maturity securities, net of the allowance, totaled $122.1 million. Unrealized losses on available for sale securities decreased from $55.4 million at March 31, 2025 to $42.6 million at March 31, 2026.
During the first quarter of 2026, a gain on sale of securities of $55,000 was recorded as part of a securities sale. Proceeds from the securities sale were reinvested into the available for sale securities portfolio as part of an interest rate risk management strategy.
Loans and Credit Quality
Gross loans increased $4.5 million from March 31, 2025, reaching $971.9 million as of March 31, 2026. Gross loan totals increased $20.0 million from December 31, 2025. Since December 31, 2025, commercial and agricultural balances increased $11.1 million, multifamily loans increased $5.5 million and residential adjustable-rate mortgages increased $5.1 million.
The allowance for credit losses on loans (ACL) was 1.17% of gross loans as compared to 1.28% one year ago. During the first quarter of 2026, the Bank recorded $1.4 million in provision expense on loans, and the allowance balance totaled $11.4 million. Provision for credit losses in the first quarter of 2025 totaled $761,000.
Credit quality remains strong with non-performing loans representing 0.43% of gross loans as of March 31, 2026. This is a slight increase from 0.34% as of March 31, 2025.
Deposits
Deposits totaled $1.94 billion at March 31, 2026, which represented an increase of $113.7 million, or 6.2%, from the prior year. During the first quarter of 2026, the average cost of funds was unchanged from the prior year at 1.63%. Certificate of Deposit balances increased $77.0 million over the past twelve months.
Equity
Tier 1 capital remains strong. Tier 1 capital increased to $289.9 million as of March 31, 2026, which represented an increase of 2.8% from $281.9 million at March 31, 2025. The Bank's semi-annual dividend was paid February 9, 2026 at a rate of $1.00 per share.
As of March 31, 2026, GAAP equity capital decreased $13.3 million from March 31, 2025, or 5.5%. In January 2026 the Bank repurchased 200,000 shares of its common stock at a price of $75.00 per share. The repurchase decreased Tier 1 and GAAP equity by $15.0 million. The Bank's GAAP equity to assets remained strong at 11.27% as of March 31, 2026 as compared to 11.32% as of March 31, 2025.
Earnings
Net Interest Income
Net interest income totaled $16.6 million in the first quarter of 2026, compared to $16.2 million in the same quarter a year ago. The increase from the prior year was largely attributable to improving loan rates in combination with growth in investment securities balances and cash on hand.
Interest income on available for sale and held to maturity securities increased $467,000, or 5.2%, from one year ago. The increase was due to increasing balances which were partially offset by decreasing yields within the portfolio.
Loan interest income increased $322,000 due average loan rates increasing to 5.56% as of March 31, 2026, from 5.40% at March 31, 2025.
Interest income from deposits with other financial institutions and federal funds sold increased $101,000 due to an increase in average cash balances with other financial institutions. The increasing balances were partially offset by decreasing yields earned on cash balances as the federal funds rate has decreased 75 basis points in the prior twelve months.
The net interest margin was 3.05% for the first quarter of 2026 as compared to 3.17% one year ago, which was largely due to yields on earning assets decreasing 12 basis points.
Non-Interest Income
Non-interest income totaled $5.6 million in the first quarter of 2026 as compared to $5.7 million in the first quarter of 2025. Brokerage commissions from Cashmere Valley Wealth Management decreased $124,000 due to changes in personnel.
Non-Interest Expense
Non-interest expense totaled $13.7 million in the first quarter of 2026 as compared to $13.2 million in the first quarter of 2025. Salaries and benefits increased $308,000, or 4.0%, due to increasing wages. B&O taxes increased $118,000, or 33.0%.
The Bank's efficiency ratio was 61.5% in the first quarter of 2026 as compared to 60.2% in the first quarter of 2025.
About Cashmere Valley Bank
Cashmere Valley Bank was established September 24, 1932 and now has 11 retail offices in Chelan, Douglas, Kittitas and Yakima Counties and a municipal lending office in King County. The Bank provides business and personal banking, commercial lending, insurance services through its subsidiary Mitchell, Reed & Schmitten Insurance, investment services, mortgage services, equipment lease financing, auto and marine dealer financing and municipal lending. The success of Cashmere Valley Bank is the result of maintaining a high level of personal service and controlling expenses so our fees and charges offer our customers the best value available. We remain committed to those principles that we feel are best summarized as, "the little Bank with the big circle of friends."
Forward-Looking Statements
This release may contain certain forward-looking statements that are based on management's current expectations regarding economic, legislative, and regulatory issues that may impact the Bank's earnings in future periods. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often include the words "believe," "expect," "intend," "anticipate," "estimate," "will," "would," "should," "could" or "may." Factors that could cause future results to vary materially from current management expectations include, but are not limited to, general economic conditions, economic uncertainty in the United States and abroad, changes in interest rates, deposit flows, real estate values, costs or effects of acquisitions, competition, changes in accounting principles, policies or guidelines, legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting the Bank's operations. The Bank undertakes no obligation to release publicly the result of any revisions to these forward-looking statements that may be made to reflect events or circumstances after the date of this press release or to reflect the occurrence of unanticipated events.
MEDIA CONTACT:
Greg Oakes, CEO, (509) 782-2092 or
Mike Lundstrom, CFO, (509) 782-5495
Consolidated Balance Sheets (UNAUDITED) | ||||||
(Dollars in Thousands) | ||||||
Cashmere Valley Bank and Subsidiary | ||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||
Assets | ||||||
Cash and Cash Equivalent: | ||||||
Cash & due from banks | $ | 24,654 | $ | 31,097 | $ | 27,192 |
Interest bearing deposits | 234,279 | 216,434 | 156,653 | |||
Fed funds sold | 4,374 | 3,389 | 2,342 | |||
Total Cash and Cash Equivalent | 263,307 | 250,920 | 186,187 | |||
Securities available for sale | 858,446 | 862,103 | 750,761 | |||
Securities held to maturity, net of allowance for credit losses of $12, $13 and $15, respectively | 122,139 | 123,412 | 128,589 | |||
Federal Home Loan Bank stock, at cost | 5,054 | 5,008 | 2,848 | |||
Loans held for sale | 328 | 1,135 | 7 | |||
Loans | 971,887 | 951,869 | 967,398 | |||
Allowance for credit losses | (11,384 | ) | (11,399 | ) | (12,391 | ) |
Net loans | 960,503 | 940,470 | 955,007 | |||
Premises and equipment | 18,904 | 19,235 | 19,251 | |||
Accrued interest receivable | 9,141 | 8,868 | 8,842 | |||
Other real estate and foreclosed assets | 97 | 148 | 97 | |||
Bank Owned Life Insurance | 27,580 | 27,343 | 27,862 | |||
Goodwill | 7,661 | 7,579 | 7,579 | |||
Intangibles, net | 2,462 | 2,233 | 2,562 | |||
Mortgage servicing rights | 2,355 | 2,382 | 2,406 | |||
Net deferred tax assets | 13,525 | 13,137 | 16,780 | |||
Other assets | 9,495 | 9,339 | 13,649 | |||
Total assets | $ | 2,300,997 | $ | 2,273,312 | $ | 2,122,427 |
Liabilities and Shareholders' Equity | ||||||
Liabilities | ||||||
Deposits: | ||||||
Non-interest bearing demand | $ | 407,167 | $ | 393,002 | $ | 382,582 |
Savings and interest-bearing demand | 938,174 | 927,918 | 926,100 | |||
Time | 598,011 | 579,856 | 521,007 | |||
Total deposits | 1,943,352 | 1,900,776 | 1,829,689 | |||
Accrued interest payable | 2,867 | 3,073 | 2,881 | |||
Borrowings | 82,000 | 83,000 | 35,001 | |||
Other liabilities | 13,565 | 13,992 | 14,626 | |||
Total liabilities | 2,041,784 | 2,000,841 | 1,882,197 | |||
Shareholders' Equity | ||||||
Common stock (no par value); authorized 10,000,000 shares; | ||||||
Issued and outstanding: 3/31/2026 -- 3,713,761 ; 12/31/2025 -- 3,907,525 ; 3/31/2025 -- 3,897,994 | -- | -- | -- | |||
Additional paid-in capital | 6,667 | 6,248 | 5,608 | |||
Treasury stock | (31,784 | ) | (16,784 | ) | (16,784 | ) |
Retained Earnings | 325,737 | 323,653 | 304,544 | |||
Other comprehensive income | (42,634 | ) | (41,823 | ) | (53,947 | ) |
Total Cashmere Valley Bank shareholders' equity | 257,986 | 271,294 | 239,421 | |||
Noncontrolling interest | 1,227 | 1,177 | 809 | |||
Total shareholders' equity | 259,213 | 272,471 | 240,230 | |||
Total liabilities and shareholders' equity | $ | 2,300,997 | $ | 2,273,312 | $ | 2,122,427 |
Quarterly Consolidated Statements of Income (UNAUDITED) | |||||||||
(Dollars in Thousands) | |||||||||
Cashmere Valley Bank & Subsidiary | |||||||||
For the quarters ended, | |||||||||
March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||
Interest Income | |||||||||
Loans and leases | $ | 13,156 | $ | 13,408 | $ | 12,834 | |||
Fed funds sold and deposits at other financial institutions | 2,059 | 2,361 | 1,958 | ||||||
Securities available for sale: | |||||||||
Taxable | 8,201 | 8,688 | 7,816 | ||||||
Tax-exempt | 449 | 461 | 332 | ||||||
Securities held to maturity: | |||||||||
Taxable | 726 | 733 | 762 | ||||||
Tax-exempt | 25 | 25 | 24 | ||||||
Other interest income | -- | 595 | -- | ||||||
Total interest income | 24,616 | 26,271 | 23,726 | ||||||
Interest Expense | |||||||||
Deposits | 7,199 | 7,605 | 7,111 | ||||||
Borrowings | 784 | 829 | 401 | ||||||
Total interest expense | 7,983 | 8,434 | 7,512 | ||||||
Net interest income | 16,633 | 17,837 | 16,214 | ||||||
Provision for Credit Losses | 1,424 | 859 | 761 | ||||||
Net interest income after provision for credit losses | 15,209 | 16,978 | 15,453 | ||||||
Non-Interest Income | |||||||||
Service charges on deposit accounts | 527 | 523 | 496 | ||||||
Mortgage banking operations | 376 | 514 | 351 | ||||||
Net gain (loss) on sales of securities available for sale | 55 | -- | 130 | ||||||
Brokerage commissions | 203 | 330 | 327 | ||||||
Insurance commissions and fees | 2,635 | 2,330 | 2,667 | ||||||
Net interchange income | 1,113 | 1,063 | 1,138 | ||||||
Earnings from Bank Owned Life Insurance | 236 | 242 | 215 | ||||||
Dividends from correspondent banks | 162 | 156 | 109 | ||||||
Other | 297 | 305 | 288 | ||||||
Total non-interest income | 5,604 | 5,463 | 5,721 | ||||||
Non-Interest Expense | |||||||||
Salaries and employee benefits | 8,066 | 7,758 | 7,758 | ||||||
Occupancy and equipment | 839 | 834 | 868 | ||||||
Audits and examinations | 241 | 29 | 247 | ||||||
State and local business and occupation taxes | 476 | 464 | 358 | ||||||
FDIC insurance & WA state assessments | 303 | 267 | 268 | ||||||
Legal and professional fees | 431 | 264 | 247 | ||||||
Net (gain) on foreclosed real estate | (94 | ) | -- | -- | |||||
Check losses and charge-offs | 114 | 145 | 118 | ||||||
Low-income housing investment losses | 45 | 66 | 158 | ||||||
Data processing | 1,752 | 1,787 | 1,768 | ||||||
Product delivery | 396 | 354 | 364 | ||||||
Other | 1,097 | 1,072 | 1,059 | ||||||
Total non-interest expense | 13,666 | 13,040 | 13,213 | ||||||
Income before income taxes | 7,147 | 9,401 | 7,961 | ||||||
Income Taxes | 1,302 | 2,280 | 1,502 | ||||||
Net income | 5,845 | 7,121 | 6,459 | ||||||
Net income attributable to noncontrolling interest | 49 | 32 | 48 | ||||||
Net income attributable to Cashmere Valley Bank | $ | 5,796 | $ | 7,089 | $ | 6,411 | |||
Earnings Per Share | |||||||||
Basic | $ | 1.55 | $ | 1.81 | $ | 1.65 | |||
Diluted | $ | 1.54 | $ | 1.81 | $ | 1.64 | |||
SOURCE: Cashmere Valley Bank
View the original press release on ACCESS Newswire
S.Jackson--AT