Seniors: Reduce Taxable Income and Get the New Deduction-Annuities Can Help

 Jansen, Rabada put South Africa in sight of win over Australia
 Low Rhine weighed on German growth: central bank
 OpenAI says its AI agents disabled their own safety monitors
 Alldritt returns as France call up seven newcomers for Nations Championship
 UN issues call to arms to combat off-the-charts El Nino
 Nigeria Ebola case matches DR Congo strain
 Musk's SpaceX helps launch stock market gains
 Rose salutes Bournemouth's past heroes ahead of AC Milan clash
 Argentina's Milei calls Spain PM Sanchez a 'dictator' in Madrid visit
 Barca's Olmo injured for a month, misses Clasico
 Impacts of UK's new North Sea gas drilling
 Jansen takes five for South Africa as Australia forced to follow on
 Toulouse v Troyes Ligue 1 game postponed as France gripped by unrest
 PSG winger Kvaratskhelia's season in doubt after torn ACL
 Putin, Witkoff meet in Russia for Ukraine war talks
 Musk's SpaceX helps fuel stock market gains
 Authors urge UK to halt 'draconian' Palestine Action ban as Rooney sales end
 South Korea guides crowd-pulling shark out of canal
 PSG's Kvaratskhelia season in doubt after torn ACL
 President berates countries that 'insult' Indonesia over wildfires
 PSG's Kvaratskhelia set for months out with torn ACL
 Japan sends senior diplomat to Russia over detained journalist
 Rising UK inflation, debt knocks govt ahead of budget
 UK govt approves drilling in controversial Jackdaw gas field
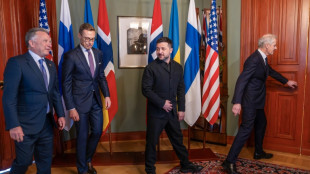 US envoy to meet Putin after 'positive' talks with Zelensky
To get a new tax break included in the One Big Beautiful Bill Act, some seniors need to lower their taxable income. Annuities can help do that.
MEDFORD, OR / ACCESS Newswire / January 8, 2026 / The "One Big Beautiful Bill" gives most people 65 and older a new deduction on their federal income taxes. To qualify, you can't exceed income limits. For some seniors, it can make sense to reduce their taxable income to qualify.
Through 2028, eligible taxpayers 65 and older can get an additional $6,000 deduction ($12,000 for a married couple if both spouses are 65). This is in addition to the usual extra deduction for seniors.
The full deduction applies to individuals with a modified adjusted gross income (MAGI) up to $75,000 and joint filers up to $150,000 MAGI. The deduction is reduced by six cents for every dollar above the threshold. For couples filing jointly, the deduction is fully phased out at $250,000. For single taxpayers, the deduction fully phases out with MAGI above $175,000.
"This is an additional deduction that will benefit the vast majority of seniors who do not itemize their deductions," says Ken Nuss, CEO of AnnuityAdvantage, an online annuity marketplace. "And, for seniors whose income is low enough, it will help reduce the tax on their Social Security benefits, in some cases to zero."
How Social Security benefits are taxed
The percentage of your Social Security benefits that are taxed is determined by your "combined income." To calculate it, add up your adjusted gross income (AGI), tax-free interest from municipal bonds if any, and 50% of your Social Security benefits.
Married couples with less than $32,000 of combined income pay no income tax on their benefits. Couples earning between $32,000 and $44,000 have up to 50 percent of their Social Security benefits subject to federal income tax. Those making more than $44,000 pay income tax on up to 85 percent of their benefits. For singles, the thresholds are $25,000 and $34,000.
The new deduction can lower your taxable income and thus your combined income. It's estimated that 90% of seniors will now pay no federal income tax on their Social Security benefits. Some other seniors will still pay the tax but at a lower rate.
Nonqualified deferred annuities can reduce your taxable income
There are many ways to reduce your taxable income to become eligible for the new seniors deduction. Buying one or more deferred annuities is a straightforward, dependable method that has other benefits, Nuss says.
A nonqualified deferred annuity is one that's held in a nonqualified account instead of a qualified account such as an IRA, Roth IRA or 401(k). Nonqualified variable, fixed, fixed index and deferred income annuities can all help reduce current income and taxes. As long as you don't withdraw any interest or gains from an annuity, you won't be taxed on it. You can defer taking out interest as long as you like.
Here's an example. Let's say you have $150,000 in funds to invest, and you want to put them in a guaranteed account. You could buy a bank certificate of deposit (CD). As of early January, the top rate for a 5-year CD was about 4.25%, and it would produce $6,375 of taxable income per year.
If you don't need that income for living expenses, you could place the $150,000 in a five-year multi-year guaranteed annuity (MYGA) instead. That would reduce your taxable income by $6,375 annually compared to the CD. Additionally, such a product, which acts much like a tax-deferred CD, produces more interest income because you could get up to 5.85% on your money and earn $8,775, tax-deferred.
Special IRA annuity defers RMDs and cuts current taxes
But that's not the only way to skin the cat.
Everyone must start taking required taxable minimum distributions (RMDs) from their IRA, 401(k) plan or other qualified retirement plan when they reach age 73. The only feasible way to defer some RMDs is to transfer a portion of your retirement-plan assets to a qualified longevity annuity contract (QLAC). The money in one is excluded from plan assets on which RMDs are calculated.
A QLAC is a special lifetime deferred income annuity that meets IRS requirements. It lets you keep more of your retirement plan intact and tax-deferred longer. You can place up to $210,000 in one or more of them. You must start taking taxable income payments from a QLAC at 85 but may begin sooner.
To purchase a QLAC, you transfer funds from your IRA or 401(k) or other eligible retirement plan to a life insurer. This single premium funds the QLAC. Since the transfer is from one plan custodian to another, it's tax-free.
Suppose you place $150,000 in a QLAC at age 73 and defer payments until age 80. That $150,000 is now removed from your annual RMD calculation. By reducing your current RMD income, you might be able to get all or a greater portion of the temporary senior credit.
If you need your entire RMDs to cover expenses, you won't be able to use this plan. You can buy a QLAC with as little as $10,000.
The other big advantage of the QLAC is that it's a lifetime annuity that guarantees a level income as long as you live. You can choose an individual or a joint lifetime payout, with the latter paying out income until the second spouse dies. The joint payee must be a spouse.
The additional senior deduction is scheduled to end in 2029, so it can be a good move for certain seniors to defer some income for the current tax year and the next three.
Ken Nuss is the founder and CEO of AnnuityAdvantage, a leading online provider of fixed-rate, fixed-indexed, and lifetime income annuities. Ken is a nationally recognized annuity expert and widely published author. A free rate comparison service with interest rates from dozens of insurers is available at www.annuityadvantage.com or by calling (800) 239-0356. The firm also offers an income-annuity quoting service. There are no fees or charges for the firm's services; 100% of the client's money goes to work for them in their annuity.
Media contact: Henry Stimpson, Stimpson Communications,
[email protected]
SOURCE: AnnuityAdvantage
View the original press release on ACCESS Newswire
Ch.P.Lewis--AT