Commencement Bancorp, Inc. (CBWA) Announces Second Quarter 2025 Results

 EU seeks deportation powers for beefed up border agency
 Two charged with UK security offences over airbase plot: police
 Maresca defends Donnarumma, Guehi after Man City defeat
 Nordic leaders call Putin as local truce begins in Ukraine
 Osaka unveils crane outfit in Tokyo before win over Paolini
 Ronaldo in line for Portugal return after fallout with coach
 Norway media take legal action to block Meta from using content
 Bayern praise 'humble' Kane after Ballon d'Or win
 Colts retain Daniel Jones as starter despite continued offensive struggles
 Madushanka wrecks Pakistan as Sri Lanka press for final slot
 Destructive Abhishek 113 leads India to series win over New Zealand
 Norway, Finland leaders hold 'frank and substantive' talk with Putin
 Wall Street faces earnings and Fed tests after turbulent technology-led week
 Ukraine, Russia say US-brokered truce holding in ravaged city
 Police form SIT after vehicles in Rahul Gandhi convoy collide on expressway
 Delhi grants minimum monthly pay and DA to about 4,000 MCD health workers
 Ather Energy shares climb 14% after quarterly profit and expansion plan
 Gold ETF flows turn negative after 13 weeks as bullion loses 4%
 Pakistan's last antique restorers give old treasures new life
 India braces for Cyclone Arnab with evacuations
 Steel Strips Wheels gains 36% in two sessions on growth outlook
 Cavs edge T'Wolves in overtime despite superb Edwards
 Prescott fires Cowboys to 38-21 win over plummeting Eagles
 Kuwait padel chief hails national showing at Premier Padel Major
 Britain prepares constrained budget as debt and defence pressures mount
2025 Second Quarter Financial Highlights:
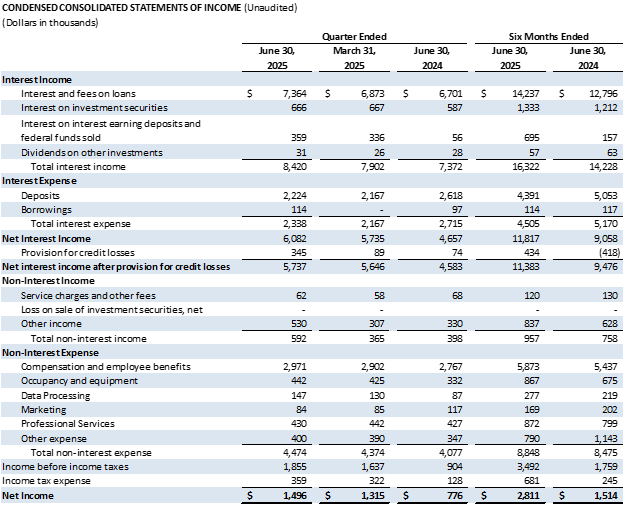
Net income was $1.5 million compared to $1.3 million for the first quarter of 2025 and $776,000 for the second quarter of 2024.
Loans receivable increased $37.9 million, or 32.4% annualized growth rate.
Deposits increased $20.5 million, or 14.4% annualized growth rate.
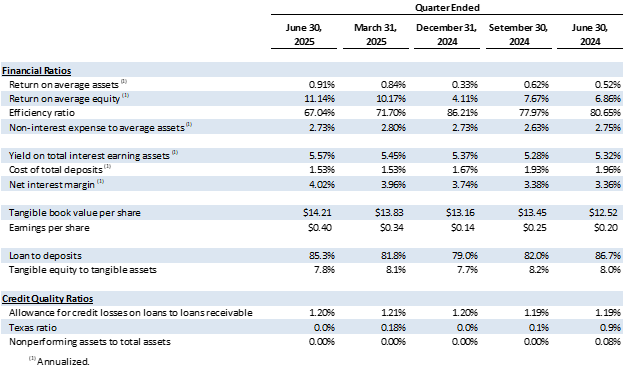
Net interest margin increased to 4.02% from 3.96% during the first quarter of 2025.
Total cost of deposits remained steady at 1.53%.
The Bank had no nonperforming assets as of June 30, 2025.
Capital ratios remained well above regulatory requirements.
TACOMA, WA / ACCESS Newswire / July 29, 2025 / Commencement Bancorp, Inc. (OTCQX:CBWA) (the "Company", "we," or "us"), the parent company of Commencement Bank (the "Bank") reported net income of $1.5 million, or $0.40 per share, for the second quarter of 2025, compared to $1.3 million, or $0.34 per share, for the first quarter of 2025 and $776,000, or $0.20 per share, for the second quarter of 2024.
"We are pleased with our continued net interest margin expansion in 2025, resulting in an improvement of 58 basis points over the same period in 2024. Due to the hard work of our bankers, we are reaping the rewards of higher loan volumes and increased yields, which when combined with our focus on managing our overall cost of funds, has resulted in improved profitability. Our capital and liquidity remain strong, and our reputation as the trusted local bank is allowing us to exceed our loan growth goals for the year," said John E. Manolides, Chief Executive Officer.
"Our bankers' calling activity and business development throughout the past several months has started to materialize, which was evidenced in the second quarter. I'm proud of their resilience while competing, building trust, and earning new lending, deposit, and treasury relationships. Our heightened brand and style of banking continues to resonate in the markets we serve, and it's rewarding to see our strong performance during the quarter," said Nigel L. English, President & Chief Operating Officer.
Balance Sheet
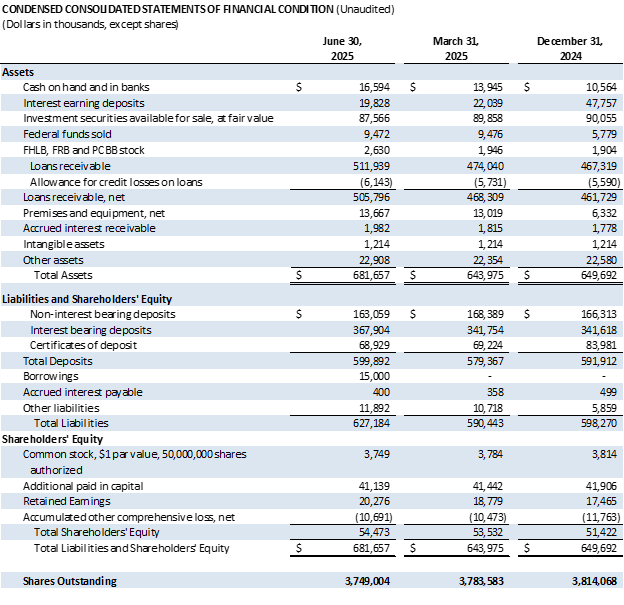
Total assets increased to $681.7 million at June 30, 2025 from $644.0 million at March 31, 2025 due to loan growth.
Investment securities available for sale decreased $2.3 million, or 2.6%, to $87.6 million at June 30, 2025 from $89.9 million at March 31, 2025. This decrease was due to principal payments and amortization of $2.2 million and an increase in unrealized losses of $88,000. The slight increase in market rates at June 30, 2025 caused the increase in unrealized losses.
Loans receivable increased $37.9 million, or 8.0%, to $511.9 million at June 30, 2025 from $474.0 million at March 31, 2025 due primarily to new loan originations, offset slightly by principal payments. The Bank originated commitments of $62.3 million during second quarter of 2025 compared to $20.8 million during the first quarter of 2025 and $27.3 million during the second quarter of 2024.
Total deposits increased $20.5 million, or 3.5%, to $599.9 million at June 30, 2025 from $579.4 million at March 31, 2025. Noninterest bearing deposits, as a percentage of total deposits, was 27.2% at June 30, 2025.
Total borrowings were $15.0 million at June 30, 2025 and represented a 3-month advance from the Federal Home Loan Bank ("FHLB") at a fixed rate of 4.50%. Borrowings were necessary during the second quarter of 2025 to fund higher than projected loan growth.
Credit Quality
The Bank had no nonperforming assets at June 30, 2025 or March 31, 2025. The allowance for credit losses to loan receivable remains strong at 1.20% at June 30, 2025.
The percentage of classified loans (loans rated Substandard or worse) to loans receivable improved to 1.69% at June 30, 2025 from 2.13% at March 31, 2025 due primarily to the payoff of two loan relationships. The Bank proactively downgrades loans if the borrower is experiencing financial difficulties.
Liquidity
The Bank has ample liquidity with both on- and off-balance sheet sources. Total on-balance sheet liquidity of $133.5 million, or 19.6% of total assets at June 30, 2025, includes cash and cash equivalents as well as unencumbered investment securities. The Bank had access to available Federal Home Loan Bank advances, Federal Reserve discount window, and federal fund lines with correspondent banks of $185.0 million at June 30, 2025.
Income Statement
Net interest income increased $347,000, or 6.1%, during the second quarter of 2025 compared to the first quarter of 2025 due to the increase in interest income of $518,000, offset by the increase in interest expense of $171,000. Net interest margin increased six basis points ("bps") to 4.02% during the second quarter of 2025 from 3.96% during the first quarter of 2025 and increased 66 bps from 3.36% during the second quarter of 2024.
Interest income on loans increased $491,000 during the second quarter of 2025 compared to the first quarter of 2025 due primarily to an increase in average balance of loans of $18.0 million. The yield on net loans increased 12 bps to 6.11% for the second quarter of 2025 from 5.99% for the first quarter of 2025 due to loan mix, higher yields on new originations, and repricing higher on existing portfolio rates.
Interest expense on deposits increased $57,000 during the second quarter of 2025 compared to the first quarter of 2025 due to an increase in the average balance of deposits of $8.2 million. Total cost of deposits was 1.53% for both the second quarter of 2025 and the first quarter of 2025.
Interest expense on borrowings increased to $114,000 during the second quarter of 2025. There was no borrowing expense during the first quarter of 2025 and $97,000 during the second quarter of 2024. The cost of the short-term funding will be augmented by dividends from the FHLB stock anticipated to be received during the third quarter of 2025.
Total non-interest income increased $227,000 during the second quarter of 2025 compared to the first quarter of 2025 due to the recognition of loan swap fee income of $188,000 and higher customer-related transactional activity in the second quarter of 2025.
Total non-interest expense increased $100,000, or 2.3%, during the second quarter of 2025 compared to the first quarter of 2025 due primarily to increase in compensation and employee benefits related to an increase in full-time equivalents and incentive compensation accrual. The second quarter of 2025 also includes three months of lease amortization and depreciation of assets related to the new Tacoma headquarters and final moving costs, as compared to one month of such costs during the first quarter of 2025.
###
About Commencement Bancorp, Inc.
Commencement Bancorp, Inc. is the holding company for Commencement Bank, headquartered in Tacoma, Washington. Commencement Bank was formed in 2006 to provide traditional, reliable, and sustainable banking in Pierce, King, and Thurston counties and the surrounding areas. Their team of experienced banking experts focuses on personal attention, flexible service, and building strong relationships with customers through state-of-the-art technology as well as traditional delivery systems. As a local bank, Commencement Bank is deeply committed to the community. For more information, please visit www.commencementbank.com. For information related to the trading of CBWA, please visit www.otcmarkets.com
For further discussion, please contact the following:
John E. Manolides,Chief Executive Officer | 253-284-1802
Nigel L. English, President & Chief Operating Officer | 253-284-1801
Brandi Parker, Executive Vice President & Chief Financial Officer | 253-284-1803
Forward-Looking Statement Safe Harbor: This news release contains comments or information that constitutes forward-looking statements (within the meaning of the Private Securities Litigation Reform Act of 1995) that are based on current expectations that involve a number of risks and uncertainties. Forward-looking statements describe Commencement Bancorp, Inc.'s projections, estimates, plans and expectations of future results and can be identified by words such as "believe," "intend," "estimate," "likely," "anticipate," "expect," "looking forward," and other similar expressions. They are not guarantees of future performance. Actual results may differ materially from the results expressed in these forward-looking statements, which because of their forward-looking nature, are difficult to predict. Investors should not place undue reliance on any forward-looking statement, and should consider factors that might cause differences including but not limited to the degree of competition by traditional and nontraditional competitors, declines in real estate markets, an increase in unemployment or sustained high levels of unemployment; changes in interest rates; greater than expected costs to integrate acquisitions, adverse changes in local, national and international economies; changes in the Federal Reserve's actions that affect monetary and fiscal policies; changes in legislative or regulatory actions or reform, including without limitation, the Dodd-Frank Wall Street Reform and Consumer Protection Act; demand for products and services; changes to the quality of the loan portfolio and our ability to succeed in our problem-asset resolution efforts; the impact of technological advances; changes in tax laws; and other risk factors. Commencement Bancorp, Inc.undertakes no obligation to publicly update or clarify any forward-looking statement to reflect the impact of events or circumstances that may arise after the date of this release.
SOURCE: Commencement Bank
View the original press release on ACCESS Newswire
L.Adams--AT