ESSA Bancorp, Inc. Announces Fiscal Second Quarter and Fiscal First Half 2025 Financial Results

 Marc Marquez on front row at Malaysian MotoGP as Martin ruled out
 Injured Martin out of Malaysian MotoGP in big title blow
 US, S.Korea, Japan vow 'complete' N.Korea denuclearization
 Nations commit to get nature goals back on track
 US oil companies aim to squeeze more out of refineries
 How to Repurpose Old Furniture into New Treasures
 Trump admin approves potential Patriot missiles sale to Ukraine
 Sun Goddess wins at Breeders' Cup, O'Brien leads Baffert
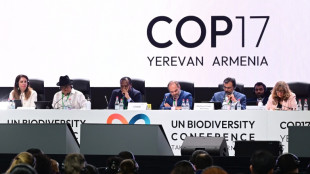 Nations agree push to get nature goals on track
 Leclerc shows practice pace as Antonelli prowls in Mexico
 Trump, Milei under pressure to explain Bolsonaro flight from Brazil
 Hakimi bags hat-trick as Paris Saint-Germain rip Le Havre to pieces
 Polish riot police deployed after court chief suspended
 Emery's focus fully on Fulham despite Barcelona tie
 Reigning champs chase history in New York Marathon
 Monaco taken off global money-laundering 'grey list'
 Canada, EU launch new alliance with deals on Ukraine, minerals, AI
 Tears, fear, anger: relatives of Spain train crash dead await fate
 Spurs get Maddison boost ahead of Palace clash
 French authorities fear new street violence at Halloween protests

 Rickelton, Mulder centuries lift South Africa's chances in Test decider

 Maresca adamant Donnarumma can be dropped but first name selected

 EU and Canada to 'withstand shocks together' with new alliance
 Flick praises Yamal 'mentality' after missing out on Ballon d'Or
 Binance heist: How were cryptocurrency billions stolen?
STROUDSBURG, PA / ACCESS Newswire / April 23, 2025 / ESSA Bancorp, Inc. (the "Company") (NASDAQ:ESSA), the holding company for ESSA Bank & Trust (the "Bank"), a $2.2 billion asset financial institution providing full service commercial and retail banking, asset management and trust, and investment services in eastern Pennsylvania, today announced financial results for the fiscal second quarter and fiscal first half periods ended March 31, 2025.
Net income was $2.7 million, or $0.29 per diluted share, for the three months ended March 31, 2025, compared with $4.6 million, or $0.48 per diluted share, for the three months ended March 31, 2024. Results for the quarter ended March 31, 2025 include pre-tax merger-related costs of $1.0 million. As previously announced, the Company entered an Agreement and Plan of Merger with CNB Financial Corporation, dated January 9, 2025. Excluding after-tax merger costs, net income was $3.8 million, or $0.40 per diluted share for the three months ended March 31, 2025.
Net income was $6.7 million, or $0.70 per diluted share, for the six months ended March 31, 2025, compared with $8.9 million, or $0.93 per diluted share, for the six months ended March 31, 2024. Excluding after-tax merger costs, net income was $7.7 million, or $0.81 per diluted share for the six months ended March 31, 2025.
Gary S. Olson, President and CEO, commented: "In our fiscal second quarter 2025, the Company continued to generate strong, positive operational results as ESSA progressed toward the anticipated closing of its merger with CNB Financial Corporation. On April 15, 2025, at a special meeting of ESSA shareholders, the merger received formal approval from ESSA Bancorp, Inc.'s shareholders".
Fiscal Second Quarter and First Half of 2025 Income Statement Review
Total interest income was $25.6 million for the second quarter of fiscal 2025 compared with $25.7 million the year earlier period, reflecting a slight decrease in average interest earning assets, offset in part, by an increase in the total yield on average interest earning assets to 5.01% from 4.95%.
Total interest income increased to $52.0 million for the six months ended March 31, 2025, compared with $51.7 million for the year earlier period, reflecting an increase in the total yield on average interest earning assets to 5.01% from 4.92%, offset in part, by a decrease in average interest earning assets.
Interest expense was $11.4 million for the second quarter of 2025, compared with $10.8 million for the same period in 2024, reflecting increased interest rates on deposits partially offset by declines in interest rates on short-term borrowings and in average interest-bearing liabilities. The Company's cost of interest-bearing liabilities was 2.80% in the second quarter of 2025 compared with 2.58% for the same quarter in 2024.
Interest expense was $23.7 million for the six months ended March 31, 2025, compared with $22.0 million for the same period in 2024, reflecting increased interest rates on deposits partially offset by declines in interest rates on short term borrowings and in average interest-bearing liabilities. The Company's cost of interest-bearing liabilities was 2.85% in the six months ended March 31, 2025, compared with 2.59% for the same period in 2024.
Net interest income before release of credit losses was $14.2 million in the second quarter of 2025 compared with $14.9 million in the second quarter of 2024. Net interest income before release of credit losses was $28.4 million in the first half of 2025 compared with $29.7 million in the first half of 2024.
The net interest margin for the second quarter of 2025 was 2.78% compared with 2.87% for the comparable period of fiscal 2024. For the three months ended March 31, 2025, including merger-related costs, the Company's return on average assets and return on average equity were 0.51% and 4.70%, compared with 0.84% and 8.23%, respectively, for the comparable period of fiscal 2024.
The net interest margin for the six months ended March 31, 2025, was 2.73% compared with 2.82% for the comparable period of fiscal 2024. For the six months ended March 31, 2025, including merger-related costs, the Company's return on average assets and return on average equity were 0.61% and 5.71%, compared with 0.80% and 8.04%, respectively, for the comparable period of fiscal 2024.
The release of credit losses decreased to $42,000 for the second quarter of fiscal 2025 compared to a release of $496,000 for the same fiscal quarter of 2024. The release of credit losses decreased to $649,000 for the six months ended March 31, 2025, compared to a release of $893,000 for the same period of 2024.
Noninterest income was $2.0 million for the second quarter of 2025 and 2024, respectively. The three-month year-over-year comparison reflected increases in service fees on loans, gain on sale of loans, net and trust and investment fees offset by decreases in loan swap fees and other noninterest income.
Noninterest income was $4.1 million for the six months ended March 31, 2025, compared with $4.0 million a year earlier. The six-month year-over-year comparison reflected increases in loan swap fees, earnings on bank owned life insurance and trust and investment fees, offset, in part, by decreases in service fees on loans, gain on sale of loans, net and other noninterest income.
Noninterest expense for the three months ended March 31, 2025 was $12.8 million compared to $11.7 million a year earlier. Noninterest expense for the three months ended March 31, 2025, excluding the $1.0 million in merger-related costs, was $11.8 million compared to $11.7 million for the year earlier period. Increases in compensation and employee benefits were partially offset by declines in advertising, FDIC insurance and other noninterest expenses.
Noninterest expense for the six months ended March 31, 2025, was $24.7 million compared to $23.6 million a year earlier. Noninterest expense for the six months ended March 31, 2025, excluding the $1.0 million in merger-related costs, was $23.7 million compared to $23.6 million for the year earlier period. Increases in compensation and employee benefits were partially offset by declines in advertising, FDIC insurance, foreclosed real estate and other noninterest expenses.
Balance Sheet, Asset Quality and Capital Adequacy Review
Total assets were $2.168 billion at March 31, 2025, compared to $2.188 billion at September 30, 2024. Growth in total net loans outstanding was more than offset by decreases in cash and cash equivalents, investment securities, regulatory stock and other assets.
Total net loans were $1.76 billion at March 31, 2025, up from $1.74 billion at September 30, 2024. Residential real estate loans were $734.8 million at March 31, 2025, compared with $721.5 million at September 30, 2024. Commercial real estate loans decreased to $870.8 million at March 31, 2025, compared with $884.6 million at September 30, 2024. Commercial loans (primarily commercial and industrial) were $48.6 million compared with $36.8 million at September 30, 2024. Loans to states and political subdivisions were $48.3 million at March 31, 2025, compared to $48.6 million at September 30, 2024. Consumer loans were $52.5 million at March 31, 2025, compared to $51.3 million at September 30, 2024.
Nonperforming assets were $11.7 million, or 0.54% of total assets at March 31, 2025, compared to $12.2 million, or 0.56% at September 30, 2024. The allowance for credit losses to total loans was 0.84% at March 31, 2025, compared to 0.87% at September 30, 2024. Foreclosed real estate was $3.7 million at March 31, 2025, and $3.2 million at September 30, 2024, reflecting two commercial properties the Company is actively marketing.
Total deposits were $1.69 billion at March 31, 2025, compared with $1.63 billion at September 30, 2024. Core deposits were $1.04 billion, or 62% of total deposits, at March 31, 2025, compared to $1.05 billion, or 64% of total deposits at September 30, 2024.
Noninterest bearing demand accounts at March 31, 2025, were $264.8 million, up 3.2% from September 30, 2024. Interest bearing demand accounts declined 8.6% to $285.8 million and money market accounts increased 4.0% to $348.2 million at March 31, 2025, from September 30, 2024. Certificates of deposit increased $65.4 million or 11.2% to $647.5 million at March 31, 2025, compared to September 30, 2024. Included in the certificates of deposit increase is an increase of $65.1 million in brokered certificates of deposit. Total borrowings decreased to $200.7 million at March 31, 2025, from $290.0 million at September 30, 2024.
The Bank maintained a strong capital position with a Tier 1 capital ratio of 10.3% at March 31, 2025, exceeding regulatory standards for a well-capitalized institution. Total stockholders' equity increased $6.1 million to $236.5 million at March 31, 2025, from $230.4 million at September 30, 2024, primarily reflecting net income growth and a decrease in other comprehensive loss, offset in part by dividends paid to shareholders. Tangible book value per share at March 31, 2025, was $21.93 compared to $21.40 at September 30, 2024.
About the Company: ESSA Bancorp, Inc. is the holding company for its wholly owned subsidiary, ESSA Bank & Trust, which was formed in 1916. The Company has total assets of $2.2 billion and has 20 community offices throughout the Lehigh Valley, Greater Pocono, Scranton/Wilkes-Barre, and suburban Philadelphia areas. ESSA Bank & Trust offers a full range of commercial and retail financial services, asset management and trust services, investment services through Ameriprise Financial Institutions Group and insurance benefit services through ESSA Advisory Services, LLC. ESSA Bancorp Inc. stock trades on the NASDAQ Global Market (SM) under the symbol "ESSA."
Forward-Looking Statements
Certain statements contained herein are "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. Such forward-looking statements may be identified by reference to a future period or periods, or by the use of forward-looking terminology, such as "may," "will," "believe," "expect," "estimate," "anticipate," "continue," or similar terms or variations on those terms, or the negative of those terms. Forward-looking statements are subject to numerous risks and uncertainties, including, but not limited to, those related to the status of our proposed merger with CNB Financial Corporation, economic environment, particularly in the market areas in which the Company operates, competitive products and pricing, fiscal and monetary policies of the U.S. Government, changes in government regulations affecting financial institutions, including compliance costs and capital requirements, changes in prevailing interest rates, the recent turmoil in the banking industry , credit risk management, asset-liability management, the financial and securities markets and the availability of and costs associated with sources of liquidity, and the Risk Factors disclosed in our annual, quarterly and current reports.
The Company wishes to caution readers not to place undue reliance on any such forward-looking statements, which speak only as of the date made. The Company wishes to advise readers that the factors listed above could affect the Company's financial performance and could cause the Company's actual results for future periods to differ materially from any opinions or statements expressed with respect to future periods in any current statements. The Company does not undertake and specifically declines any obligation to publicly release the result of any revisions that may be made to any forward-looking statements to reflect events or circumstances after the date of such statements or to reflect the occurrence of anticipated or unanticipated events.
Contact:
Gary S. Olson, President & CEO
Corporate Office: 200 Palmer Street
Stroudsburg, Pennsylvania 18360
Telephone: (570) 421-0531
ESSA BANCORP, INC. AND SUBSIDIARY
CONSOLIDATED BALANCE SHEET
(UNAUDITED)
March 31, | September 30, | |||||
2025 | 2024 | |||||
(dollars in thousands) | ||||||
ASSETS | ||||||
Cash and due from banks | $ | 26,553 | $ | 38,683 | ||
Interest-bearing deposits with other institutions | 2,999 | 9,897 | ||||
Total cash and cash equivalents | 29,552 | 48,580 | ||||
Investment securities available for sale, at fair value | 209,937 | 215,869 | ||||
(net of allowance for credit losses of $0) | ||||||
Investment securities held to maturity, at amortized cost | ||||||
(net of allowance for credit losses of $0) | 44,997 | 47,378 | ||||
Loans receivable (net of allowance for credit losses | ||||||
of $14,950 and $15,306) | 1,757,056 | 1,744,284 | ||||
Regulatory stock, at cost | 15,506 | 18,750 | ||||
Premises and equipment, net | 11,296 | 11,253 | ||||
Bank-owned life insurance | 40,020 | 39,571 | ||||
Foreclosed real estate | 3,667 | 3,195 | ||||
Goodwill | 13,801 | 13,801 | ||||
Deferred income taxes | 4,562 | 3,889 | ||||
Derivative and hedging assets | 7,586 | 8,203 | ||||
Other assets | 29,644 | 32,944 | ||||
TOTAL ASSETS | $ | 2,167,624 | $ | 2,187,717 | ||
LIABILITIES | ||||||
Deposits | $ | 1,689,754 | $ | 1,629,051 | ||
Short-term borrowings | 200,739 | 280,000 | ||||
Other borrowings | - | 10,000 | ||||
Advances by borrowers for taxes and insurance | 13,242 | 6,870 | ||||
Derivative and hedging liabilities | 7,126 | 9,183 | ||||
Other liabilities | 20,277 | 22,192 | ||||
TOTAL LIABILITIES | 1,931,138 | 1,957,296 | ||||
STOCKHOLDERS' EQUITY | ||||||
Common stock | 181 | 181 | ||||
Additional paid-in capital | 183,278 | 183,073 | ||||
Unallocated common stock held by the | ||||||
Employee Stock Ownership Plan ("ESOP") | (5,327 | ) | (5,557 | ) | ||
Retained earnings | 167,241 | 163,473 | ||||
Treasury stock, at cost | (103,826 | ) | (104,184 | ) | ||
Accumulated other comprehensive loss | (5,061 | ) | (6,565 | ) | ||
TOTAL STOCKHOLDERS' EQUITY | 236,486 | 230,421 | ||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 2,167,624 | $ | 2,187,717 | ||
ESSA BANCORP, INC. AND SUBSIDIARY
CONSOLIDATED STATEMENT OF OPERATIONS
(UNAUDITED)
Three Months Ended March 31, | Six Months Ended March 31, | |||||||||||||
2025 | 2024 | 2025 | 2024 | |||||||||||
(dollars in thousands, except per share data) | ||||||||||||||
INTEREST INCOME | ||||||||||||||
Loans receivable, including fees | $ | 22,520 | $ | 21,724 | $ | 45,513 | $ | 43,138 | ||||||
Investment securities: | ||||||||||||||
Taxable | 2,438 | 2,750 | 4,948 | 6,637 | ||||||||||
Exempt from federal income tax | 7 | 10 | 18 | 21 | ||||||||||
Other investment income | 667 | 1,166 | 1,525 | 1,944 | ||||||||||
Total interest income | 25,632 | 25,650 | 52,004 | 51,740 | ||||||||||
INTEREST EXPENSE | ||||||||||||||
Deposits | 9,813 | 7,590 | 20,142 | 16,052 | ||||||||||
Short-term borrowings | 1,530 | 3,064 | 3,285 | 5,720 | ||||||||||
Other borrowings | 79 | 142 | 223 | 250 | ||||||||||
Total interest expense | 11,422 | 10,796 | 23,650 | 22,022 | ||||||||||
NET INTEREST INCOME | 14,210 | 14,854 | 28,354 | 29,718 | ||||||||||
Release of credit losses | (42 | ) | (496 | ) | (649 | ) | (893 | ) | ||||||
NET INTEREST INCOME AFTER RELEASE OF | ||||||||||||||
CREDIT LOSSES | 14,252 | 15,350 | 29,003 | 30,611 | ||||||||||
NONINTEREST INCOME | ||||||||||||||
Service fees on deposit accounts | 665 | 674 | 1,380 | 1,370 | ||||||||||
Services charges and fees on loans | 329 | 295 | 609 | 625 | ||||||||||
Loan swap fees | 33 | 74 | 132 | 74 | ||||||||||
Unrealized loss on equity securities | (1 | ) | (2 | ) | - | (5 | ) | |||||||
Trust and investment fees | 435 | 418 | 910 | 811 | ||||||||||
Gain on sale of loans, net | 98 | 58 | 158 | 176 | ||||||||||
Earnings on bank-owned life insurance | 220 | 220 | 454 | 432 | ||||||||||
Insurance commissions | 125 | 134 | 245 | 262 | ||||||||||
Other | 113 | 133 | 187 | 220 | ||||||||||
Total noninterest income | 2,017 | 2,004 | 4,075 | 3,965 | ||||||||||
NONINTEREST EXPENSE | ||||||||||||||
Compensation and employee benefits | 6,880 | 6,673 | 14,080 | 13,419 | ||||||||||
Occupancy and equipment | 1,215 | 1,228 | 2,403 | 2,457 | ||||||||||
Professional fees | 1,133 | 1,039 | 2,096 | 2,064 | ||||||||||
Data processing | 1,432 | 1,360 | 2,900 | 2,702 | ||||||||||
Advertising | 168 | 239 | 272 | 375 | ||||||||||
Federal Deposit Insurance Corporation ("FDIC") | ||||||||||||||
premiums | 398 | 475 | 755 | 855 | ||||||||||
Foreclosed real estate | - | - | - | 101 | ||||||||||
Merger-related costs | 1,044 | - | 1,044 | - | ||||||||||
Amortization of intangible assets | - | 44 | - | 91 | ||||||||||
Other | 537 | 656 | 1,191 | 1,507 | ||||||||||
Total noninterest expense | 12,807 | 11,714 | 24,741 | 23,571 | ||||||||||
Income before income taxes | 3,462 | 5,640 | 8,337 | 11,005 | ||||||||||
Income taxes | 727 | 1,078 | 1,646 | 2,106 | ||||||||||
NET INCOME | $ | 2,735 | $ | 4,562 | $ | 6,691 | $ | 8,899 | ||||||
Earnings per share: | ||||||||||||||
Basic | $ | 0.29 | $ | 0.48 | $ | 0.70 | $ | 0.93 | ||||||
Diluted | $ | 0.29 | $ | 0.48 | $ | 0.70 | $ | 0.93 | ||||||
Dividends per share | $ | 0.15 | $ | 0.15 | $ | 0.30 | $ | 0.30 | ||||||
For the Three Months | For the Six Months | |||||||||||||
Ended March 31, | Ended March 31, | |||||||||||||
2025 | 2024 | 2025 | 2024 | |||||||||||
(unaudited) | ||||||||||||||
(dollars in thousands, except per share data) | ||||||||||||||
CONSOLIDATED AVERAGE BALANCES: | ||||||||||||||
Total assets | $ | 2,183,673 | $ | 2,191,544 | $ | 2,192,408 | $ | 2,213,976 | ||||||
Total interest-earning assets | 2,076,180 | 2,077,074 | 2,083,259 | 2,099,284 | ||||||||||
Total interest-bearing liabilities | 1,654,509 | 1,675,831 | 1,663,953 | 1,698,571 | ||||||||||
Total stockholders' equity | 236,216 | 222,906 | 234,823 | 221,265 | ||||||||||
PER COMMON SHARE DATA: | ||||||||||||||
Average shares outstanding - basic | 9,537,210 | 9,513,656 | 9,570,264 | 9,575,730 | ||||||||||
Average shares outstanding - diluted | 9,560,278 | 9,513,798 | 9,592,682 | 9,575,730 | ||||||||||
Book value shares | 10,154,664 | 10,131,521 | 10,154,664 | 10,131,521 | ||||||||||
Net interest rate spread: | 2.21 | % | 2.37 | % | 2.16 | % | 2.33 | % | ||||||
Net interest margin: | 2.78 | % | 2.87 | % | 2.73 | % | 2.82 | % | ||||||
SOURCE: ESSA Bancorp Inc.
View the original press release on ACCESS Newswire
B.Torres--AT