
Solera National Bancorp Announces First Quarter 2025 Financial Results

 Scam centres relocated from Cambodia operate in Madagascar
 Marc Marquez on front row at Malaysian MotoGP as Martin ruled out
 Injured Martin out of Malaysian MotoGP in big title blow
 US, S.Korea, Japan vow 'complete' N.Korea denuclearization
 Nations commit to get nature goals back on track
 US oil companies aim to squeeze more out of refineries
 How to Repurpose Old Furniture into New Treasures
 Trump admin approves potential Patriot missiles sale to Ukraine
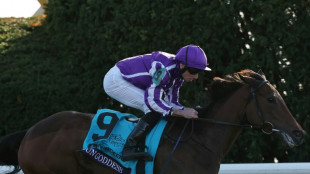 Sun Goddess wins at Breeders' Cup, O'Brien leads Baffert
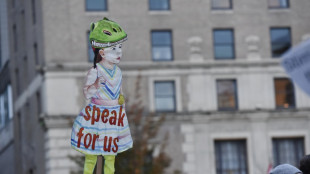
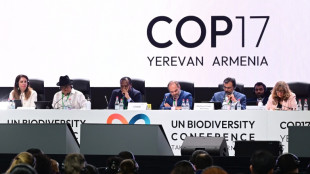 Nations agree push to get nature goals on track
 Leclerc shows practice pace as Antonelli prowls in Mexico
 Trump, Milei under pressure to explain Bolsonaro flight from Brazil
 Hakimi bags hat-trick as Paris Saint-Germain rip Le Havre to pieces
 Polish riot police deployed after court chief suspended
 Emery's focus fully on Fulham despite Barcelona tie
 Reigning champs chase history in New York Marathon
 Monaco taken off global money-laundering 'grey list'
 Canada, EU launch new alliance with deals on Ukraine, minerals, AI
 Tears, fear, anger: relatives of Spain train crash dead await fate
 Spurs get Maddison boost ahead of Palace clash
 French authorities fear new street violence at Halloween protests

 Rickelton, Mulder centuries lift South Africa's chances in Test decider

 Maresca adamant Donnarumma can be dropped but first name selected

 EU and Canada to 'withstand shocks together' with new alliance
 Flick praises Yamal 'mentality' after missing out on Ballon d'Or
Net income of $4.6 million ($1.08 per share), a $1.6 million or 54% increase from Q1 2024.
Q1 2025 pre-tax and pre-provision income of $6.4 million. 3rd best quarter!
LAKEWOOD, CO / ACCESS Newswire / April 21, 2025 / Solera National Bancorp, Inc. (OTC PINK:SLRK) ("Company"), the holding company for Solera National Bank ("Bank"), a business-focused bank located in the Denver metropolitan area, today reported financial results for the three months ended March 31, 2025. See highlights below.
1Q25 Financial Highlights
Net income of $4.6 million ($1.08 per share), a $1.6 million or 54% increase from Q1 2024.
Net interest margin has improved 53 bps to 3.93% vs Q1 2024.
Solera had a pre-tax and pre-provision income of $6.4 million. 19% or $1.0 million increase from Q1 24.
Cost of funds has decreased to 2.49%, an improvement of 28 bps from Q1 2024.
Return on assets was 1.62%, a 65 bps improvement from Q1 2024.
Return on equity was 20.64%, a 561 bps improvement from Q1 2024.
Efficiency ratio was 44.31%, a 418 bps improvement from Q1 2024.
Mike Quagliano, Executive Chairman of the Board, commented: "We are $1.6M above last year, and we are off to a great start."
Steve Snailum, COO, commented: "Operational efficiency continues to be a tremendous strength for Solera. Through continuous process improvements and technological advancements, the team has been able to drive record-breaking customer outcomes. The average hold time to engage with one of our representatives is now below 30 seconds, and customer feedback remains extremely positive. It is easier than ever to become a customer of Solera, and once you are here, you will love your experience."
Avram Shabanyan, EVP, commented: "During my six years with Solera Bank, I've been proud to work closely with our self-directed partners-connecting customers to innovative banking products and expert support as they use their retirement accounts to invest in alternative assets. Solera Bank remains the industry leader in self-directed banking because we always put the customer first."
Jay Hansen, Chief Financial Officer, commented: "Our goal was to get to a 10% Tier 1 capital ratio, and we got to 10.4%. See my previous Q4 comment. We will take advantage of the very high treasury yields and improve our investment returns. The tariffs present some uncertainty in the market, but I believe we are well-positioned and have an amazing team and customers."
About Solera National Bancorp, Inc.
Solera National Bancorp, Inc. was incorporated in 2006 to organize and serve as the holding company for Solera National Bank, which opened for business in September 2007. Solera National Bank is a community bank serving the needs of emerging businesses and real estate investors. At the core of Solera National Bank is welcoming, attentive, and respectful customer service, a focus on supporting a growing and diverse economy, and a passion to serve our community through service, education, and volunteerism. For more information, please visit http://www.SoleraBank.com.
This press release contains statements that may constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. The statements contained in this release, which are not historical facts and that relate to future plans or projected results of Solera National Bancorp, Inc. and its wholly-owned subsidiary, Solera National Bank, are forward-looking statements. These forward-looking statements are subject to risks and uncertainties that could cause actual results to differ materially from those projected, anticipated, or implied. We undertake no obligation to update or revise any forward-looking statement. Readers of this release are cautioned not to put undue reliance on forward-looking statements.
Contacts: Jay Hansen, CFO (303) 209-8600
FINANCIAL TABLES FOLLOW
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED BALANCE SHEET
(unaudited)
($000s) | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | |||||
ASSETS | ||||||||||
Cash and due from banks | $ | 2,401 | $ | 1,576 | $ | 2,193 | $ | 2,241 | $ | 2,095 |
Federal funds sold | - | 800 | 400 | - | - | |||||
Interest-bearing deposits with banks | 1,033 | 148 | 595 | 844 | 1,079 | |||||
Investment securities, available-for-sale | 290,397 | 322,375 | 317,180 | 183,311 | 185,120 | |||||
Investment securities, held-to-maturity | - | - | - | 200,457 | 200,575 | |||||
FHLB and Federal Reserve Bank stocks, at cost | 5,525 | 7,457 | 3,204 | 10,959 | 7,952 | |||||
Paycheck Protection Program (PPP) loans, gross | 5 | 20 | 35 | 50 | 65 | |||||
Traditional loans, gross | 766,687 | 792,753 | 797,516 | 792,739 | 820,936 | |||||
Allowance for loan and lease losses | (10,914 | ) | (10,913 | ) | (10,912 | ) | (10,810 | ) | (10,808 | ) |
Net traditional loans | 755,773 | 781,840 | 786,604 | 781,929 | 810,128 | |||||
Premises and equipment, net | 33,236 | 33,476 | 32,289 | 30,625 | 29,448 | |||||
Accrued interest receivable | 7,153 | 7,750 | 6,940 | 7,808 | 7,807 | |||||
Bank-owned life insurance | 5,159 | 5,127 | 5,095 | 5,063 | 5,033 | |||||
Other assets | 11,103 | 8,820 | 8,734 | 8,325 | 8,607 | |||||
TOTAL ASSETS | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 | $ | 1,231,612 | $ | 1,257,909 |
LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||
Noninterest-bearing demand deposits | $ | 466,455 | $ | 484,604 | $ | 497,661 | $ | 503,819 | $ | 508,615 |
Interest-bearing demand deposits | 60,507 | 54,734 | 64,606 | 62,905 | 53,514 | |||||
Savings and money market deposits | 104,560 | 100,987 | 103,118 | 102,892 | 255,655 | |||||
Time deposits | 287,378 | 294,338 | 353,405 | 272,744 | 240,047 | |||||
Total deposits | 918,900 | 934,663 | 1,018,790 | 942,360 | 1,057,831 | |||||
Accrued interest payable | 1,808 | 2,587 | 2,618 | 2,104 | 1,347 | |||||
Short-term borrowings | 60,191 | 104,607 | 13,300 | 164,613 | 79,104 | |||||
Long-term FHLB borrowings | 34,000 | 34,000 | 34,000 | 34,000 | 34,000 | |||||
Accounts payable and other liabilities | 6,087 | 4,576 | 5,395 | 3,961 | 4,659 | |||||
TOTAL LIABILITIES | 1,020,987 | 1,080,434 | 1,074,104 | 1,147,038 | 1,176,941 | |||||
Common stock | 43 | 43 | 43 | 43 | 43 | |||||
Additional paid-in capital | 38,763 | 38,748 | 38,748 | 38,778 | 38,763 | |||||
Retained earnings | 77,076 | 72,455 | 67,163 | 61,667 | 57,440 | |||||
Accumulated other comprehensive (loss) gain | (25,084 | ) | (22,291 | ) | (16,789 | ) | (15,914 | ) | (15,278 | ) |
TOTAL STOCKHOLDERS' EQUITY | 90,798 | 88,955 | 89,165 | 84,574 | 80,968 | |||||
TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $ | 1,111,785 | $ | 1,169,389 | $ | 1,163,269 | $ | 1,231,612 | $ | 1,257,909 |
SOLERA NATIONAL BANCORP, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
Three Months Ended | |||||||||||||||||||
($000s, except per share data) | 3/31/25 | 12/31/24 | 9/30/24 | 6/30/24 | 3/31/24 | ||||||||||||||
Interest and dividend income | |||||||||||||||||||
Interest and fees on traditional loans | $ | 13,102 | $ | 13,615 | $ | 13,854 | $ | 13,270 | $ | 13,277 | |||||||||
Interest and fees on PPP loans | (1 | ) | - | - | - | - | |||||||||||||
Investment securities | 3,490 | 3,297 | 3,544 | 3,721 | 3,693 | ||||||||||||||
Dividends on bank stocks | 175 | 131 | 160 | 249 | 224 | ||||||||||||||
Other | 49 | 13 | 19 | 22 | 30 | ||||||||||||||
Total interest income | $ | 16,815 | $ | 17,056 | $ | 17,577 | $ | 17,262 | $ | 17,224 | |||||||||
Interest expense | |||||||||||||||||||
Deposits | 4,959 | 5,564 | 6,312 | 5,285 | 5,833 | ||||||||||||||
FHLB & Fed borrowings | 1,550 | 1,223 | 1,332 | 2,831 | 2,200 | ||||||||||||||
Total interest expense | 6,509 | 6,787 | 7,644 | 8,116 | 8,033 | ||||||||||||||
Net interest income | 10,306 | 10,269 | 9,933 | 9,146 | 9,191 | ||||||||||||||
Provision for loan and lease losses | 7 | 6 | 105 | 4 | 1,203 | ||||||||||||||
Net interest income after provision for loan and lease losses | 10,299 | 10,263 | 9,828 | 9,142 | 7,988 | ||||||||||||||
Noninterest income | |||||||||||||||||||
Customer service and other fees | 300 | 470 | 389 | 468 | 443 | ||||||||||||||
Other income | 807 | 954 | 1,138 | 738 | 616 | ||||||||||||||
Gain on sale of securities | - | - | 858 | - | 60 | ||||||||||||||
Total noninterest income | 1,107 | 1,424 | 2,385 | 1,206 | 1,119 | ||||||||||||||
Noninterest expense | |||||||||||||||||||
Employee compensation and benefits | 2,656 | 2,611 | 2,472 | 2,514 | 2,418 | ||||||||||||||
Occupancy | 448 | 492 | 393 | 387 | 401 | ||||||||||||||
Professional fees | 259 | 309 | 122 | 75 | 495 | ||||||||||||||
Other general and administrative | 1,694 | 1,437 | 1,423 | 1,582 | 1,656 | ||||||||||||||
Total noninterest expense | 5,057 | 4,849 | 4,410 | 4,558 | 4,970 | ||||||||||||||
Net Income Before Taxes | $ | 6,349 | $ | 6,838 | $ | 7,803 | $ | 5,790 | $ | 4,137 | |||||||||
Income Tax Expense | 1,711 | 1,526 | 2,294 | 1,564 | 1,118 | ||||||||||||||
Net Income | $ | 4,638 | $ | 5,312 | $ | 5,509 | $ | 4,226 | $ | 3,019 | |||||||||
Income Per Share | $ | 1.08 | $ | 1.24 | $ | 1.28 | $ | 0.98 | $ | 0.70 | |||||||||
Tangible Book Value Per Share | $ | 21.12 | $ | 20.69 | $ | 20.74 | $ | 19.67 | $ | 18.83 | |||||||||
WA Shares outstanding | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | 4,299,953 | ||||||||||||||
Pre-Tax Pre-Provision Income | $ | 6,356 | $ | 6,844 | $ | 7,908 | $ | 5,794 | $ | 5,340 | |||||||||
Net Interest Margin | 3.93 | % | 3.81 | % | 3.67 | % | 3.39 | % | 3.40 | % | |||||||||
Cost of Funds | 2.49 | % | 2.51 | % | 2.72 | % | 2.80 | % | 2.77 | % | |||||||||
Efficiency Ratio | 44.31 | % | 41.47 | % | 38.48 | % | 44.03 | % | 48.49 | % | |||||||||
Return on Average Assets | 1.63 | % | 1.82 | % | 1.84 | % | 1.36 | % | 0.97 | % | |||||||||
Return on Average Equity | 20.64 | % | 23.86 | % | 25.37 | % | 20.42 | % | 15.05 | % | |||||||||
Leverage Ratio | 10.4 | % | 9.5 | % | 9.1 | % | 8.2 | % | 7.7 | % | |||||||||
Asset Quality: | |||||||||||||||||||
Non-performing loans to gross loans | 0.42 | % | 0.52 | % | 0.65 | % | 0.48 | % | 0.53 | % | |||||||||
Non-performing assets to total assets | 0.29 | % | 0.35 | % | 0.45 | % | 0.31 | % | 0.34 | % | |||||||||
Allowance for loan losses to gross traditional loans | 1.42 | % | 1.38 | % | 1.37 | % | 1.36 | % | 1.32 | % | |||||||||
* Not meaningful due to the insignificant amount of non-performing loans. | |||||||||||||||||||
Criticized loans/assets: | |||||||||||||||||||
Special mention | $ | 11,103 | $ | 10,730 | $ | 29,145 | $ | 25,244 | $ | 35,997 | |||||||||
Substandard: Accruing | 19,641 | 14,911 | 22,410 | 23,030 | 19,108 | ||||||||||||||
Substandard: Nonaccrual | 3,251 | 4,142 | 5,180 | 3,784 | 4,332 | ||||||||||||||
Doubtful | - | - | - | - | - | ||||||||||||||
Total criticized loans | $ | 33,995 | $ | 29,782 | $ | 56,735 | $ | 52,058 | $ | 59,437 | |||||||||
Other real estate owned | - | - | - | - | - | ||||||||||||||
Investment securities | - | - | - | - | - | ||||||||||||||
Total criticized assets | $ | 33,995 | $ | 29,782 | $ | 56,735 | $ | 52,058 | $ | 59,437 | |||||||||
Criticized assets to total assets | 3.06 | % | 2.55 | % | 4.88 | % | 4.23 | % | 4.73 | % | |||||||||
SOURCE: Solera National Bank
View the original press release on ACCESS Newswire
W.Nelson--AT