Step-by-Step Guide on How to Calculate Vehicle Payments

 Marquez wins in Malaysia to stand on brink of MotoGP world title
 Binance says resuming withdrawals after major hack
 Divided Bulgaria votes in tense presidential runoff
 Trump says US looking 'closely' at report Nvidia CEO target of China spy plot
 Maxey scores 38 to lead Sixers 'fighters' to another comeback win
 Valkyries defeat Dream to capture first WNBA crown
 'Seen and heard': Uruguay neighborhood places hopes in pope
 Spewing US election falsehoods, AI chatbots face scrutiny
 EU's new levy on parcels kicks in
 Ocon denies reports of altercation after being dumped by Haas
 Hamilton says love of racing keeps him young
 'Disgraceful' Australia face reckoning after South Africa humbling
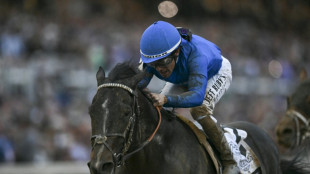 Sovereignty wins Breeders' Cup Classic, Benvenuto Cellini triumphs in Turf for O'Brien
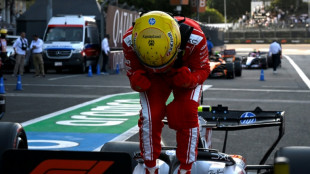 Hamilton takes record 105th pole and first for Ferrari, as Antonelli lurks
 German rioters loot shops as 'Gen Z' demos turn ugly
 Barca hammer Alaves to retain Liga top spot
 UK king to address Commonwealth with 'unflinching honesty' amid slavery focus
 US judge dismisses Trump lawsuit against Wall Steet Journal over Epstein letter
 Polish president holds crisis talks in court standoff
 NFL to review new allegations against Packers' Jacobs: reports
 Le Havre owners sack coach after PSG thrashing
 De Minaur upsets Zverev and will face Alacaraz in Vienna final
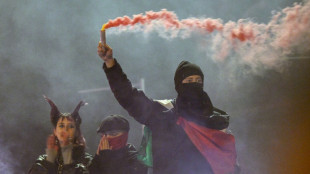 German police, protesters clash after 'Gen Z' demos
 Fresh frustration for Maresca as Man City lose to Brighton
 Norris fastest ahead of Antonelli in final Mexico practice
NEW YORK CITY, NY / ACCESS Newswire / March 20, 2025 / Purchasing a vehicle often involves financing, which makes understanding your monthly payments prior to the purchase crucial. Whether you're considering a new car or a used one, knowing how to calculate vehicle payments helps ensure you stay within your budget and avoid surprises. Here's a comprehensive, step-by-step guide to help you calculate your vehicle's payments with ease.
1. Understand the components of your loan
To calculate your monthly vehicle payment, you must first consider the parts that make up the loan, including the:
Loan amount: The total cost of the car minus any down payment and trade-in value.
Loan term: The length of the loan, usually expressed in months (36, 48, 60 or 72 months).
Interest rate: The cost to borrow the money, expressed as a percentage of the loan.
Taxes and fees: Additional costs like sales tax, registration fees and dealer charges, which may be rolled into the loan amount.
2. Know how your payments are applied
Each monthly payment is divided into two parts:
Principal: The amount that goes toward reducing the loan balance.
Interest: The cost of borrowing the money.
In the early stages of the loan, a larger portion of your payment goes toward interest, while the amount contributed to the principal increases over time. By the end of the loan term, the total interest paid can significantly impact the overall cost of the vehicle.
To find out how much of your monthly payment goes to principal and interest, request an amortization schedule from your lender. This schedule will also show the total principal paid and total interest paid by the end of the loan.
3. Determine monthly interest
Interest on a car loan is calculated based on the principal amount, the interest rate and the loan term. Most car loans use simple interest, meaning interest is calculated on the remaining loan balance, not the original loan amount. So, in the early days when the balance is higher, you'll pay more interest. As you pay down the balance, the interest portion of the monthly payments gets smaller.
The standard formula to calculate your monthly loan interest is:
Monthly interest = (interest rate/12) x loan balance
For example, if your loan balance is $20,000 with a 5% APR, your monthly interest rate is about $83. If your loan is $30,000 with a 5% APR, your monthly interest rate is about $125. If you have an interest rate of 10%, you'd pay about $167 per month for a $20,000 loan and $250 for a $30,000 loan.
It's important to shop around to find the best interest rate possible to help keep your monthly interest rate payments low.
4. Calculate monthly vehicle payments
To calculate your monthly car loan payment, you need to determine both the loan amount and the interest over the loan term.
For example, the total interest on a $30,000, 60-month loan at 10% APR would be $9,149.34, and your monthly payment would be $638.99.
You can also use the amortization schedule provided by your lender or an online loan payment or amortization calculator.
When calculating your payments, remember to factor in any additional costs, including sales tax and fees. Also, be sure to subtract the total of a down payment (if you provide one). Making a larger down payment decreases the amount you'll need to borrow, which can lower your payments.
CONTACT:
Sonakshi Murze
Manager
[email protected]
SOURCE: iQuanti
View the original press release on ACCESS Newswire
O.Ortiz--AT