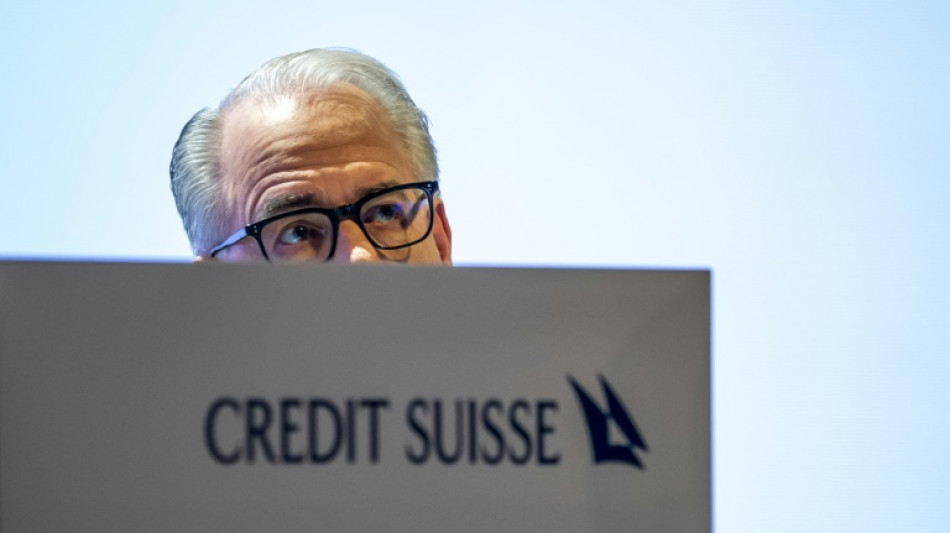
Credit Suisse chiefs say sorry to shocked shareholders / Photo: Fabrice COFFRINI - AFP

 British PM says to make 'difficult decisions' as inflation rises
 TotalEnergies pumps up controversy in France with cut-price gas
 Global fuel price demos: a round-up
 Leverate Launches MCP for Traders to Connect AI Assistants With Trading Platforms
 MEXC Launches $1M "Discover Your Wall Street DNA" Campaign to Help Traders Find Their Market Fit
 Emporio Armani names Dario Vitale new creative director
 Maresca defends VAR officials after Man City benefit from error
 Courts jails LGBTQ activists as Turkey crackdown widens
 French court to hear Depardieu's appeal against rape trial order: sources
 The German state premier hoping to halt far-right surge
 Lebanon wants Israel security deal as prelude to peace: president to AFP
 England's Brook keen to learn from 'hero' Pietersen after stunning ton
 Saudi says Houthis target Mecca, warns of 'red line'
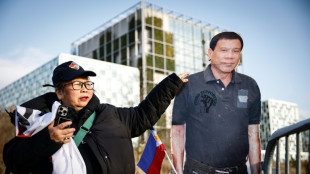
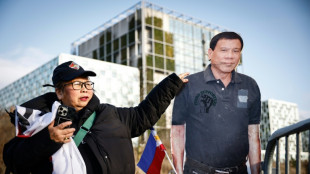 Phillippines ex-leader Duterte makes first appearance at ICC
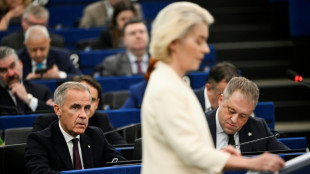
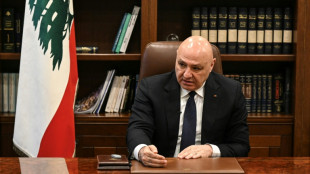 Lebanon wants Israel security deal, Hezbollah disarmament without confrontation: president to AFP
 BASIS.pro Expands On-Chain Infrastructure with XDC Network Partnership and Zypher DAO as Auto Earn Goes Live
 Samson relishing battle with teen star Sooryavanshi for India spot
 Pickle-flavoured tart? AI inspires Japan's convenience stores
 Macau holds first closed-door national security trial
 Bank of Japan set to raise rates under pressure from inflation, US
 Zverev, Shelton back on court for Davis Cup qualifiers
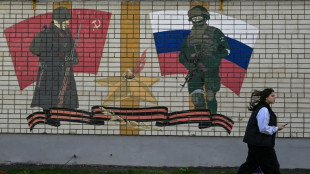 Peace is a 'dangerous' word in Russian city heading to polls
 Meta chief pushes back on AI slowdown calls
 'Resident Evil' film brings video game's ethos to the big screen
 Court orders N. Korea pay Seoul $32.5 mn for blowing up office
Credit Suisse chairman Axel Lehmann said Tuesday he was "truly sorry" that the beleaguered bank could not be saved as he faced angry and tearful shareholders whose money has gone up in smoke.
Credit Suisse's chiefs fronted up at the bank's annual general meeting, 16 days after its hastily-arranged takeover by larger Swiss rival UBS -- a mega-merger in which the shareholders of both banks had no say at all.
The 167-year-old bank's final AGM was the first chance Credit Suisse shareholders had to voice their frustrations, and some turned up in tears as they counted the cost of the bank's implosion.
"I can understand the bitterness, the anger and the shock of all those who are disappointed, overwhelmed and affected by the developments," Lehmann said at the Hallenstadion, Zurich's biggest indoor arena.
With the bank's share price in free-fall and fearing an imminent collapse that could have triggered an international banking crisis, the Swiss government, the central bank and the financial regulators strongarmed UBS into taking over Credit Suisse on March 19.
"We wanted to put all our energy and our efforts into turning the situation around," said Lehmann, who was brought in as chairman in January 2022 to fix the bank following a string of scandals that sapped investor confidence.
"It pains me that we didn't have the time to do so and in that fateful week in March our plans were thwarted -- and for that I am truly sorry," he said.
"I apologise that we were no longer able to stem the loss of trust that has accumulated over the years and for disappointing you."
- Family's money evaporated -
Thanks to those scandals, shareholders have seen the value of their investment plunge from 12.78 Swiss francs per share in February 2021 to the 0.76 francs they will receive in the $3.25-billion merger.
"I am angry and I lost 10,000 Swiss francs ($11,000). It's not so much but it's not good. It's (a lot of) money for my family," Stephan Denzler told AFP, tears forming in his eyes.
"This is a historical moment and this the reason that I want to be at this assembly."
Chief executive Ulrich Koerner said it would be the bank's last ordinary general meeting.
UBS -- which faces its own annual general meeting in Basel on Wednesday -- is the biggest bank in Switzerland, with Credit Suisse in second place.
They are both among the 30 worldwide Global Systemically Important Banks -- deemed of such importance to the international banking system that they are considered too big to fail.
But the markets saw Credit Suisse -- which suffered a net loss of $7.9 billion in 2022 -- as a weak link in the global chain following the collapse of three US regional banks in early March.
- 'Deep personal regret': CEO -
The bank's share price plunged by more than 30 percent on March 15 to a record low of 1.55 Swiss francs.
Despite reassurances, shares recovered little ground to close the week at 1.86 francs on March 17.
Fearing what might happen when the markets reopened on March 20, the Swiss government then sprung into action to patch a deal together with UBS.
Credit Suisse has been a part of Switzerland's national identity for 167 years, but nevertheless, "the bank could not be saved", Lehmann insisted.
"Ultimately there were only two options: deal or bankruptcy. The merger had to go through. The terms had to be accepted."
Koerner said he was deeply saddened at the end of Credit Suisse, but said the takeover by UBS was the only feasible solution.
"This fills me with sorrow," he said.
"This is a matter of deep personal regret to me. But the bank's survival was at stake and we... no longer had a choice.
"The collapse of Credit Suisse would have been disastrous, not just for Switzerland but for the global economy at large."
T.Perez--AT